42Flows new positioning for a rewards platform — from the client’s hypotheses to a website that took it to market
In brief
42Flows is a team that built banking systems for tens of millions of customers and now sells banks its own rewards platform. The technology was strong, but sales revolved around a cashback module, and the old landing page read like a crypto project.
We started working with 42Flows as a marketing partner and owned their marketing: we supported the business and took on the tasks of a marketing director. Along the way, the team came up with new hypotheses — the product is bigger than cashback, it’s a rewards platform. We backed them, validated them in a strategic session and interviews, and turned them into a new positioning.
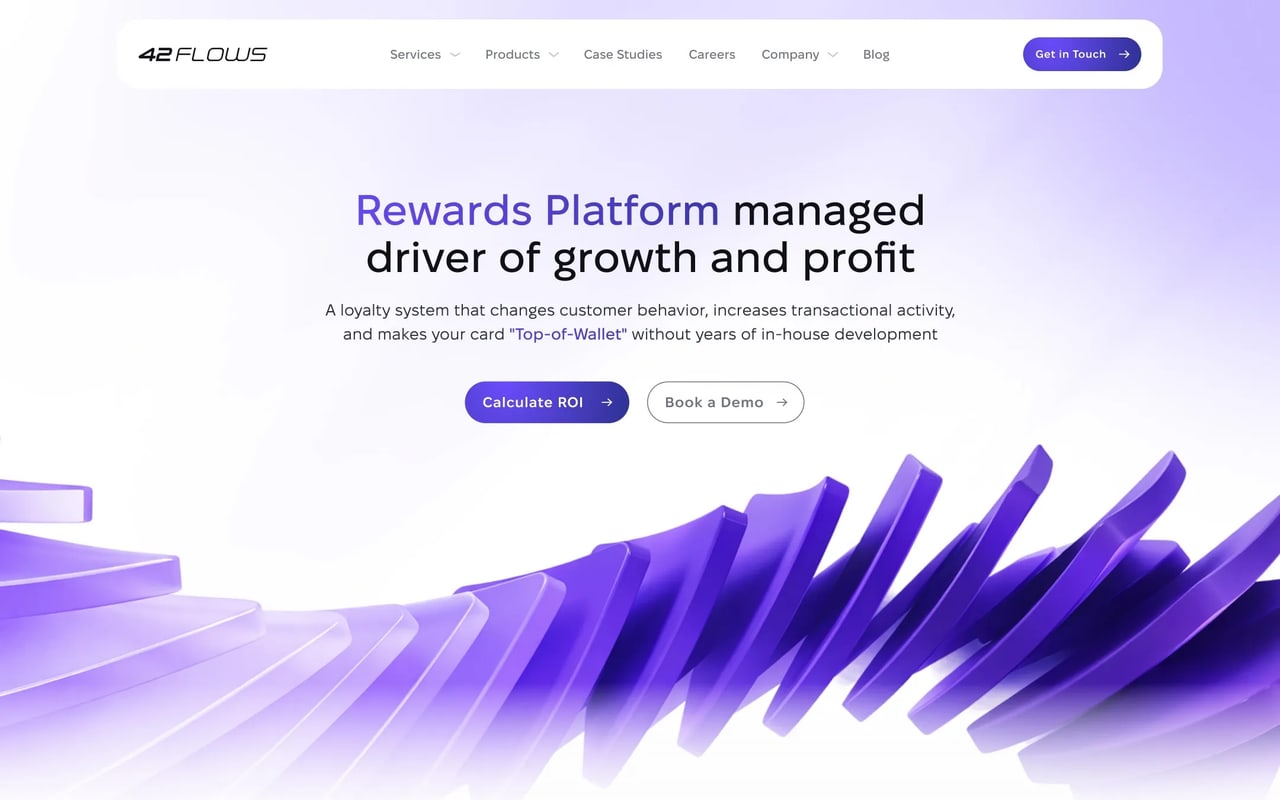
The website was the natural next step: a Rewards Platform page that proves the new position, speaks to banks in the language of money and takes the positioning to market. The identity for posts and other materials grew out of it.
Key points
We came in as a marketing partner. The website grew out of the new positioning
-
01 · Start
Marketing partner
We owned marketing at 42Flows. At the time, sales revolved around the cashback module.
-
02 · Turn
Hypotheses about a rewards platform
The team saw that the product was bigger than cashback. We tested this in a strategic session and interviews — and built the Rewards Platform positioning.
-
03 · Solution
A website that launches the positioning
The product page turns the new position into sales, and the identity grew out of it.
Before
A technically strong product that read like crypto
For a rewards platform that handles a bank’s money, noise means distrust. All-caps headlines added tension, clip art created a sense of “decorative fintech,” and the main argument relied on third-party research with no link to value for the bank.
-
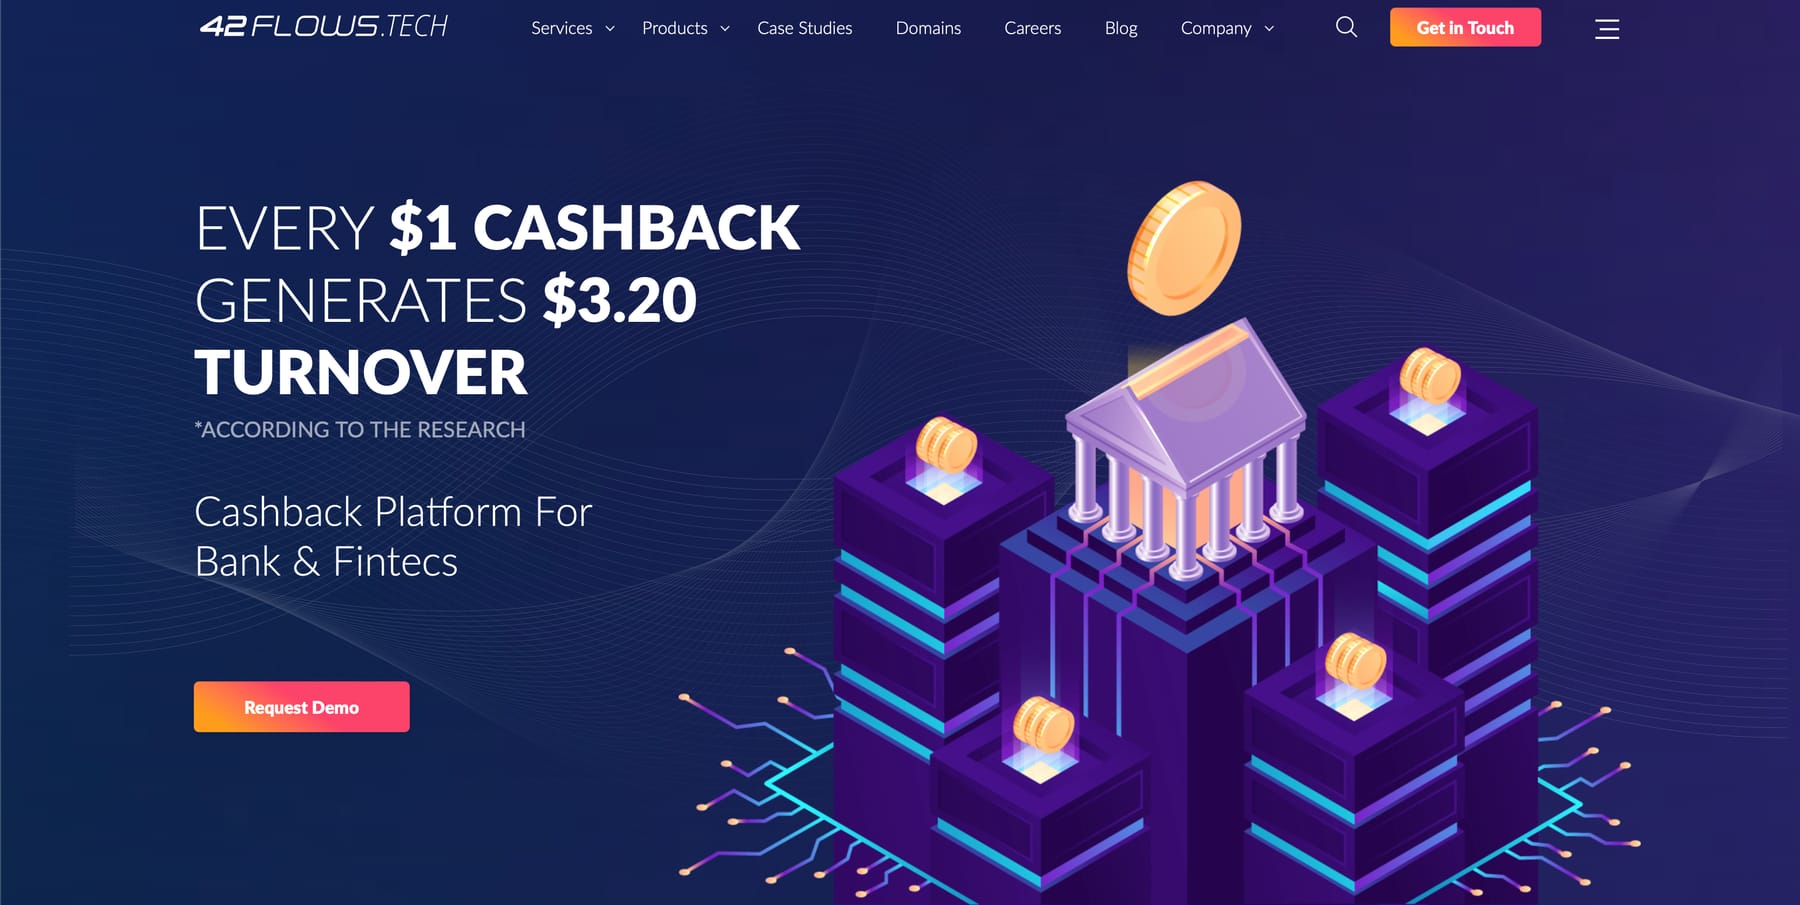
01First screenNeon towers and coins — associations with crypto, far from banking infrastructure -
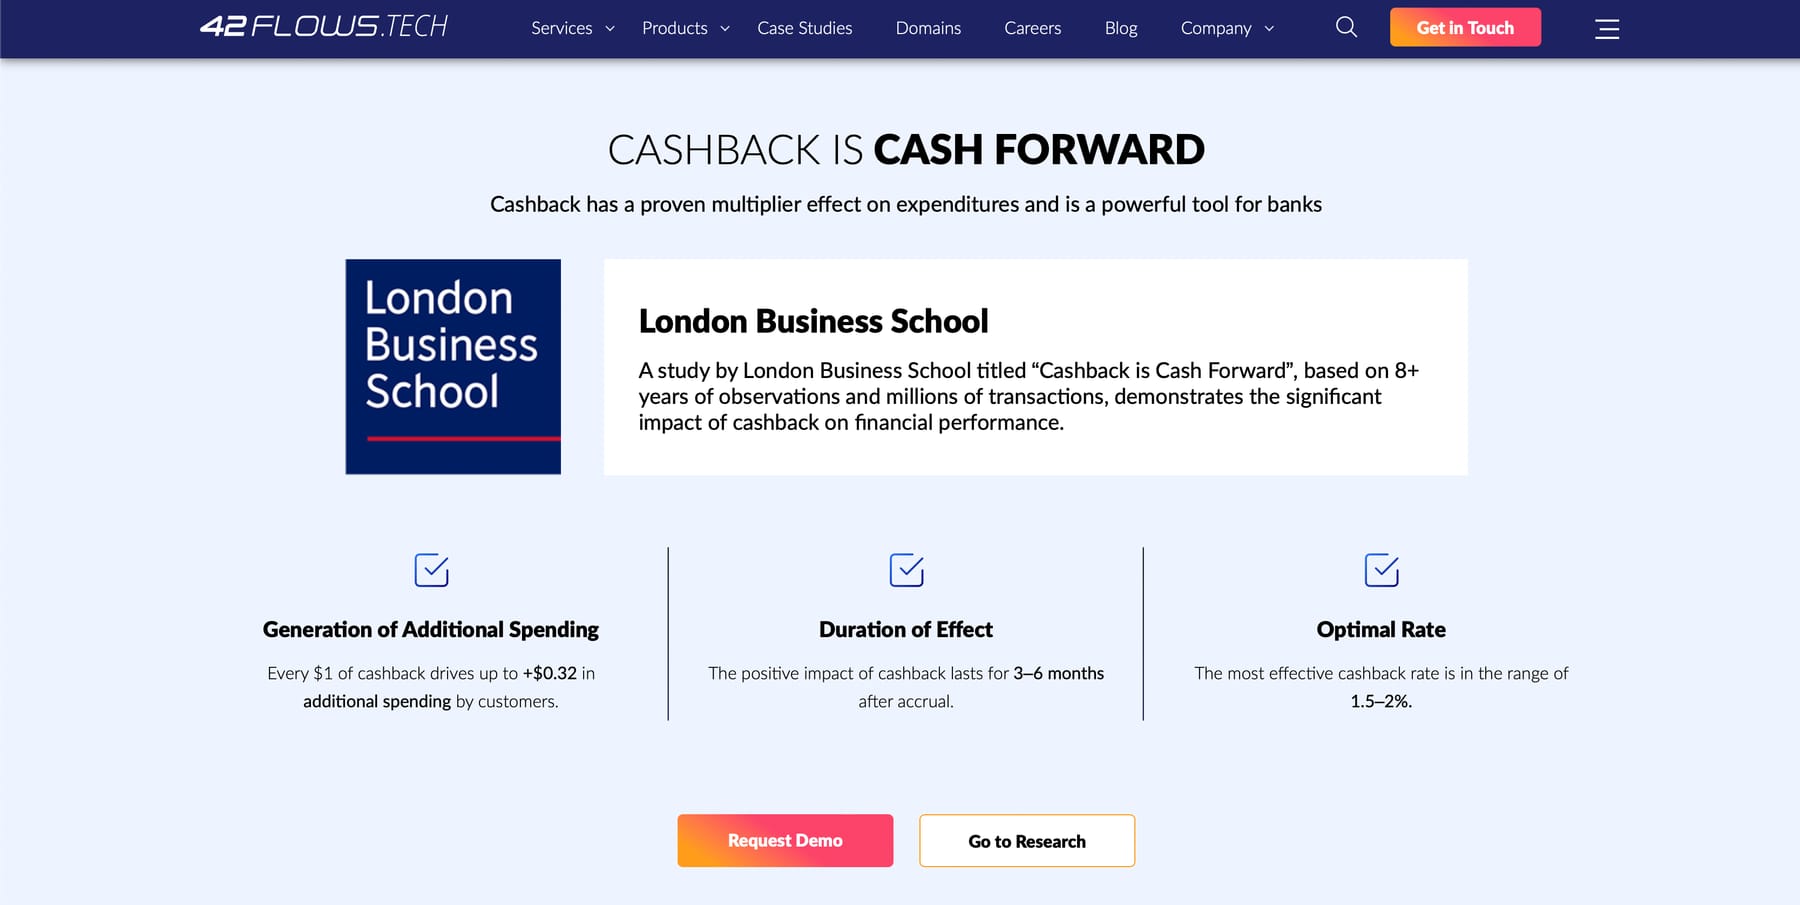
02ArgumentA figure from someone else’s study where the answer to “what will this do for my bank” should be -
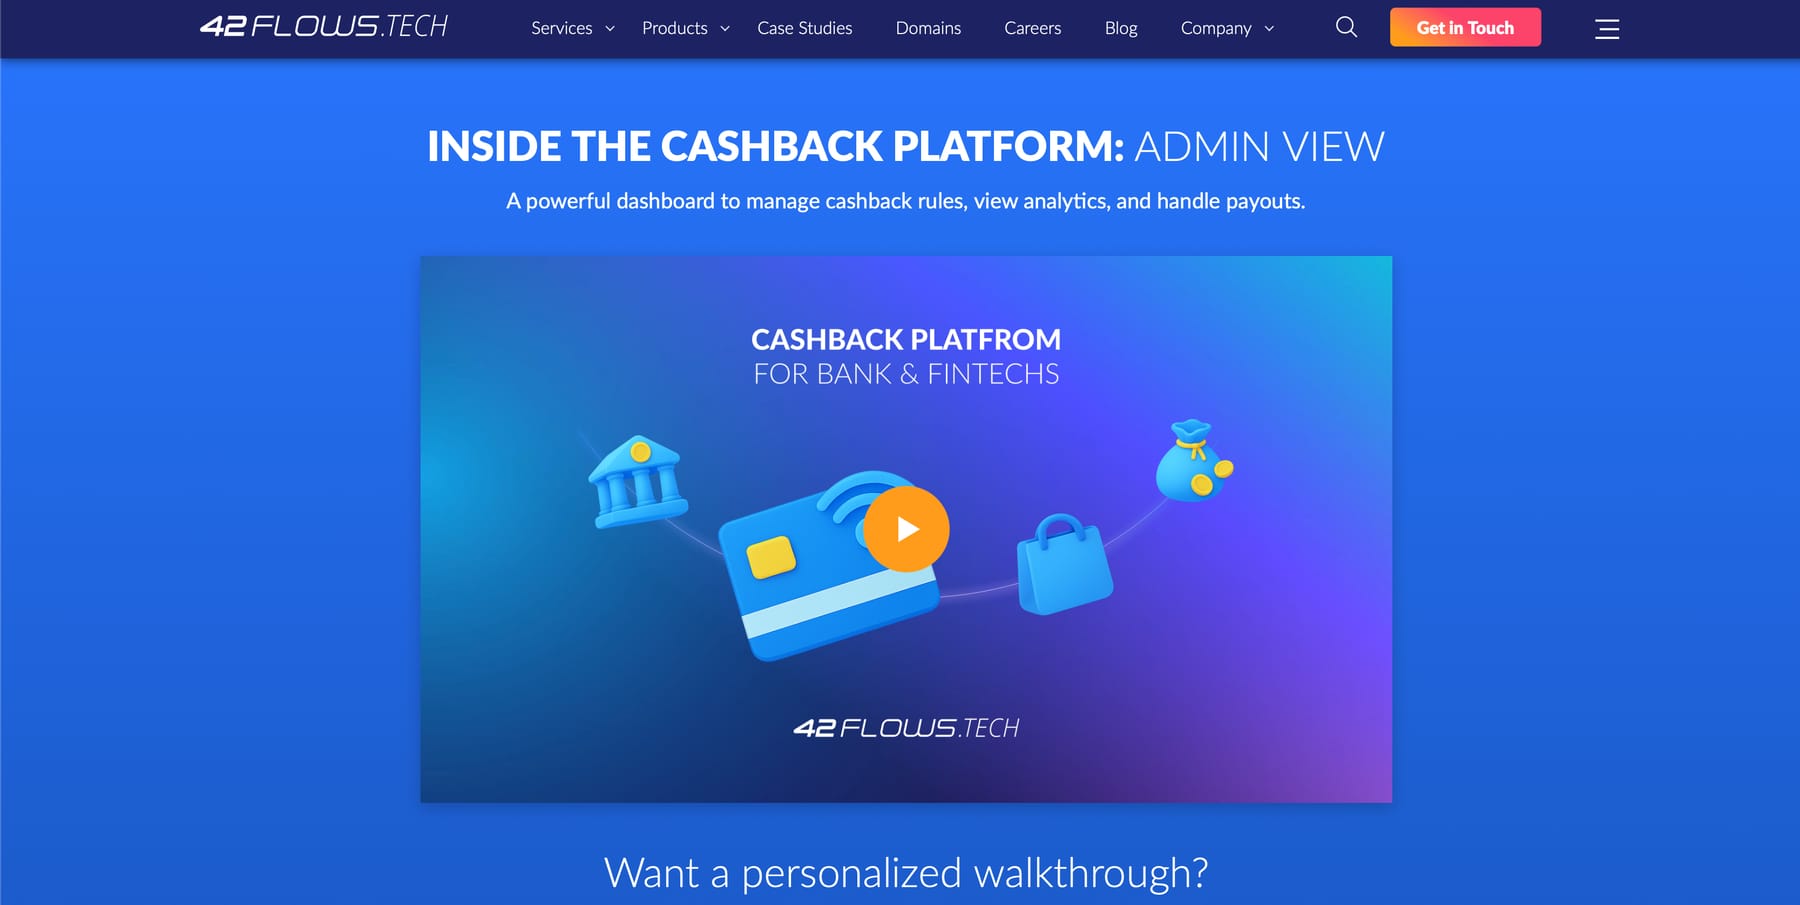
03ProductThe admin panel as decoration — nothing shows that the system exists and is easy to manage
Hypotheses
The team’s hypotheses about a rewards platform — and what the interviews confirmed
Pick a hypothesis and test it in conversations with people.
H01 · Confirmed
Banks buy a change in customer behavior, whatever the cashback rate
“1–2% for everyone” cashback rewards purchases customers would make anyway. So the product is a behavioral CRM: it turns dormant customers into active ones and transactors into credit-limit users.
“In fact, we’re building a CRM — a tool for changing customer behavior”
— the 42Flows team
H02 · Confirmed
A bank needs to see the money before the contract
The main argument is the financial model. A personal four-year P&L became both the first-screen promise and the page’s final action.
“Without a financial model, sales don’t move forward”
— the 42Flows sales team
H03 · Confirmed
42Flows is already a product company
Clients see 42Flows as a ready-made solution and have no interest in outsourcing as a category. So the page sells a platform with ROI.
“42Flows is perceived as a ready-made product solution”
— from client conversations
H04 · Refined
The main barrier is IT and a long launch
Code is the quick part. Most of the time goes into accounting and approvals, so the page shows four implementation phases with timelines and makes no “15-minute launch” promise.
“Accounting takes the most time”
— the 42Flows team
Positioning
From a cashback module to a rewards platform
- What we sell a cashback accrual modulea managed driver of the bank’s growth and profit
- Cashback is a cost and a promotiona trigger in a behavioral CRM
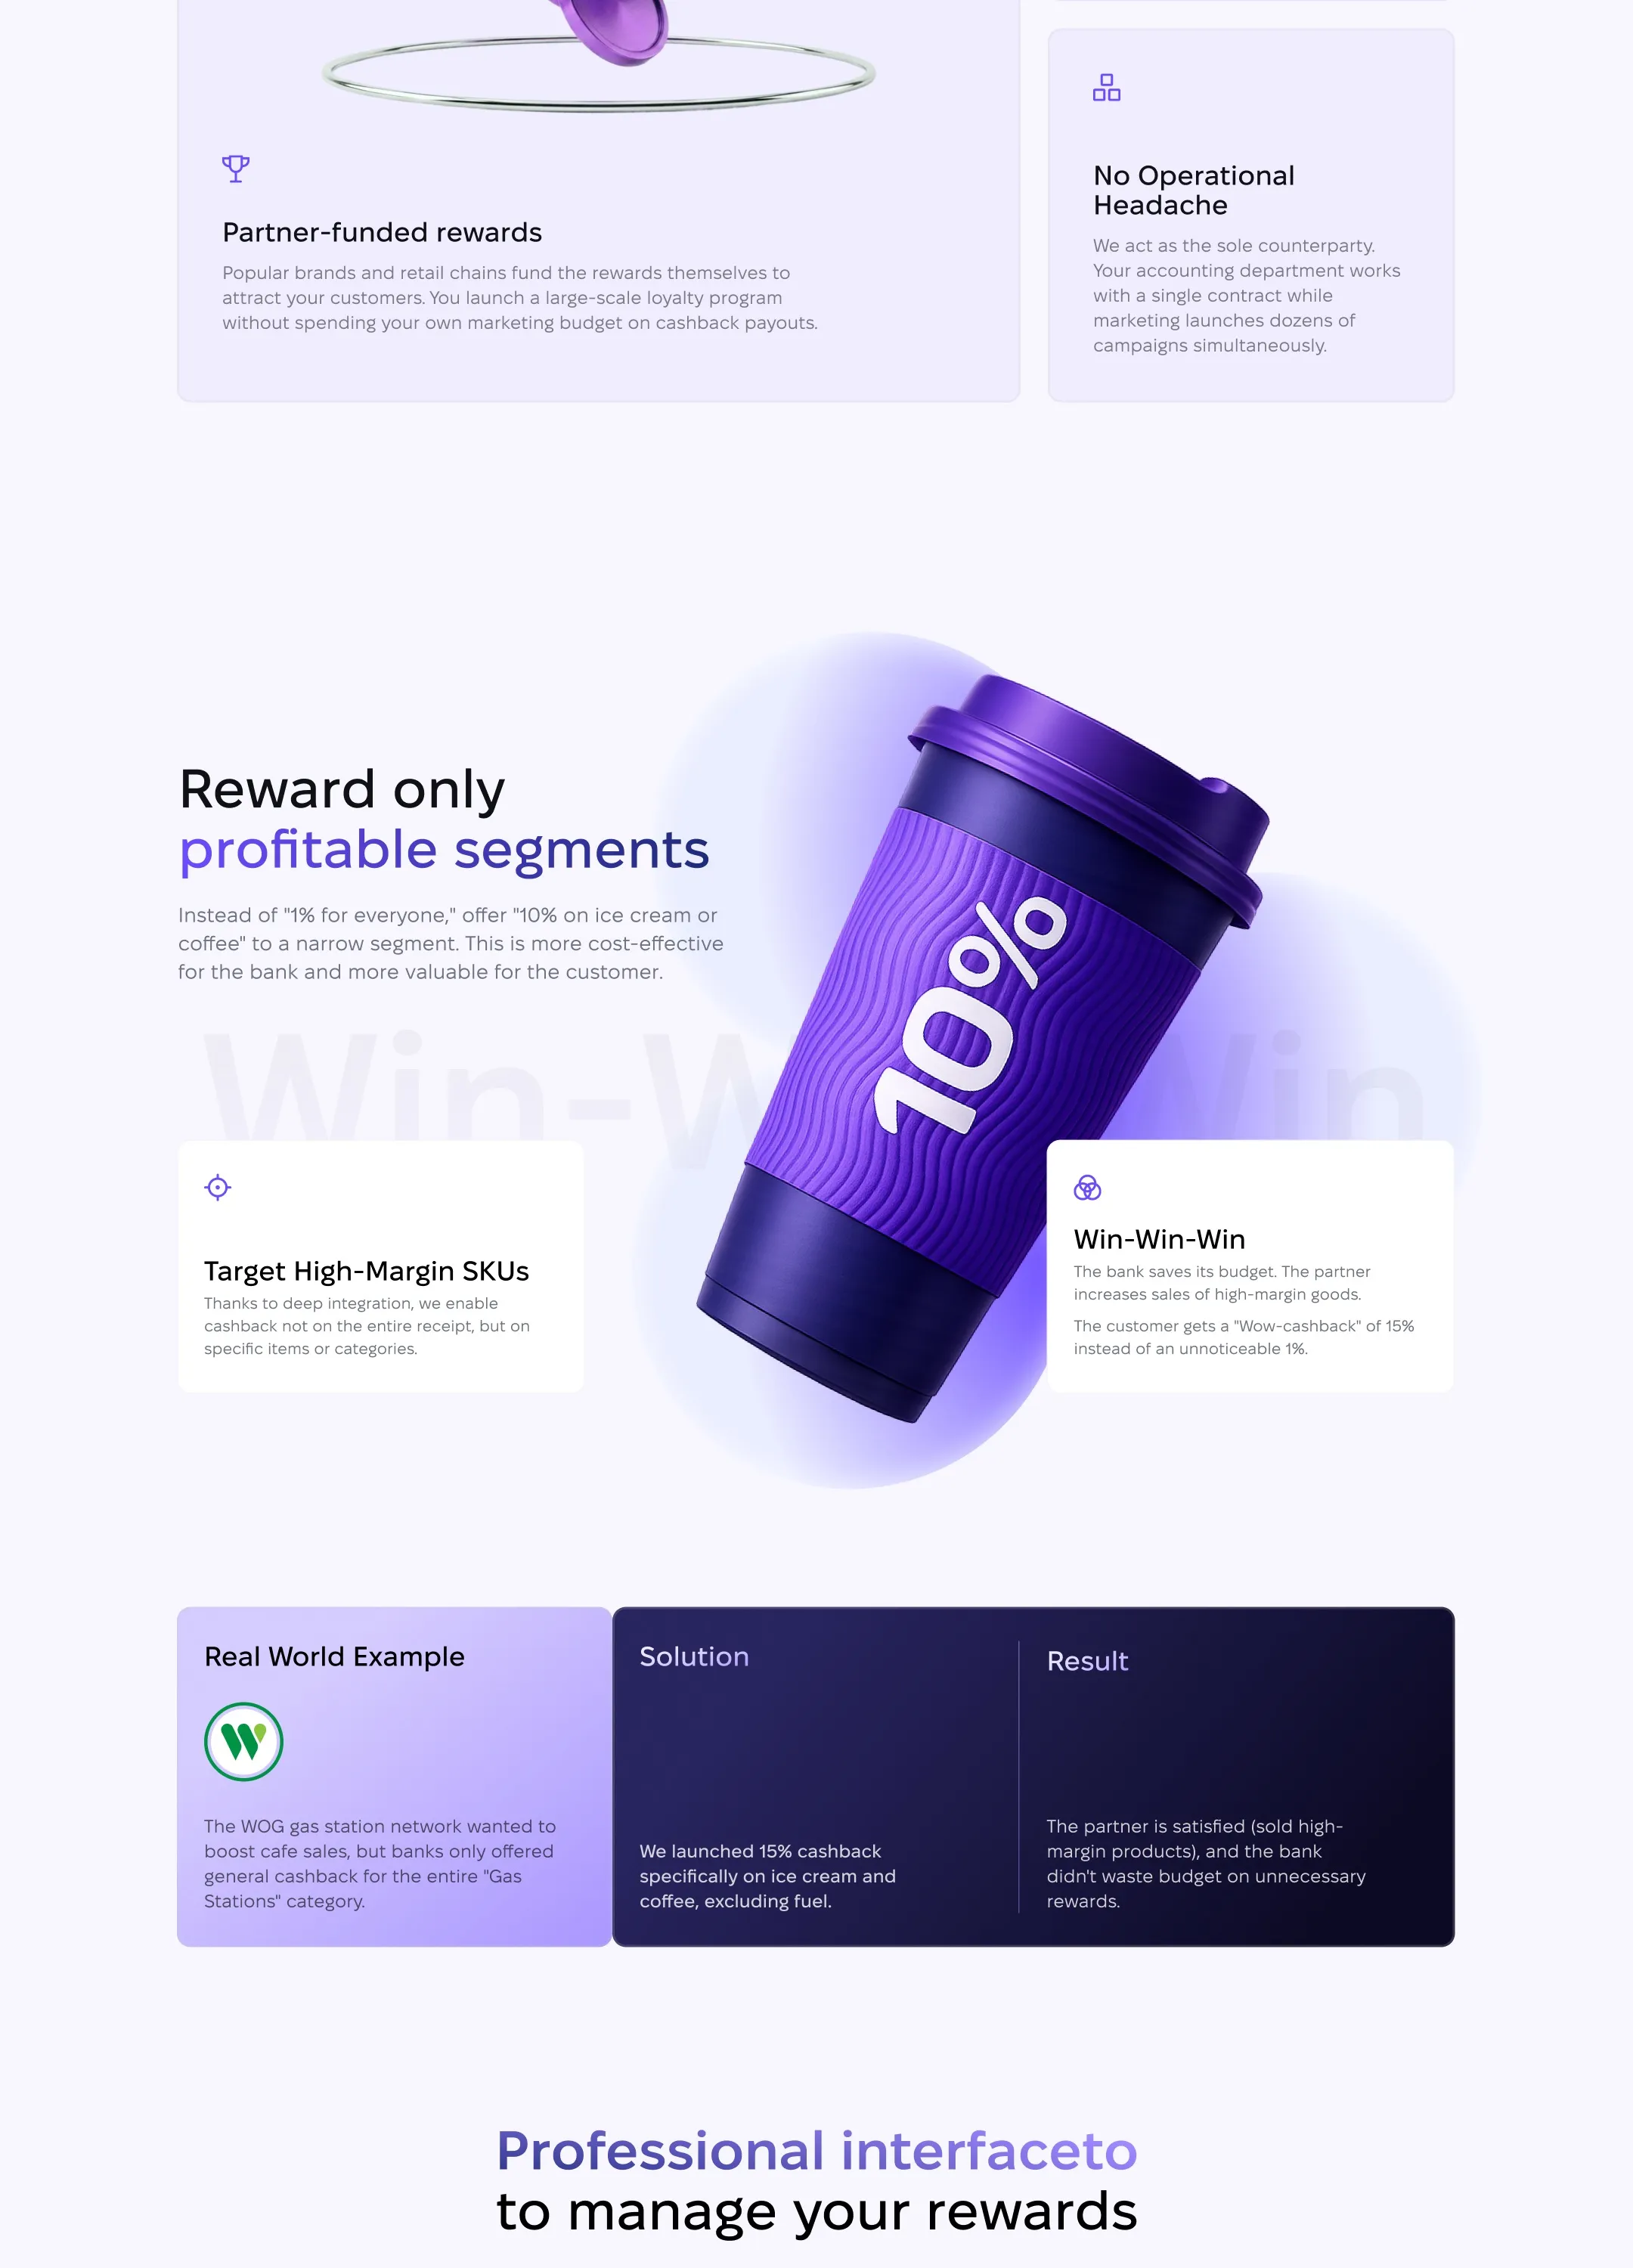
- Model “1–2% for everyone”rewards only for profitable segments
- Who pays the bank, from its marketing budgetretail partners
- Argument “$1 of cashback = $3.20 of turnover”your ROI and four-year P&L before the contract
- Feel decorative fintech, clip artcalm infrastructure backed by numbers
Key points
First, what to tell the bank. Then, the website
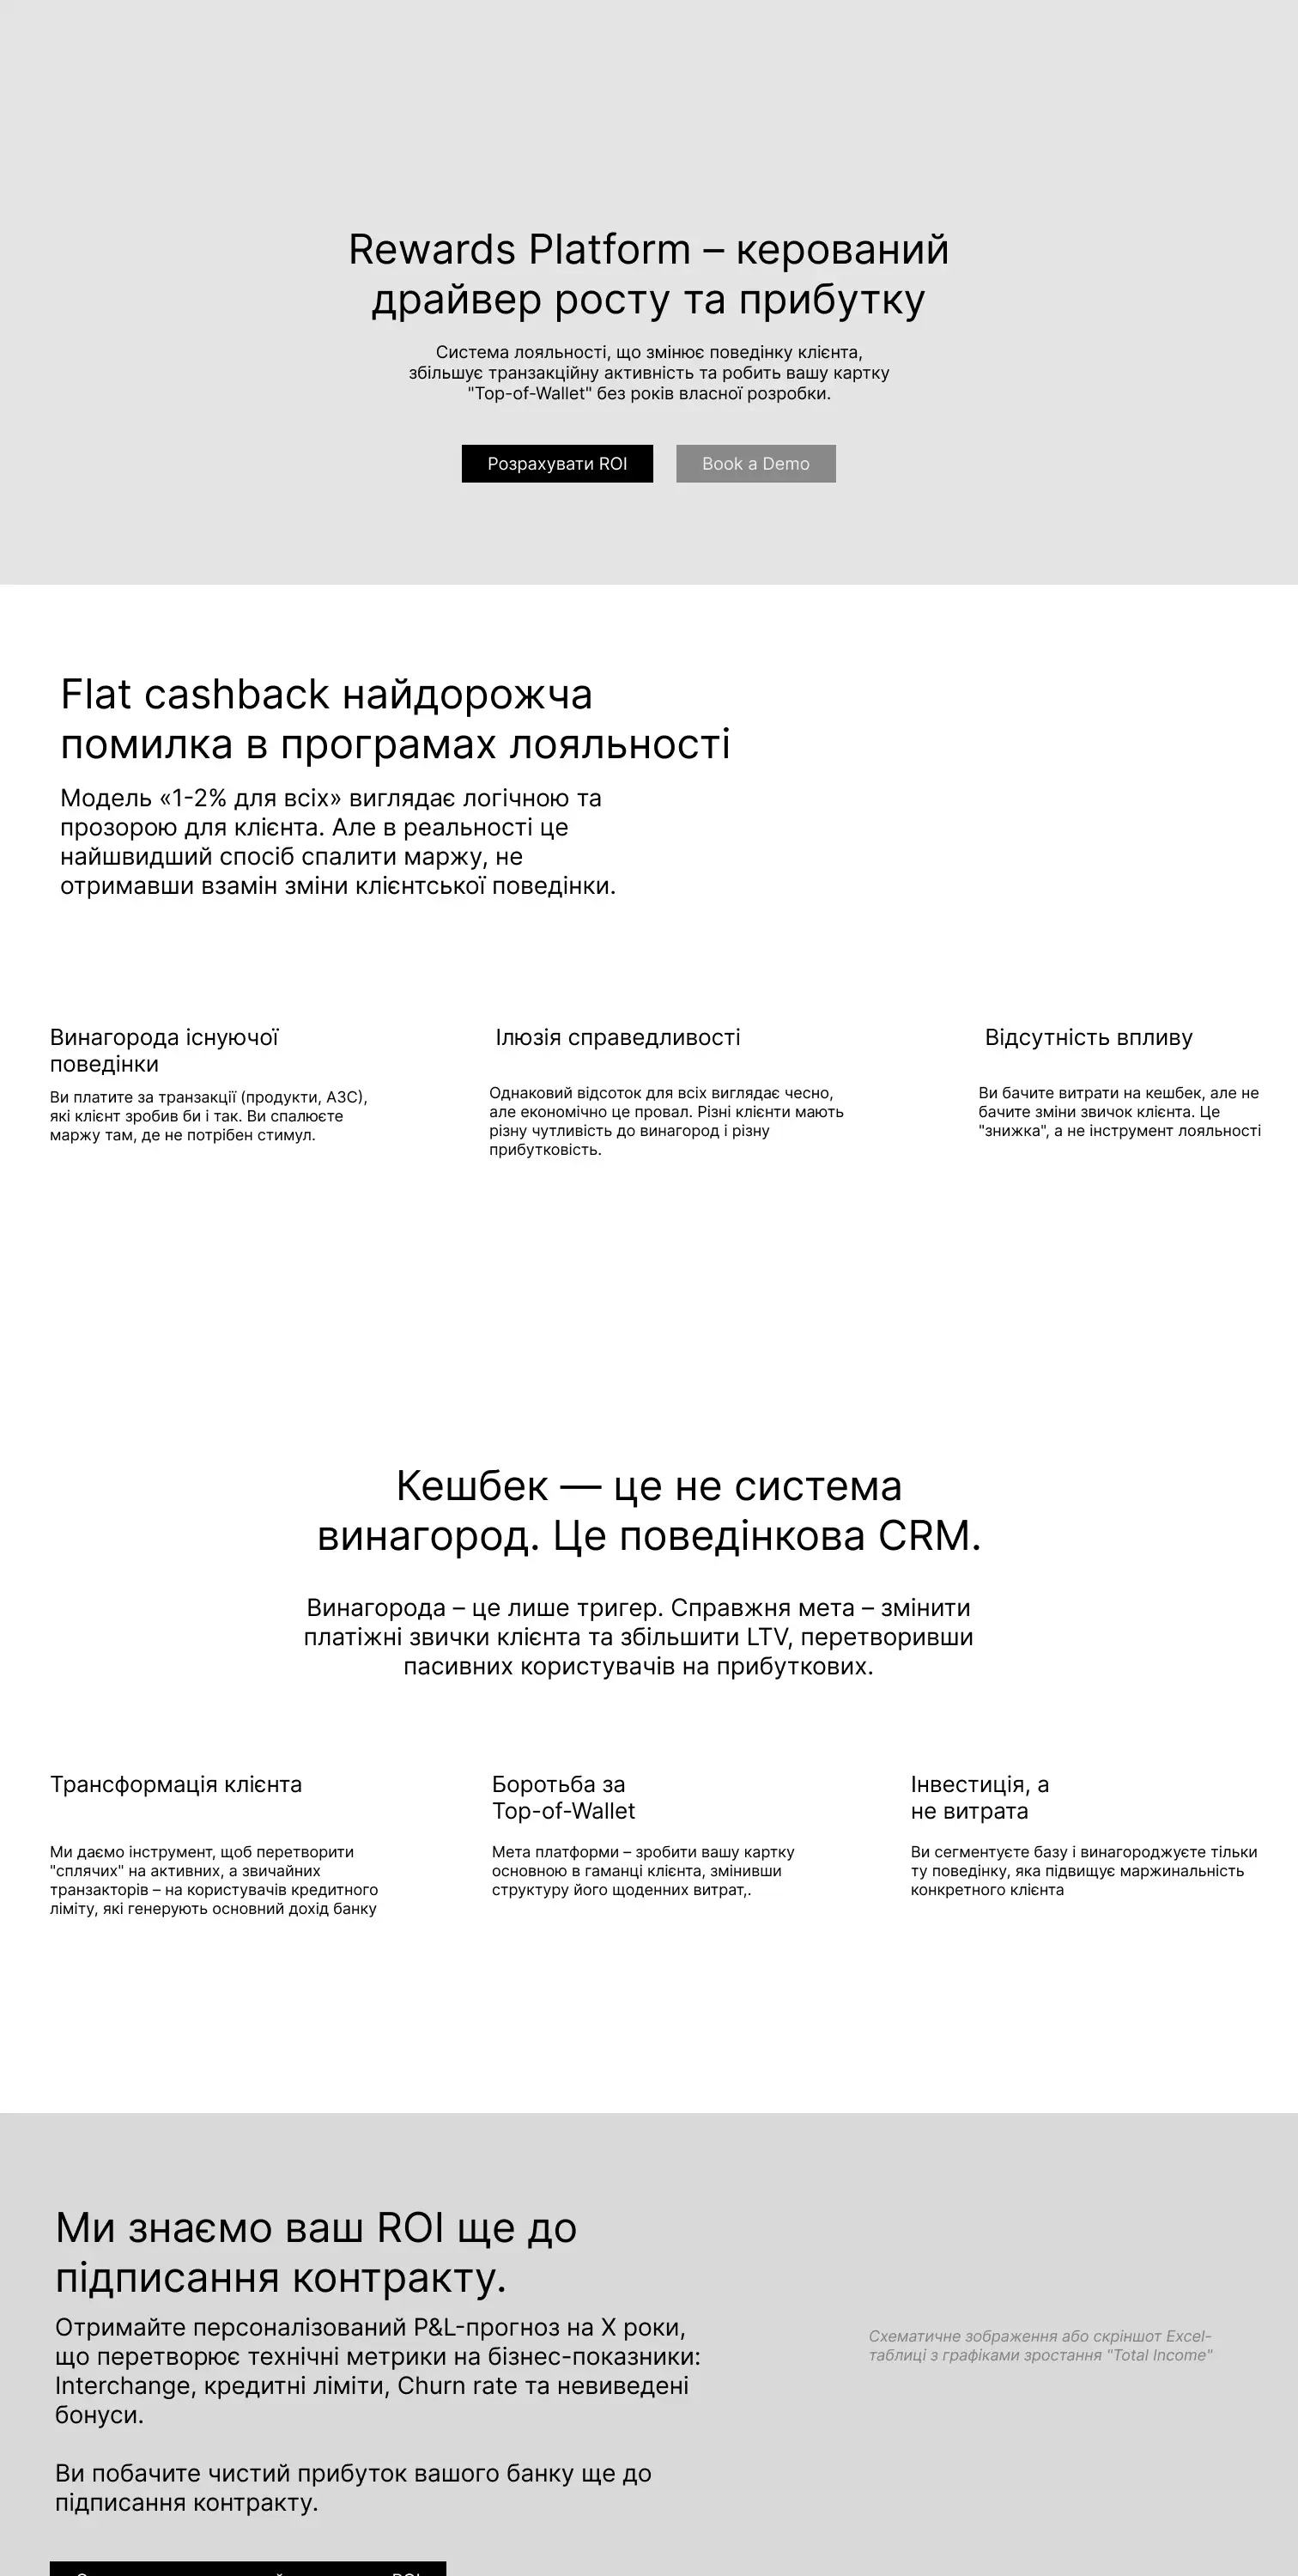
We started the website with words. Every key line on the page answers a specific bank pain and a 42Flows business task. We shaped the messages, built the structure from them, and only then did design give them form.
- 01Client pain
- 02Business task
- 03Meaning
- 04Website copy
- 05Design follows
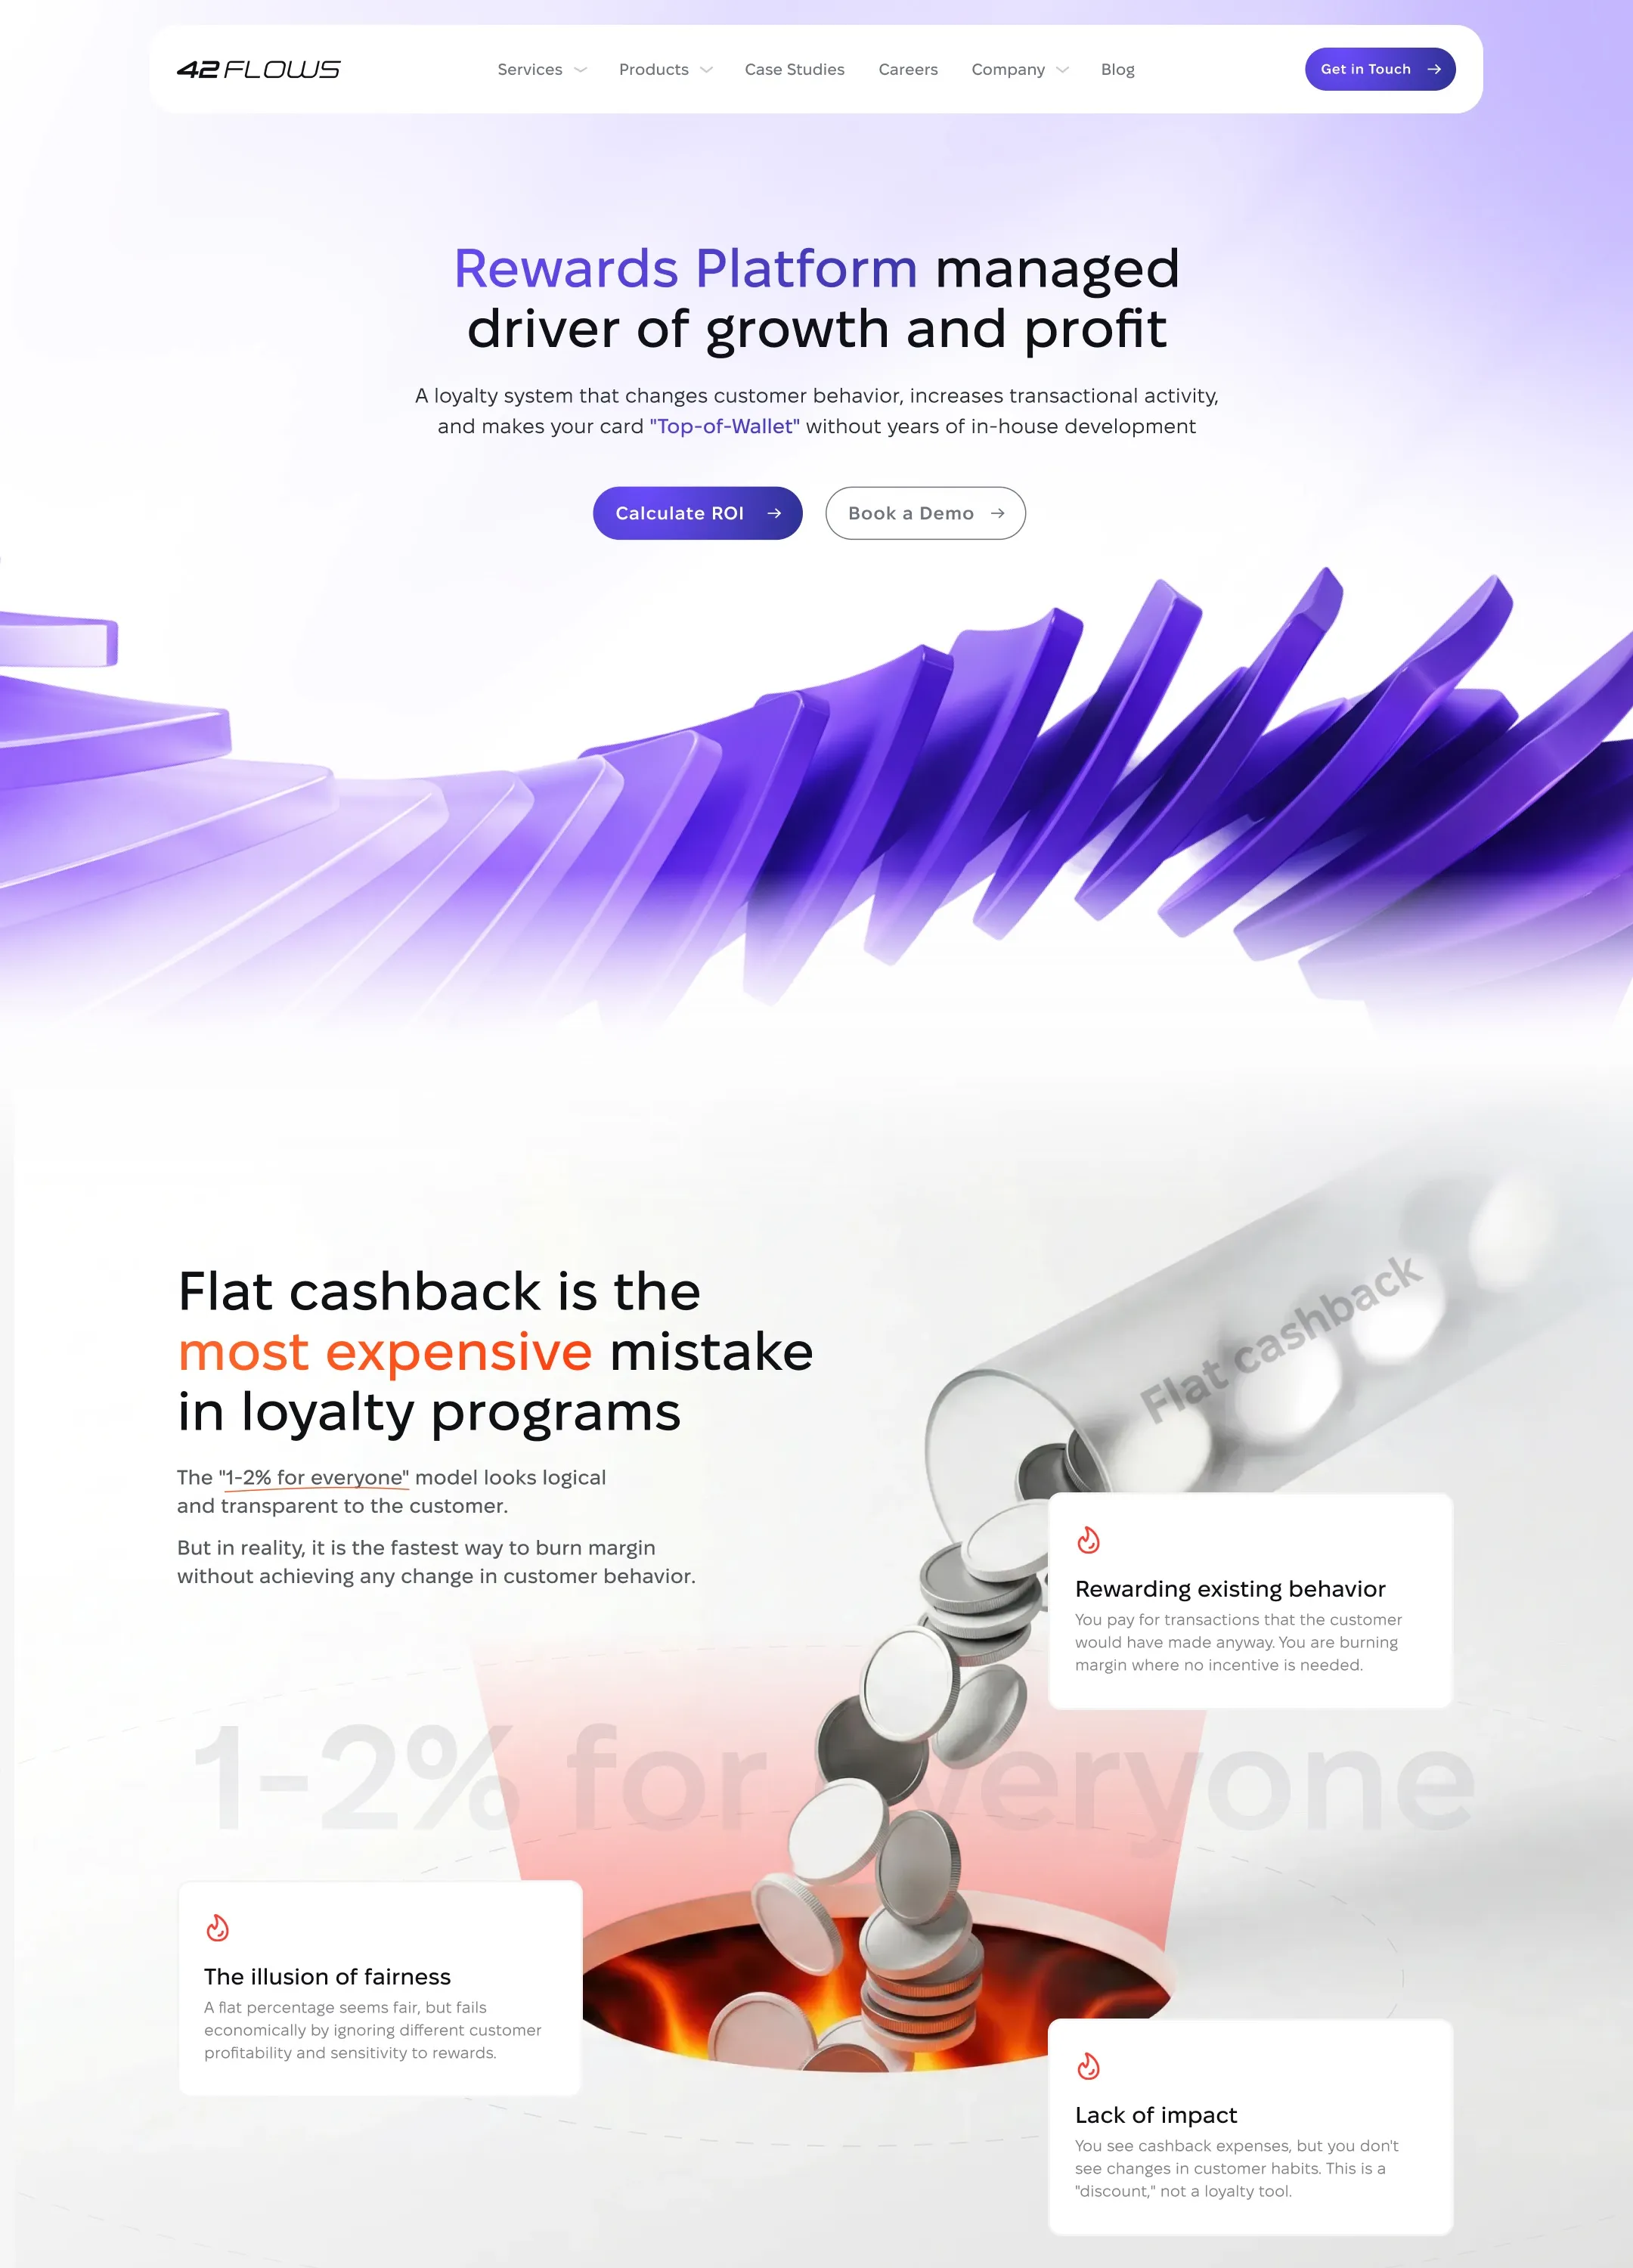
Client painBanks hand out “1–2% for everyone” and see no change in customer behavior — cashback looks like pure cost.
Business taskShow the bank that the problem lies in the model itself, whatever the rate — and that 42Flows sells something else entirely.
MeaningCashback is a trigger for behavior change. The product is a behavioral CRM.
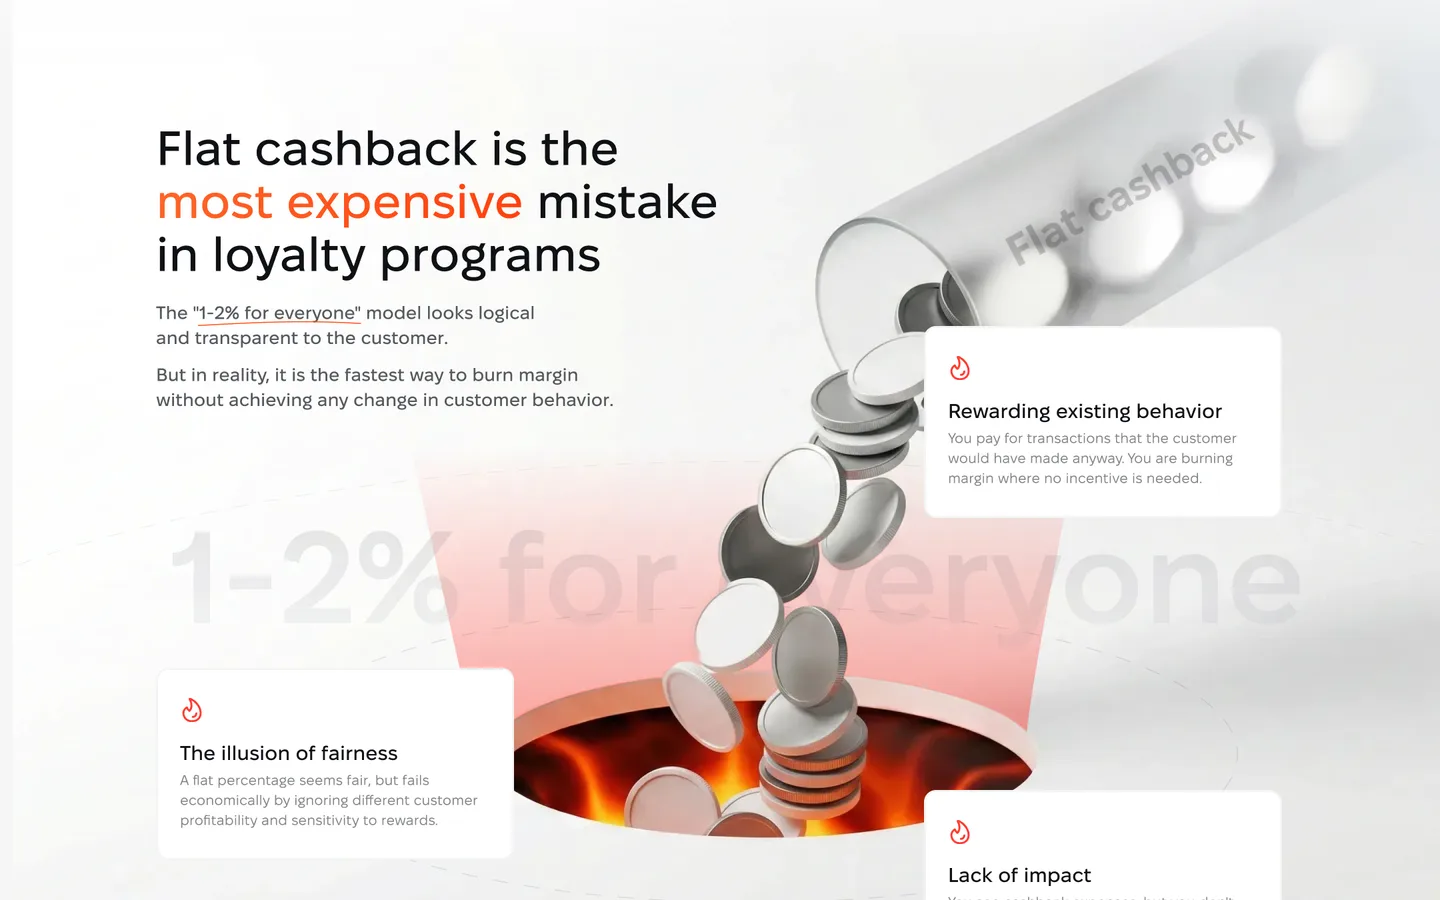
Flat cashback is the most expensive mistake in loyalty programs
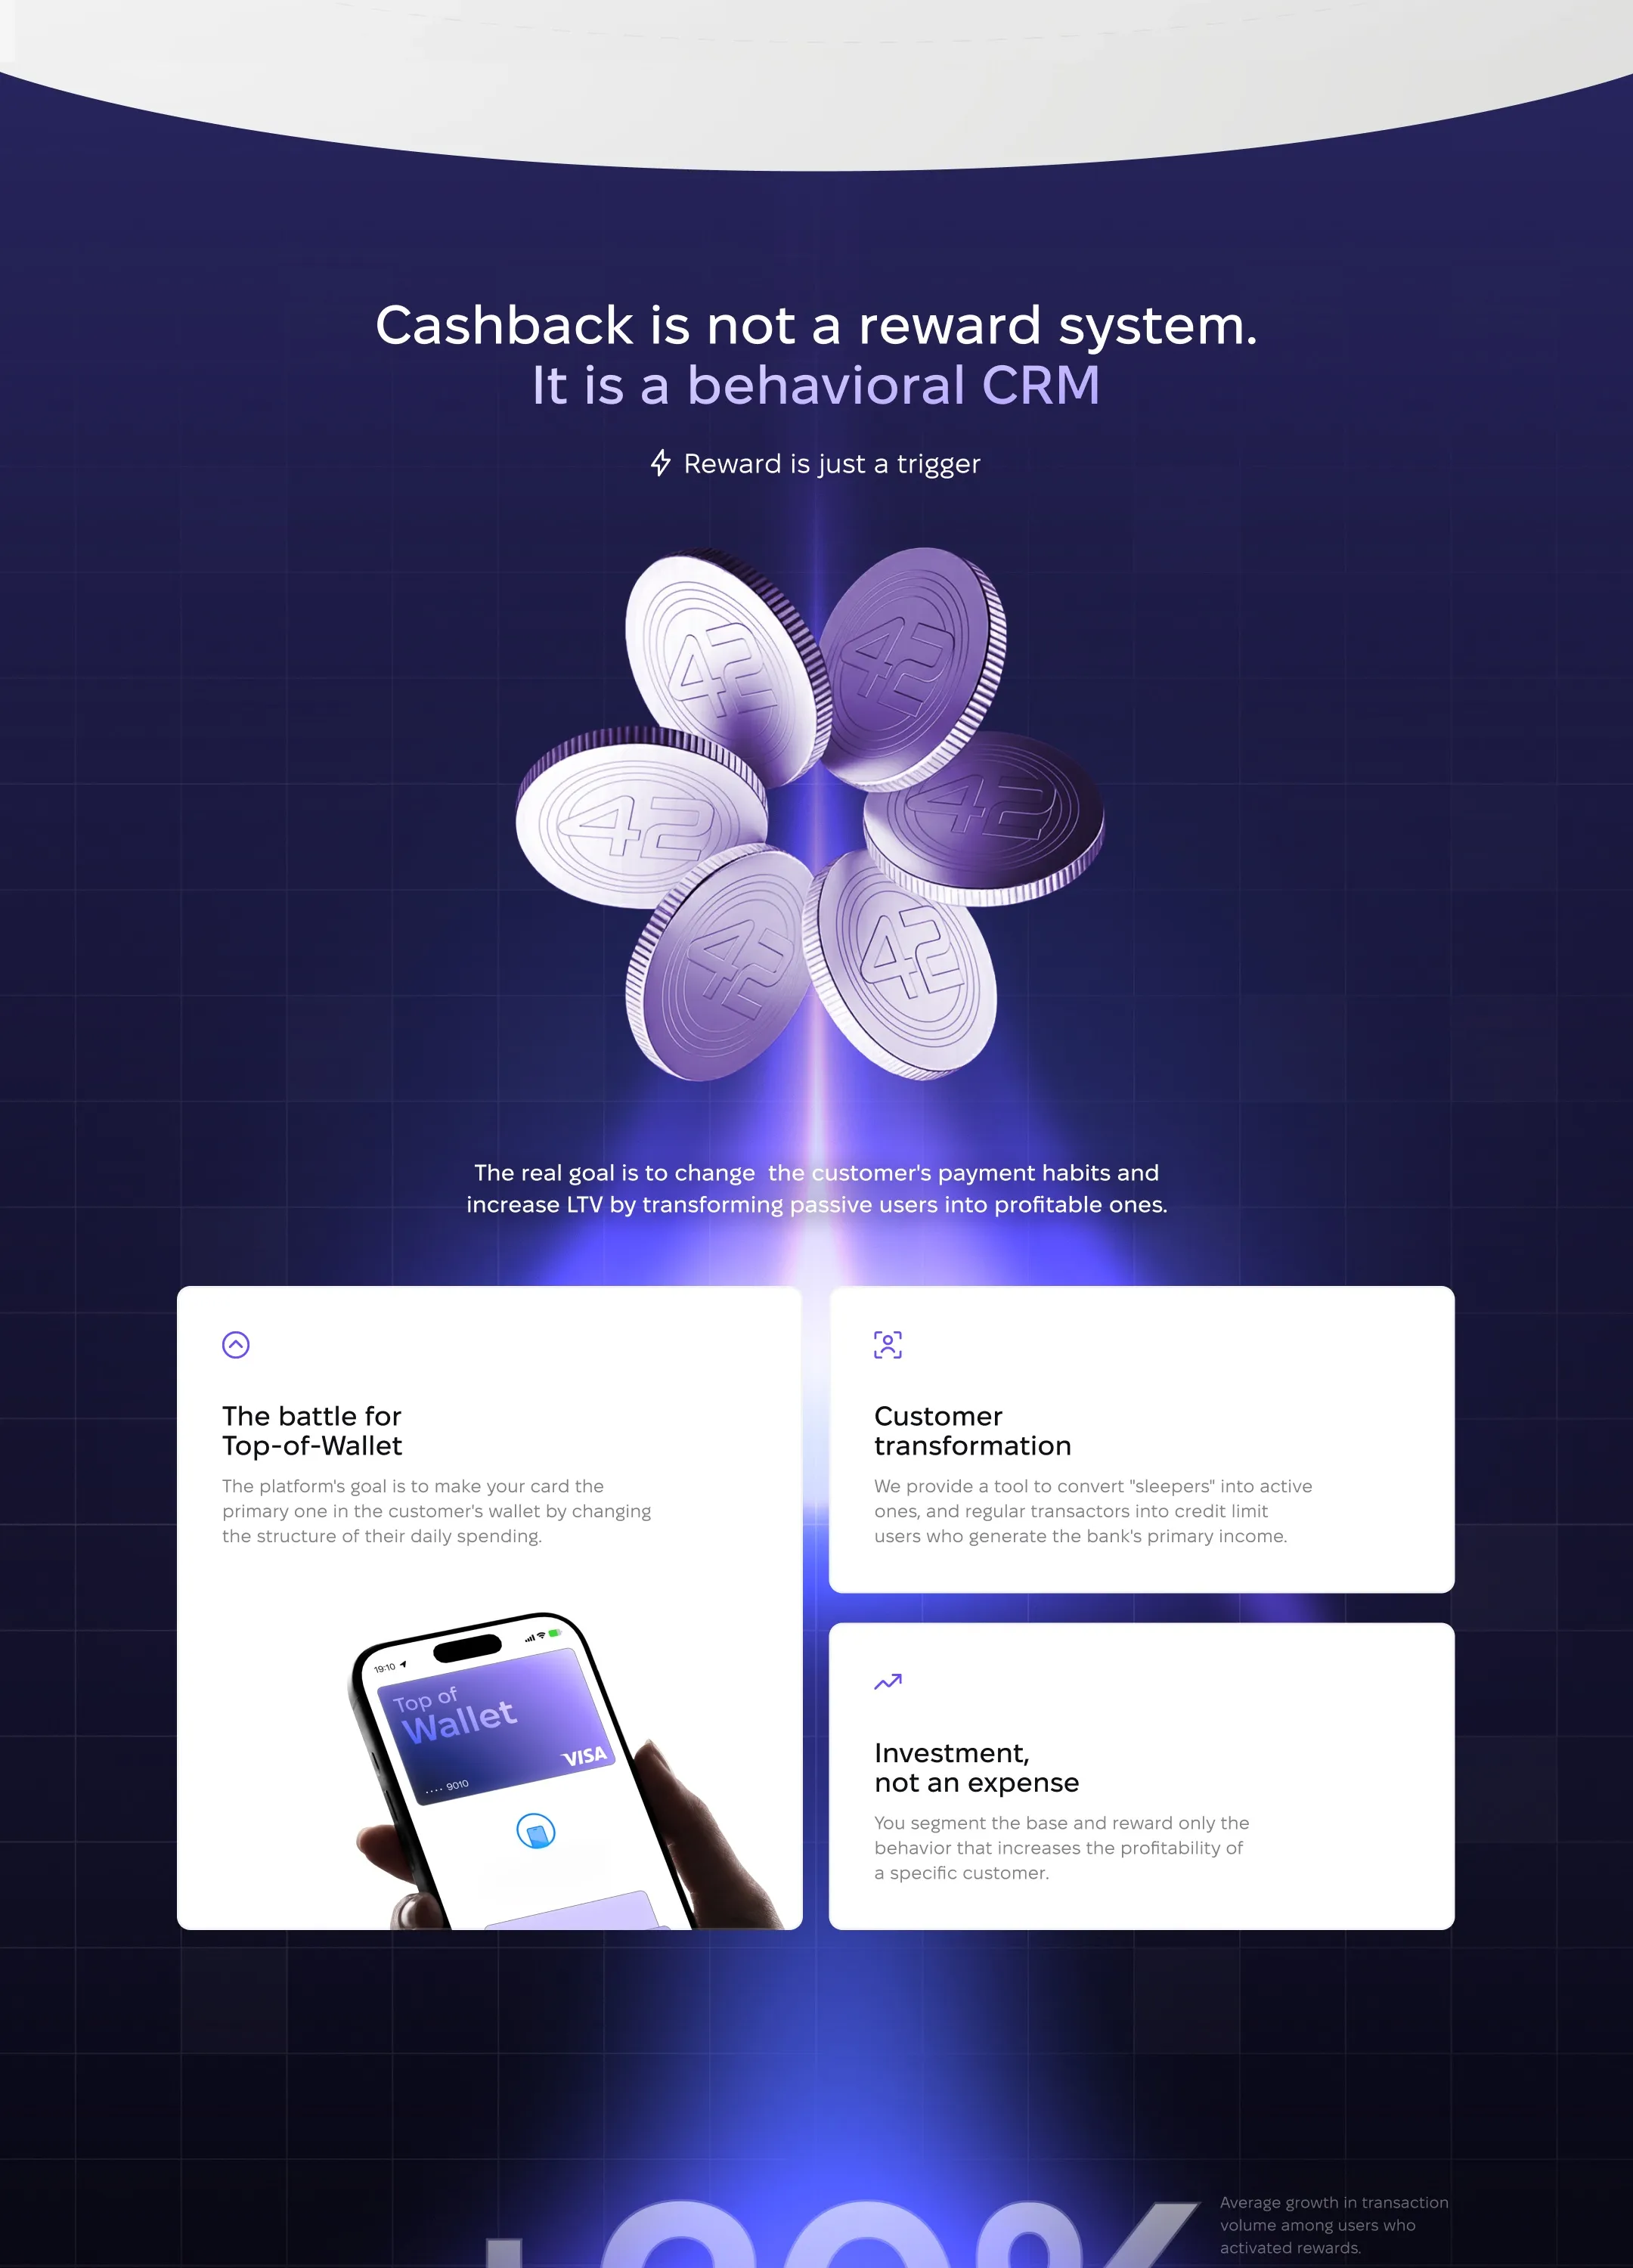
Cashback is not a reward system. It is a behavioral CRM
Client painThe bank’s finance team is pessimistic, and without numbers the sale stalls before the first meeting.
Business taskMove the conversation from features to money — and do it before the bank starts to doubt.
MeaningROI is the product’s headline promise from the very first screen.
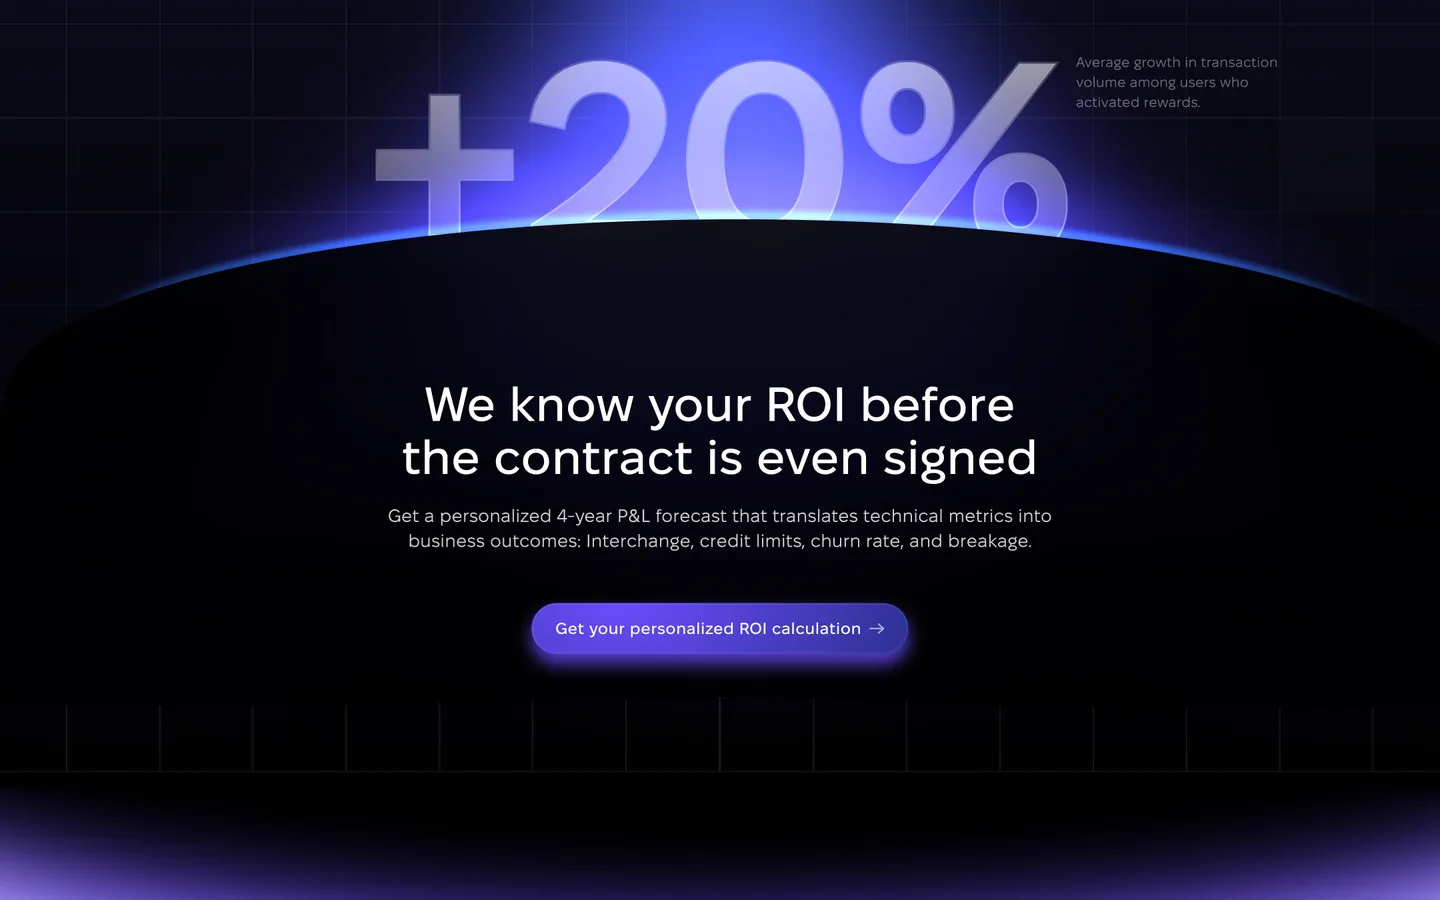
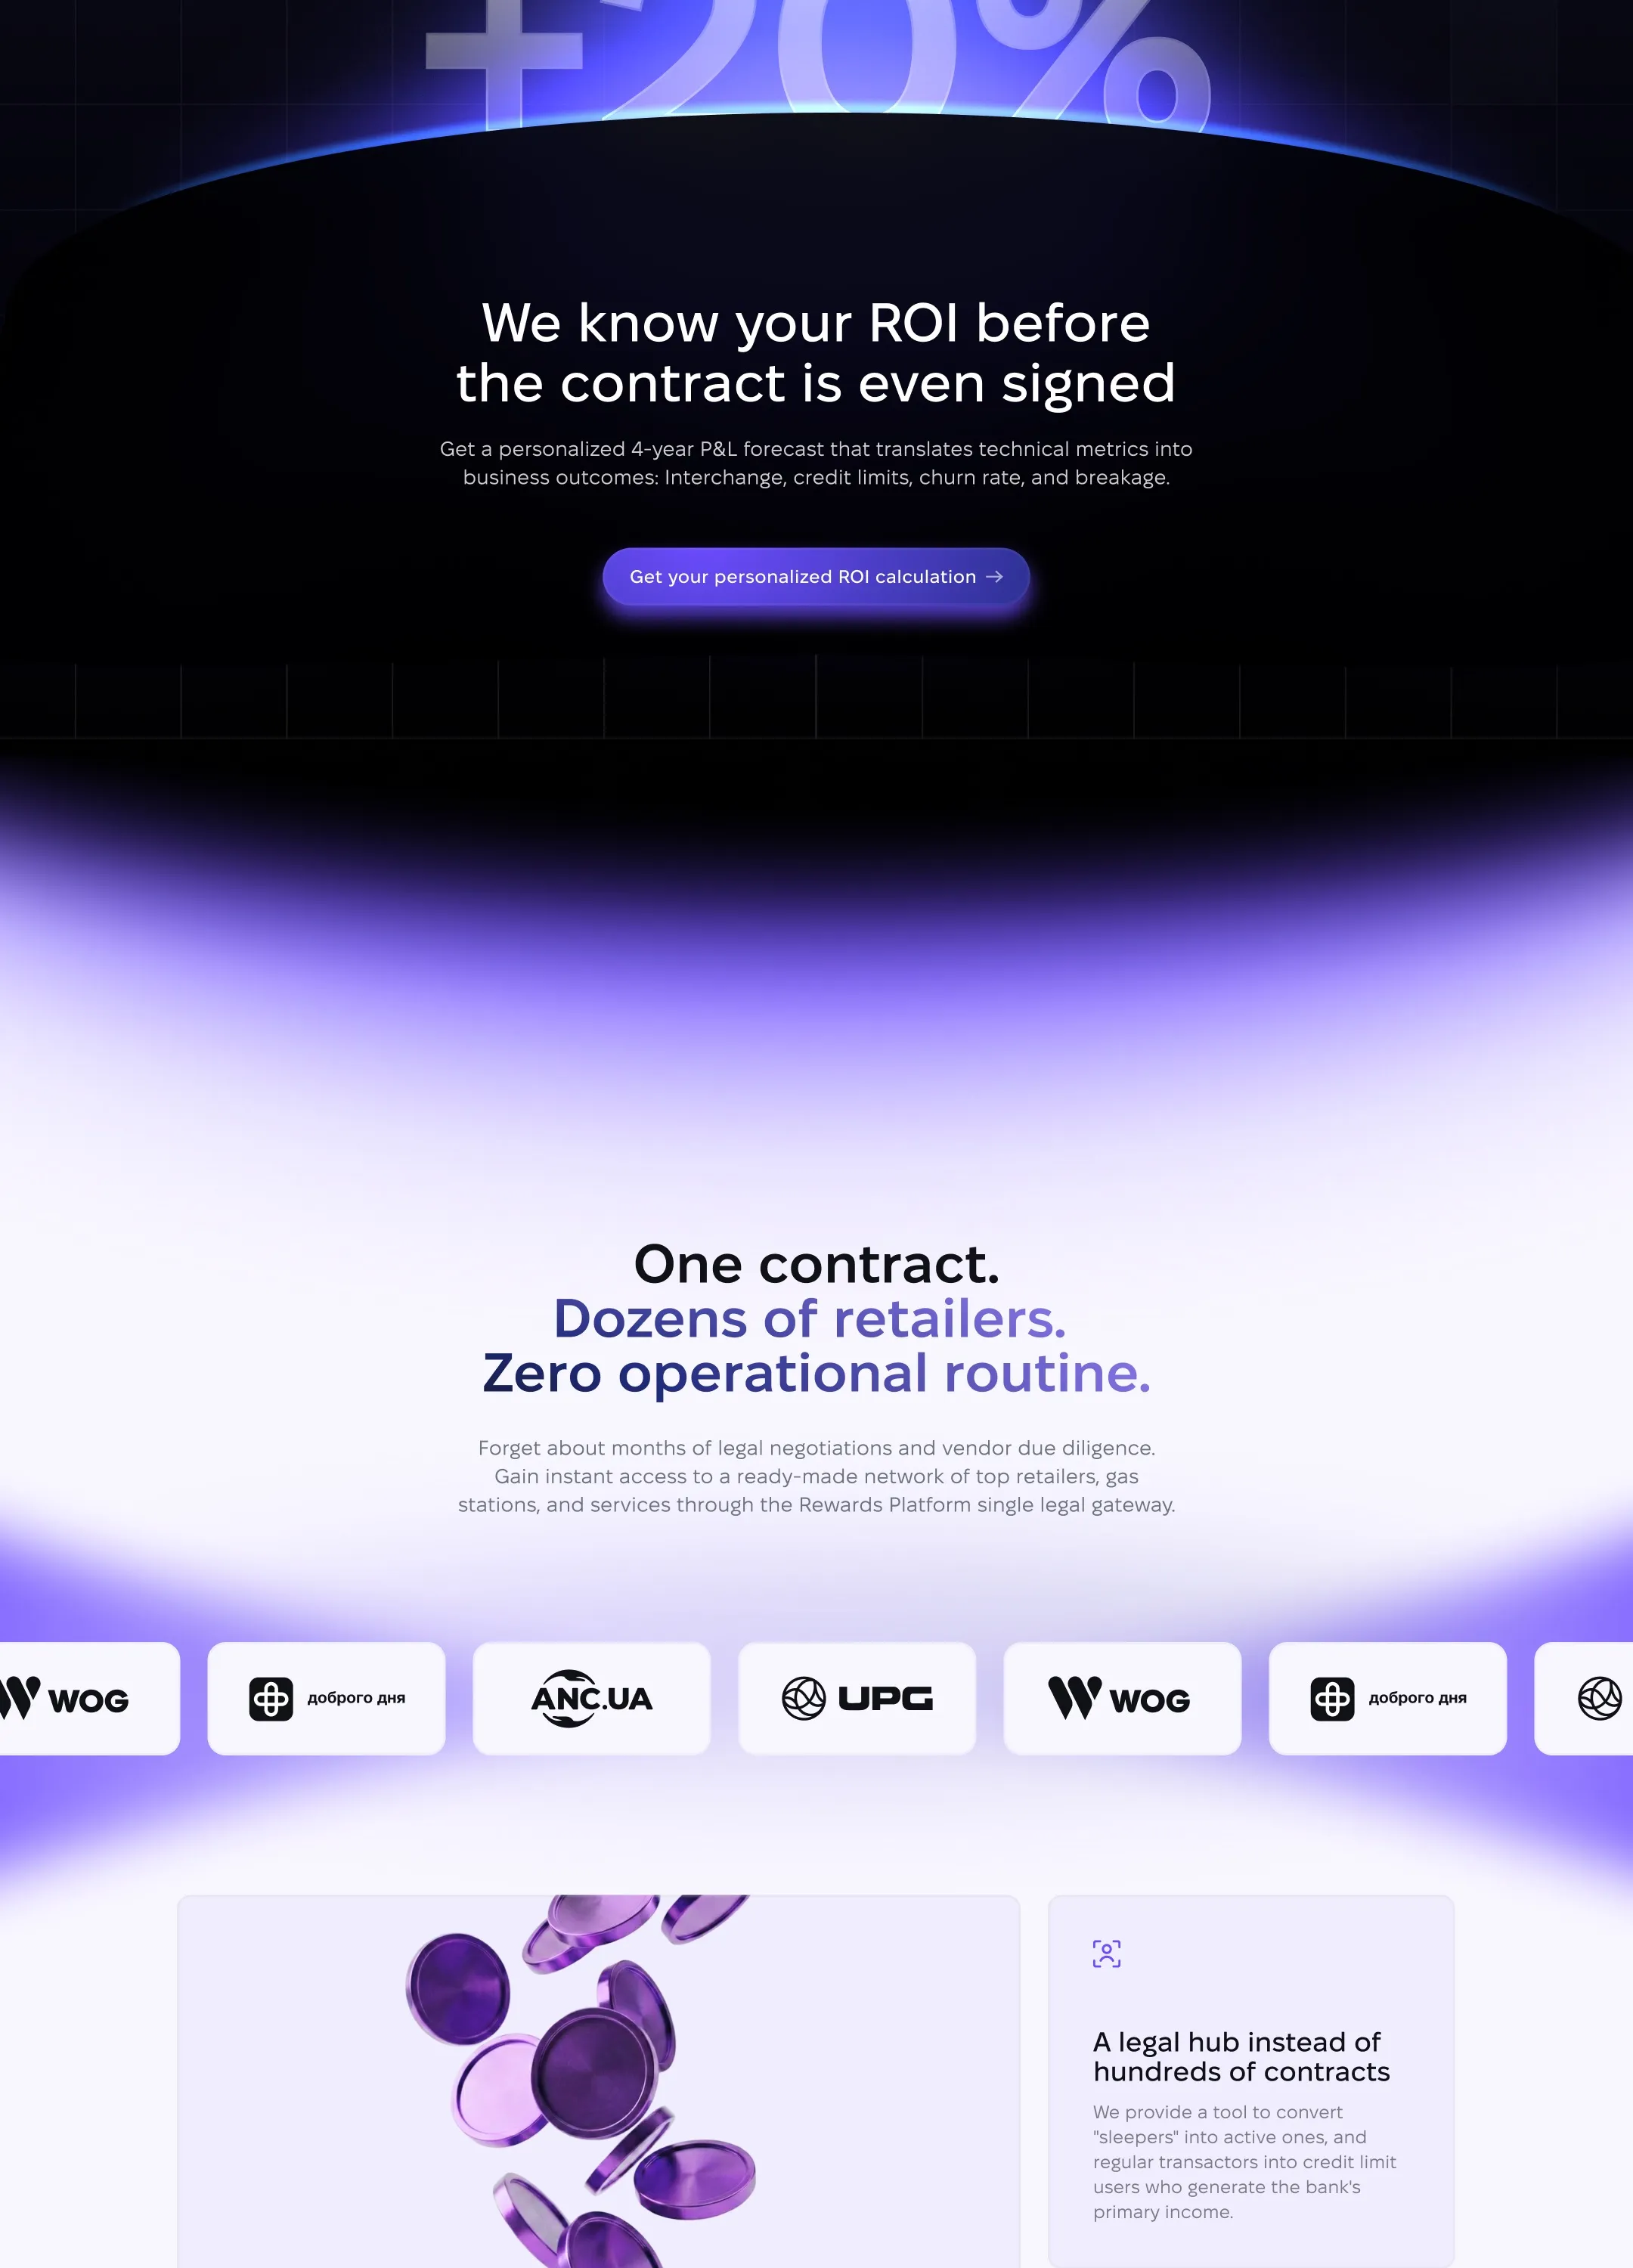
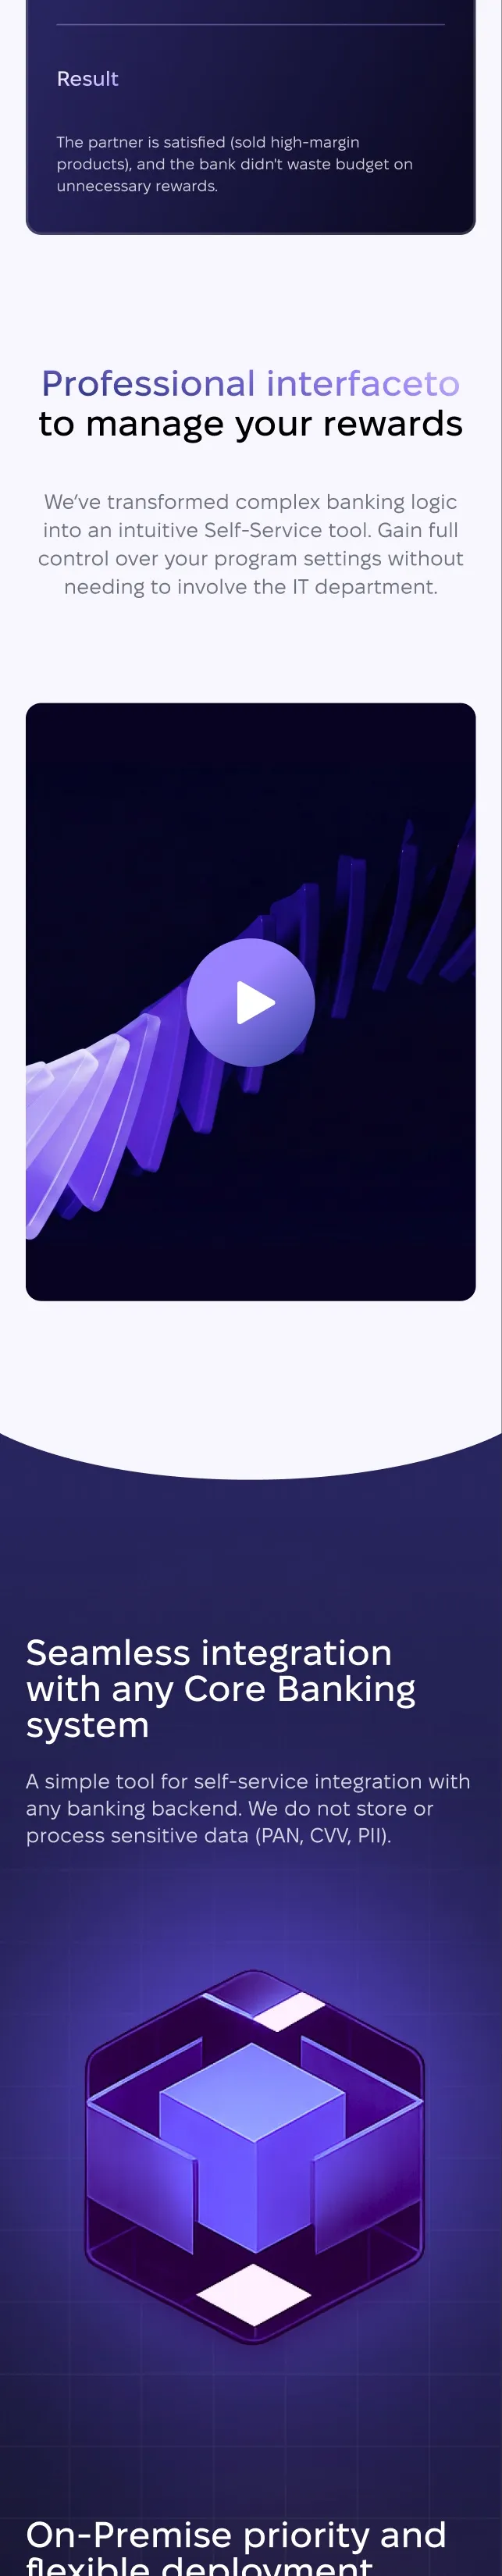
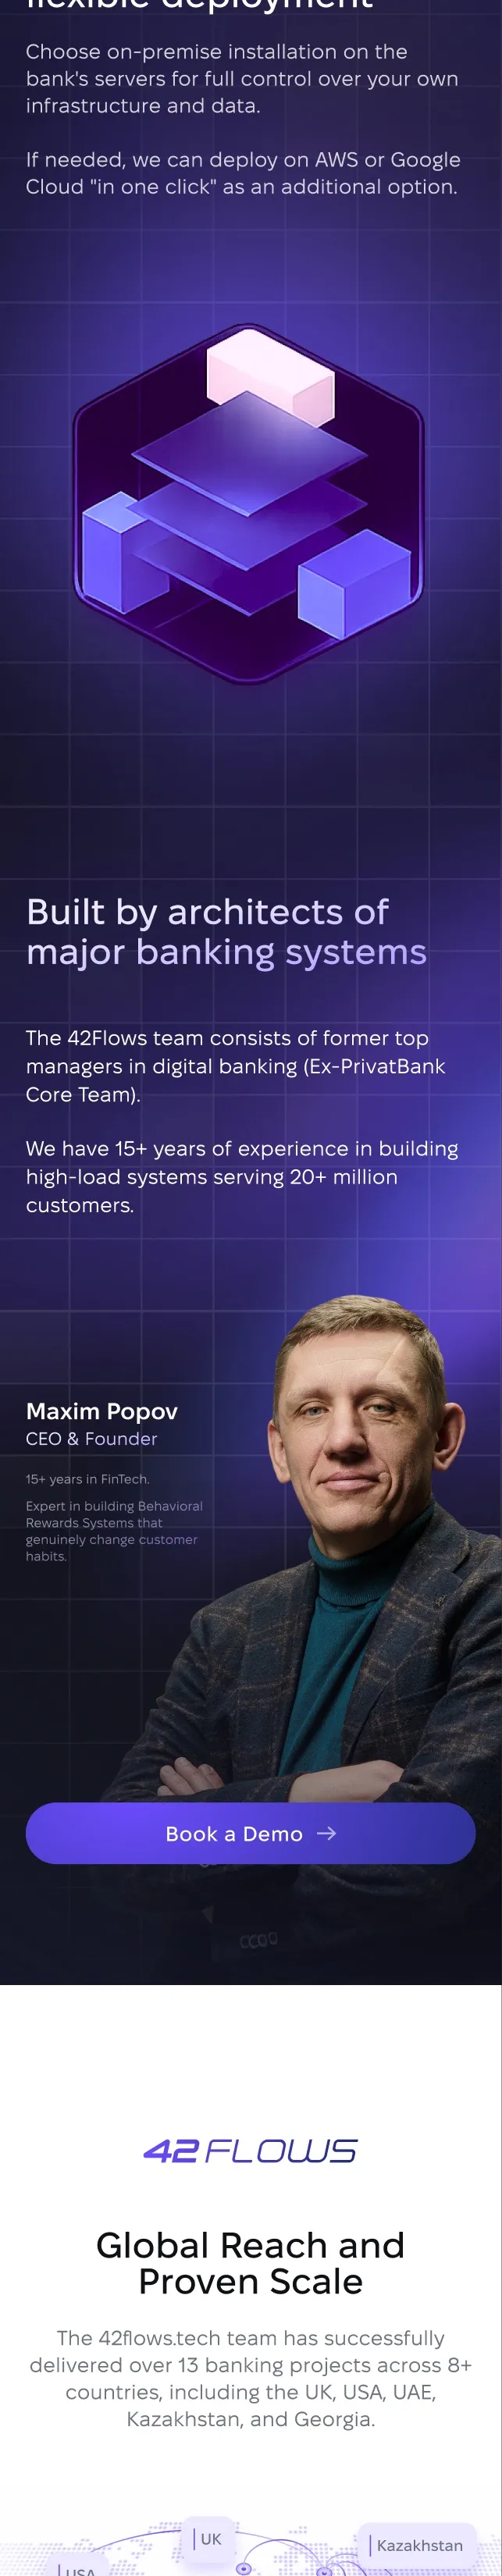
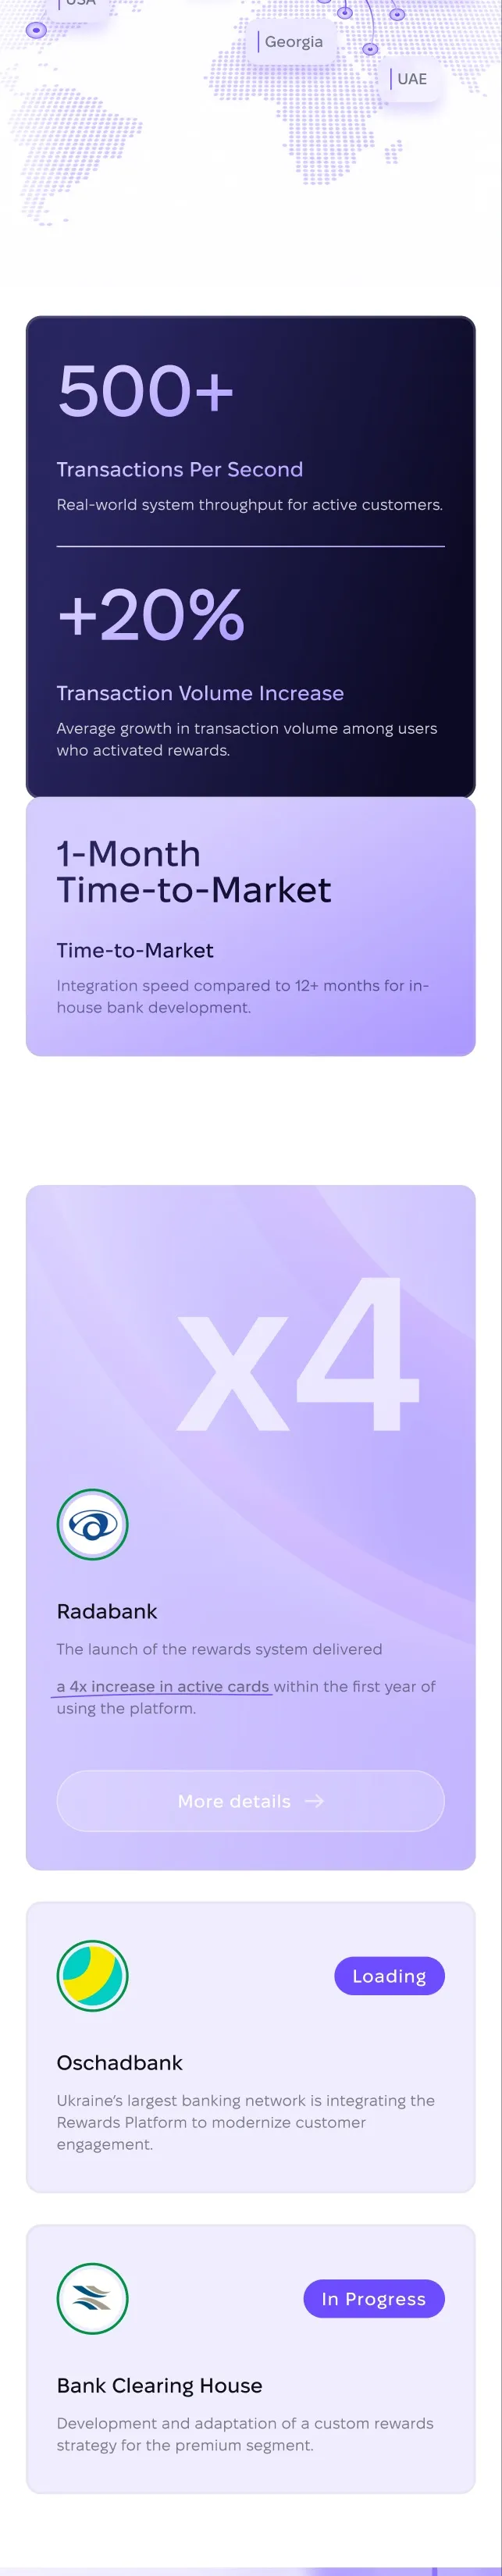
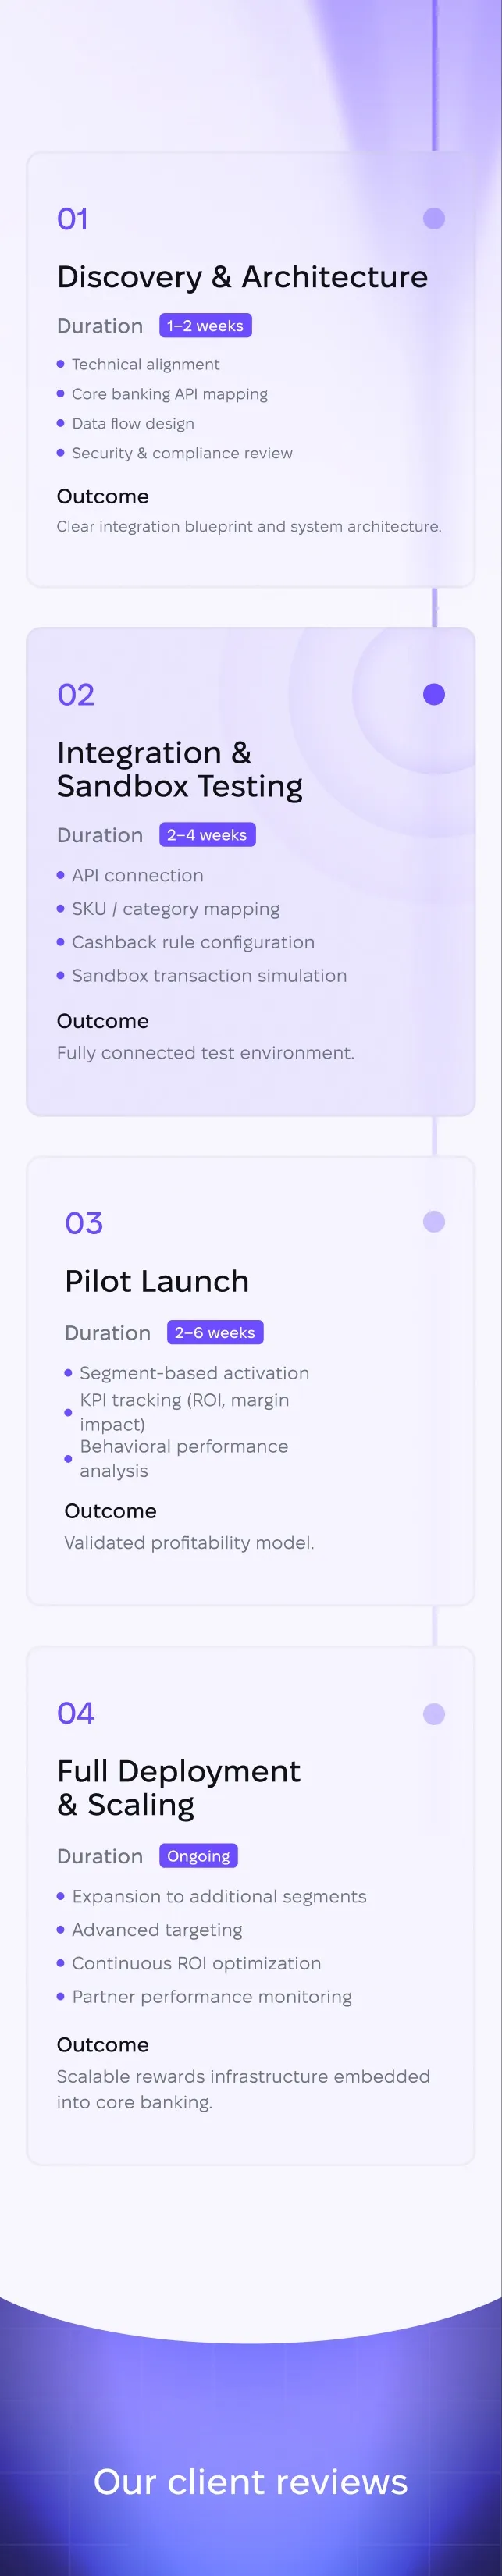
We know your ROI before the contract is even signed
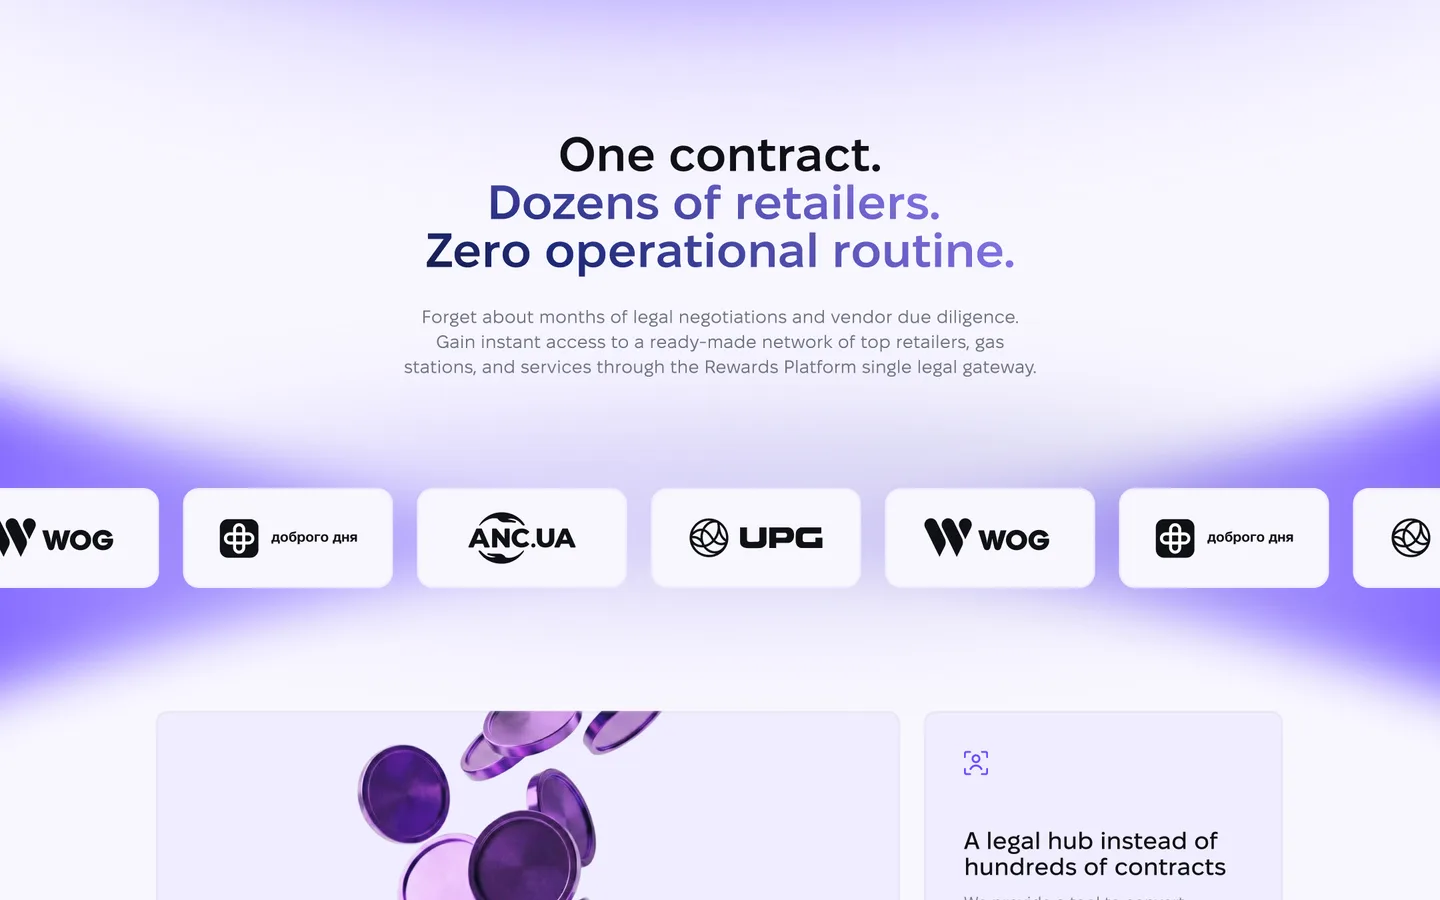
Client painHundreds of merchant agreements and a marketing budget of its own to fund rewards.
Business taskRemove the legal and budget barrier — that’s what actually stops a bank, more than technology.
MeaningOne contract — and partners pay for loyalty.
One contract. Dozens of retailers. Zero operational routine.
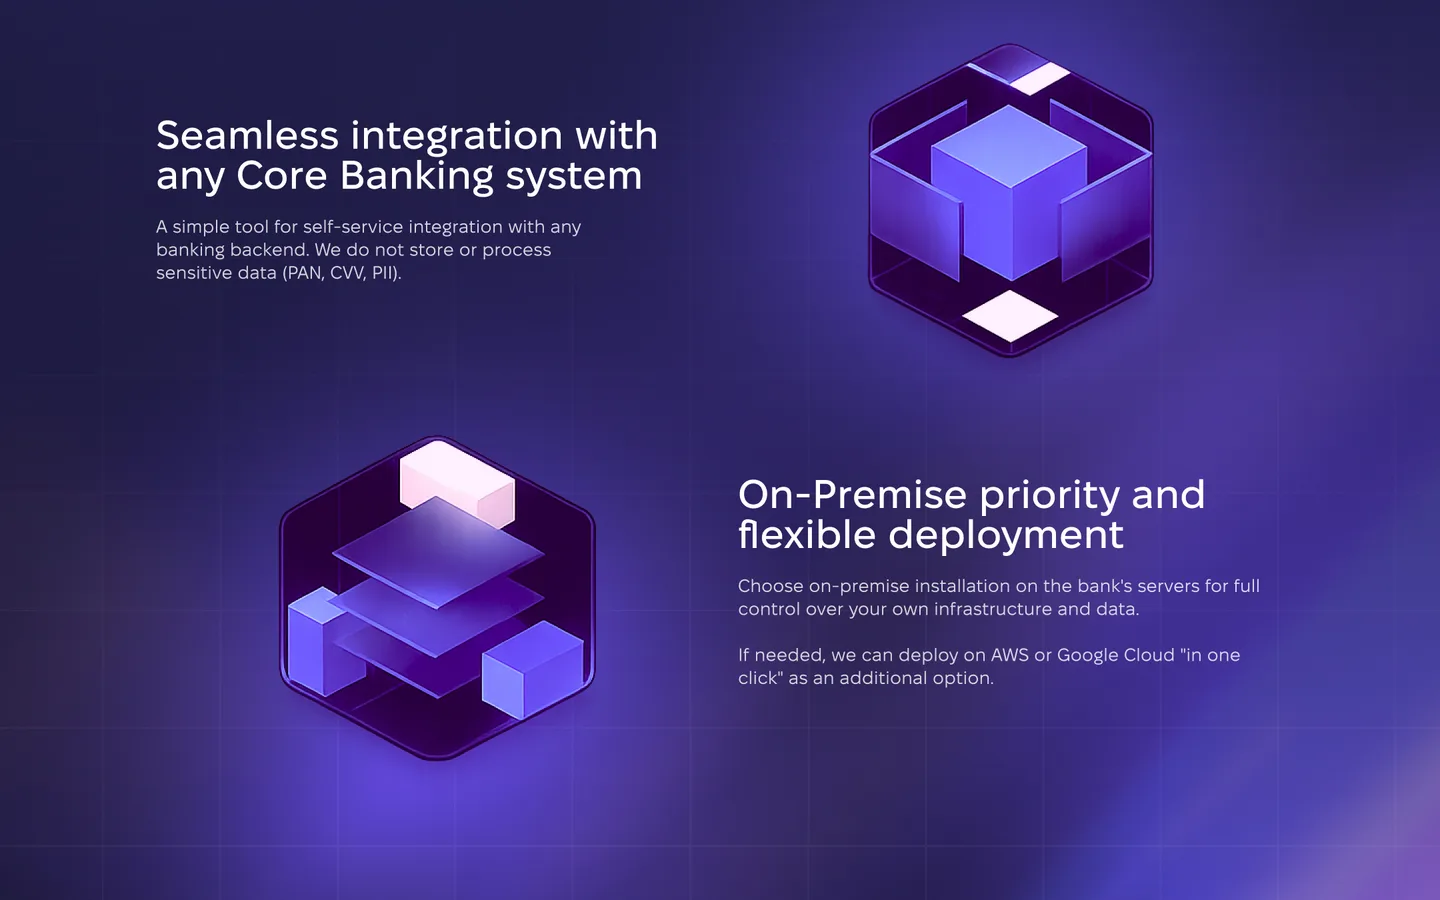
Client painA conservative bank is wary of handing its core to an outside system: security, the cloud, dependence on IT.
Business taskPresent 42Flows as infrastructure a bank can trust with core banking.
MeaningWe store no sensitive data, deploy on the bank’s servers and integrate with any system.
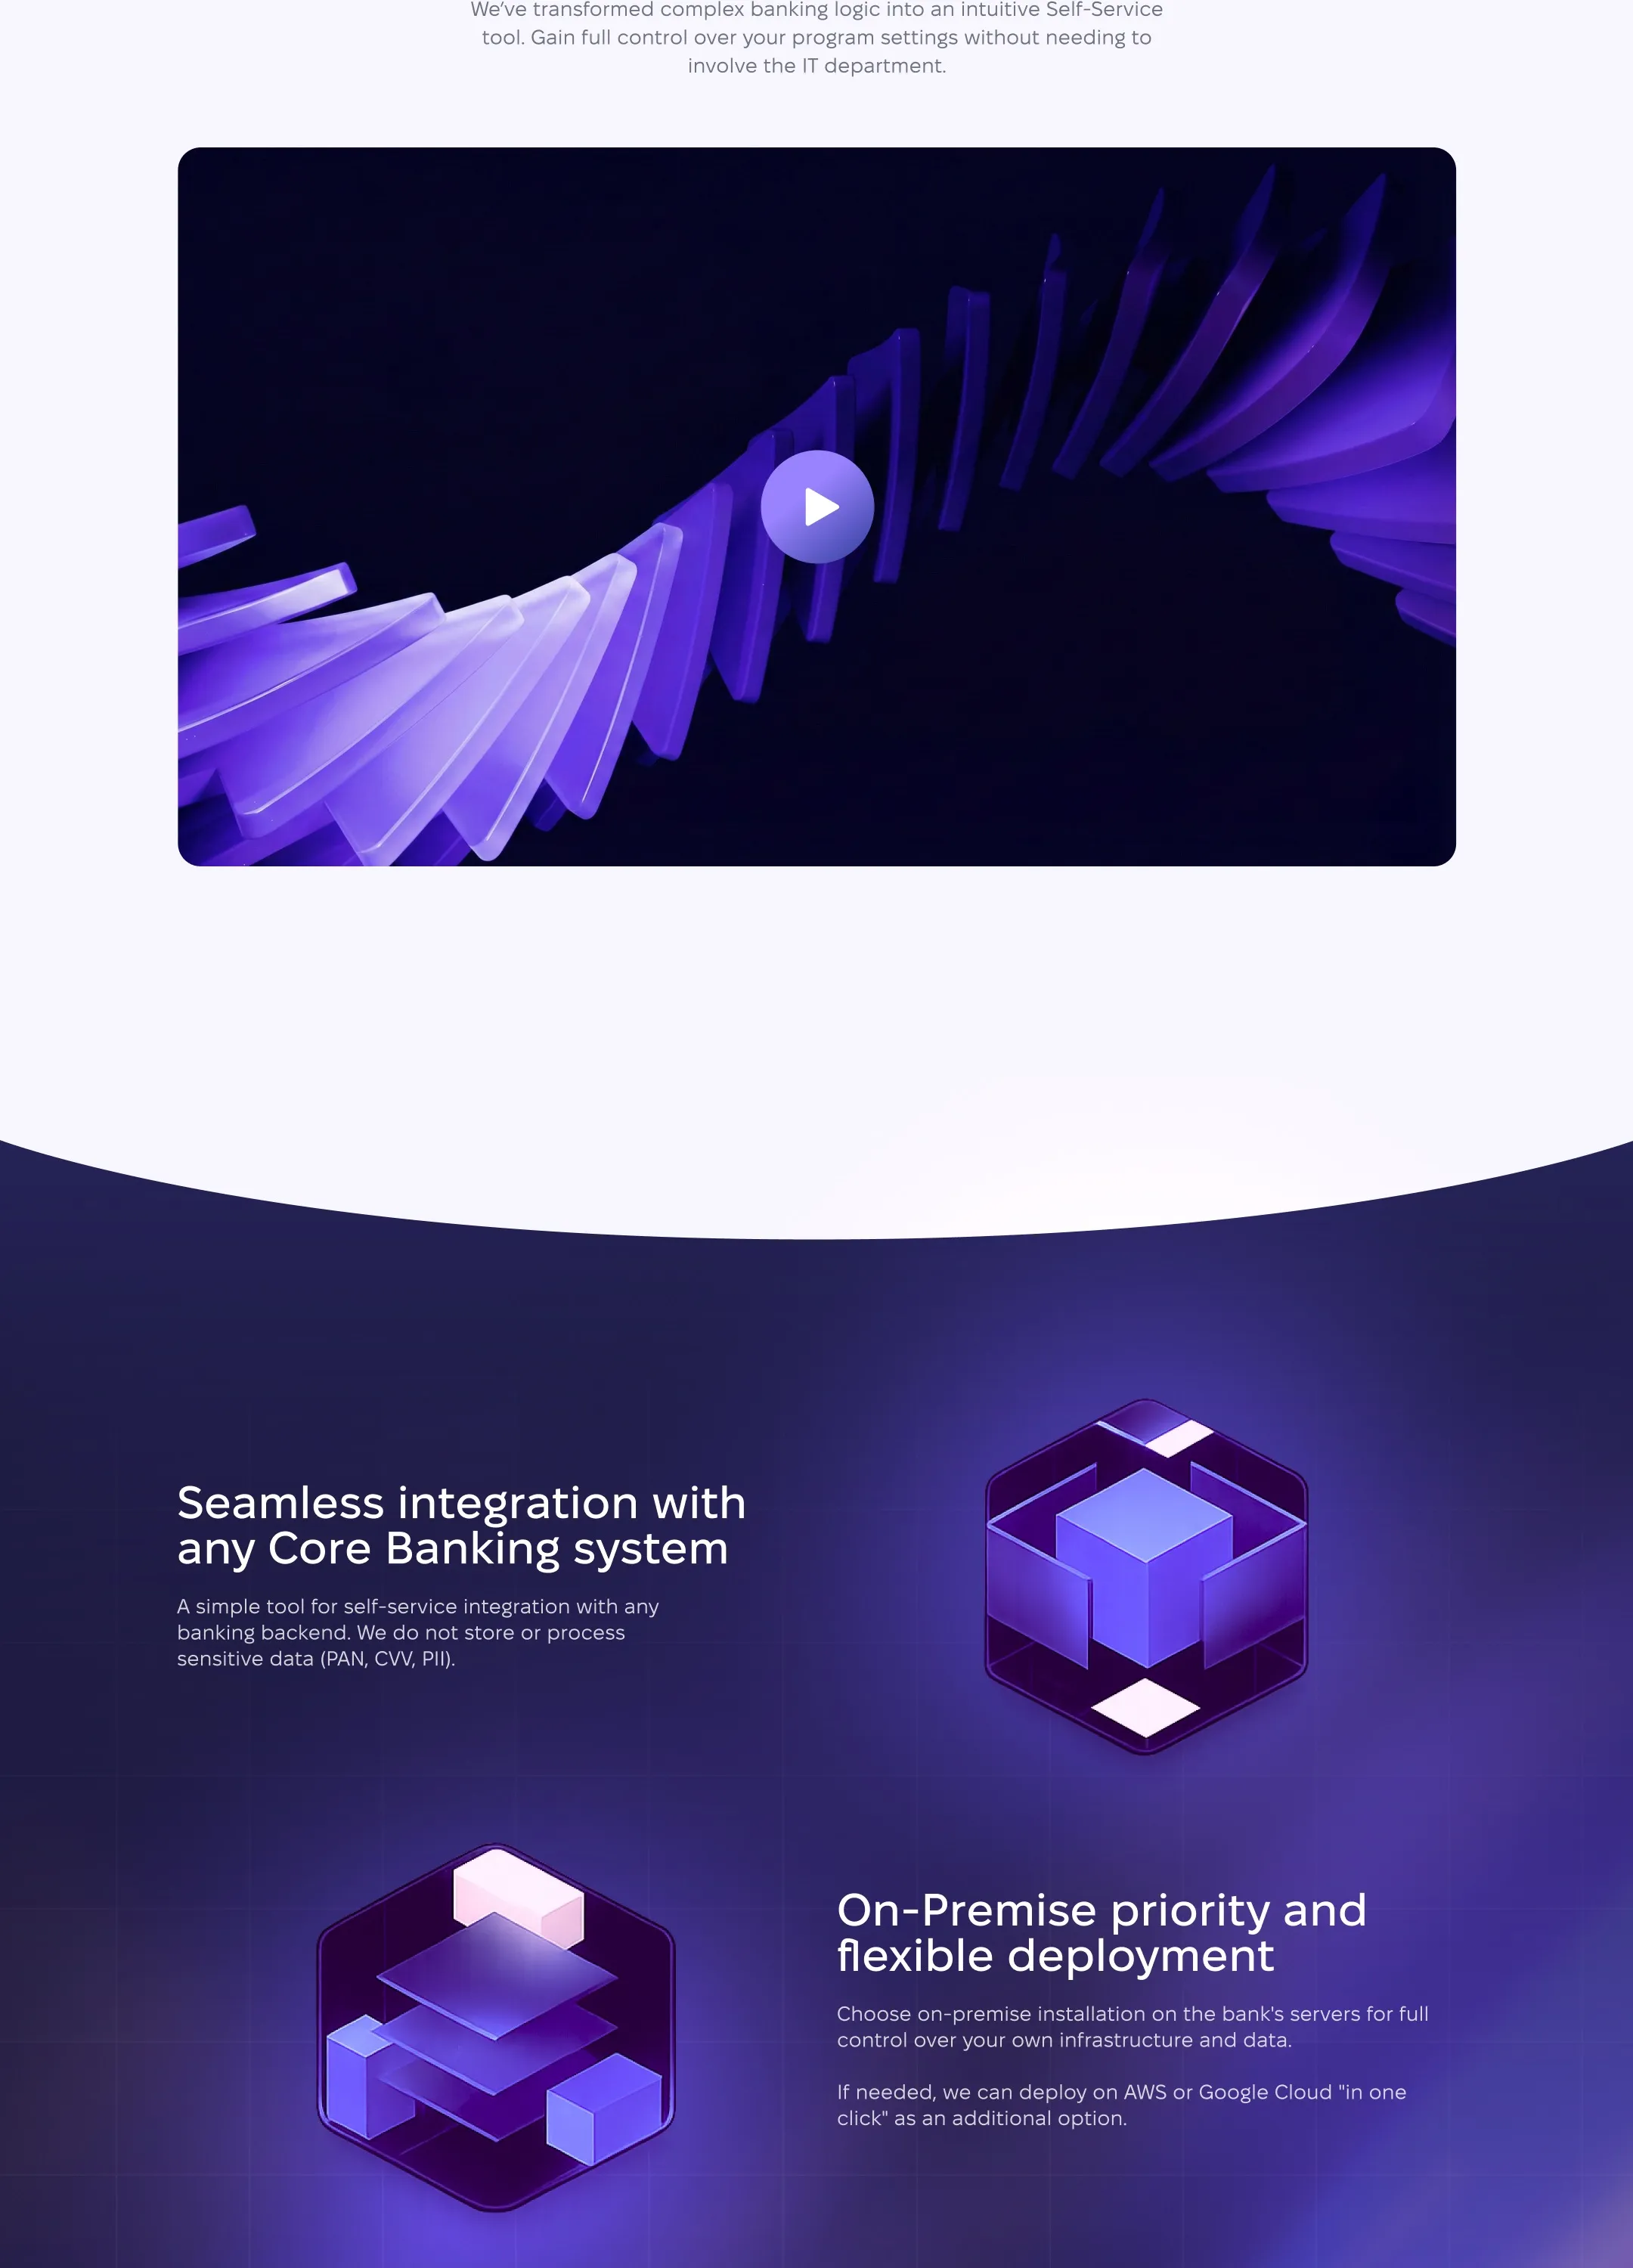
Seamless integration with any Core Banking system
On-Premise priority and flexible deployment
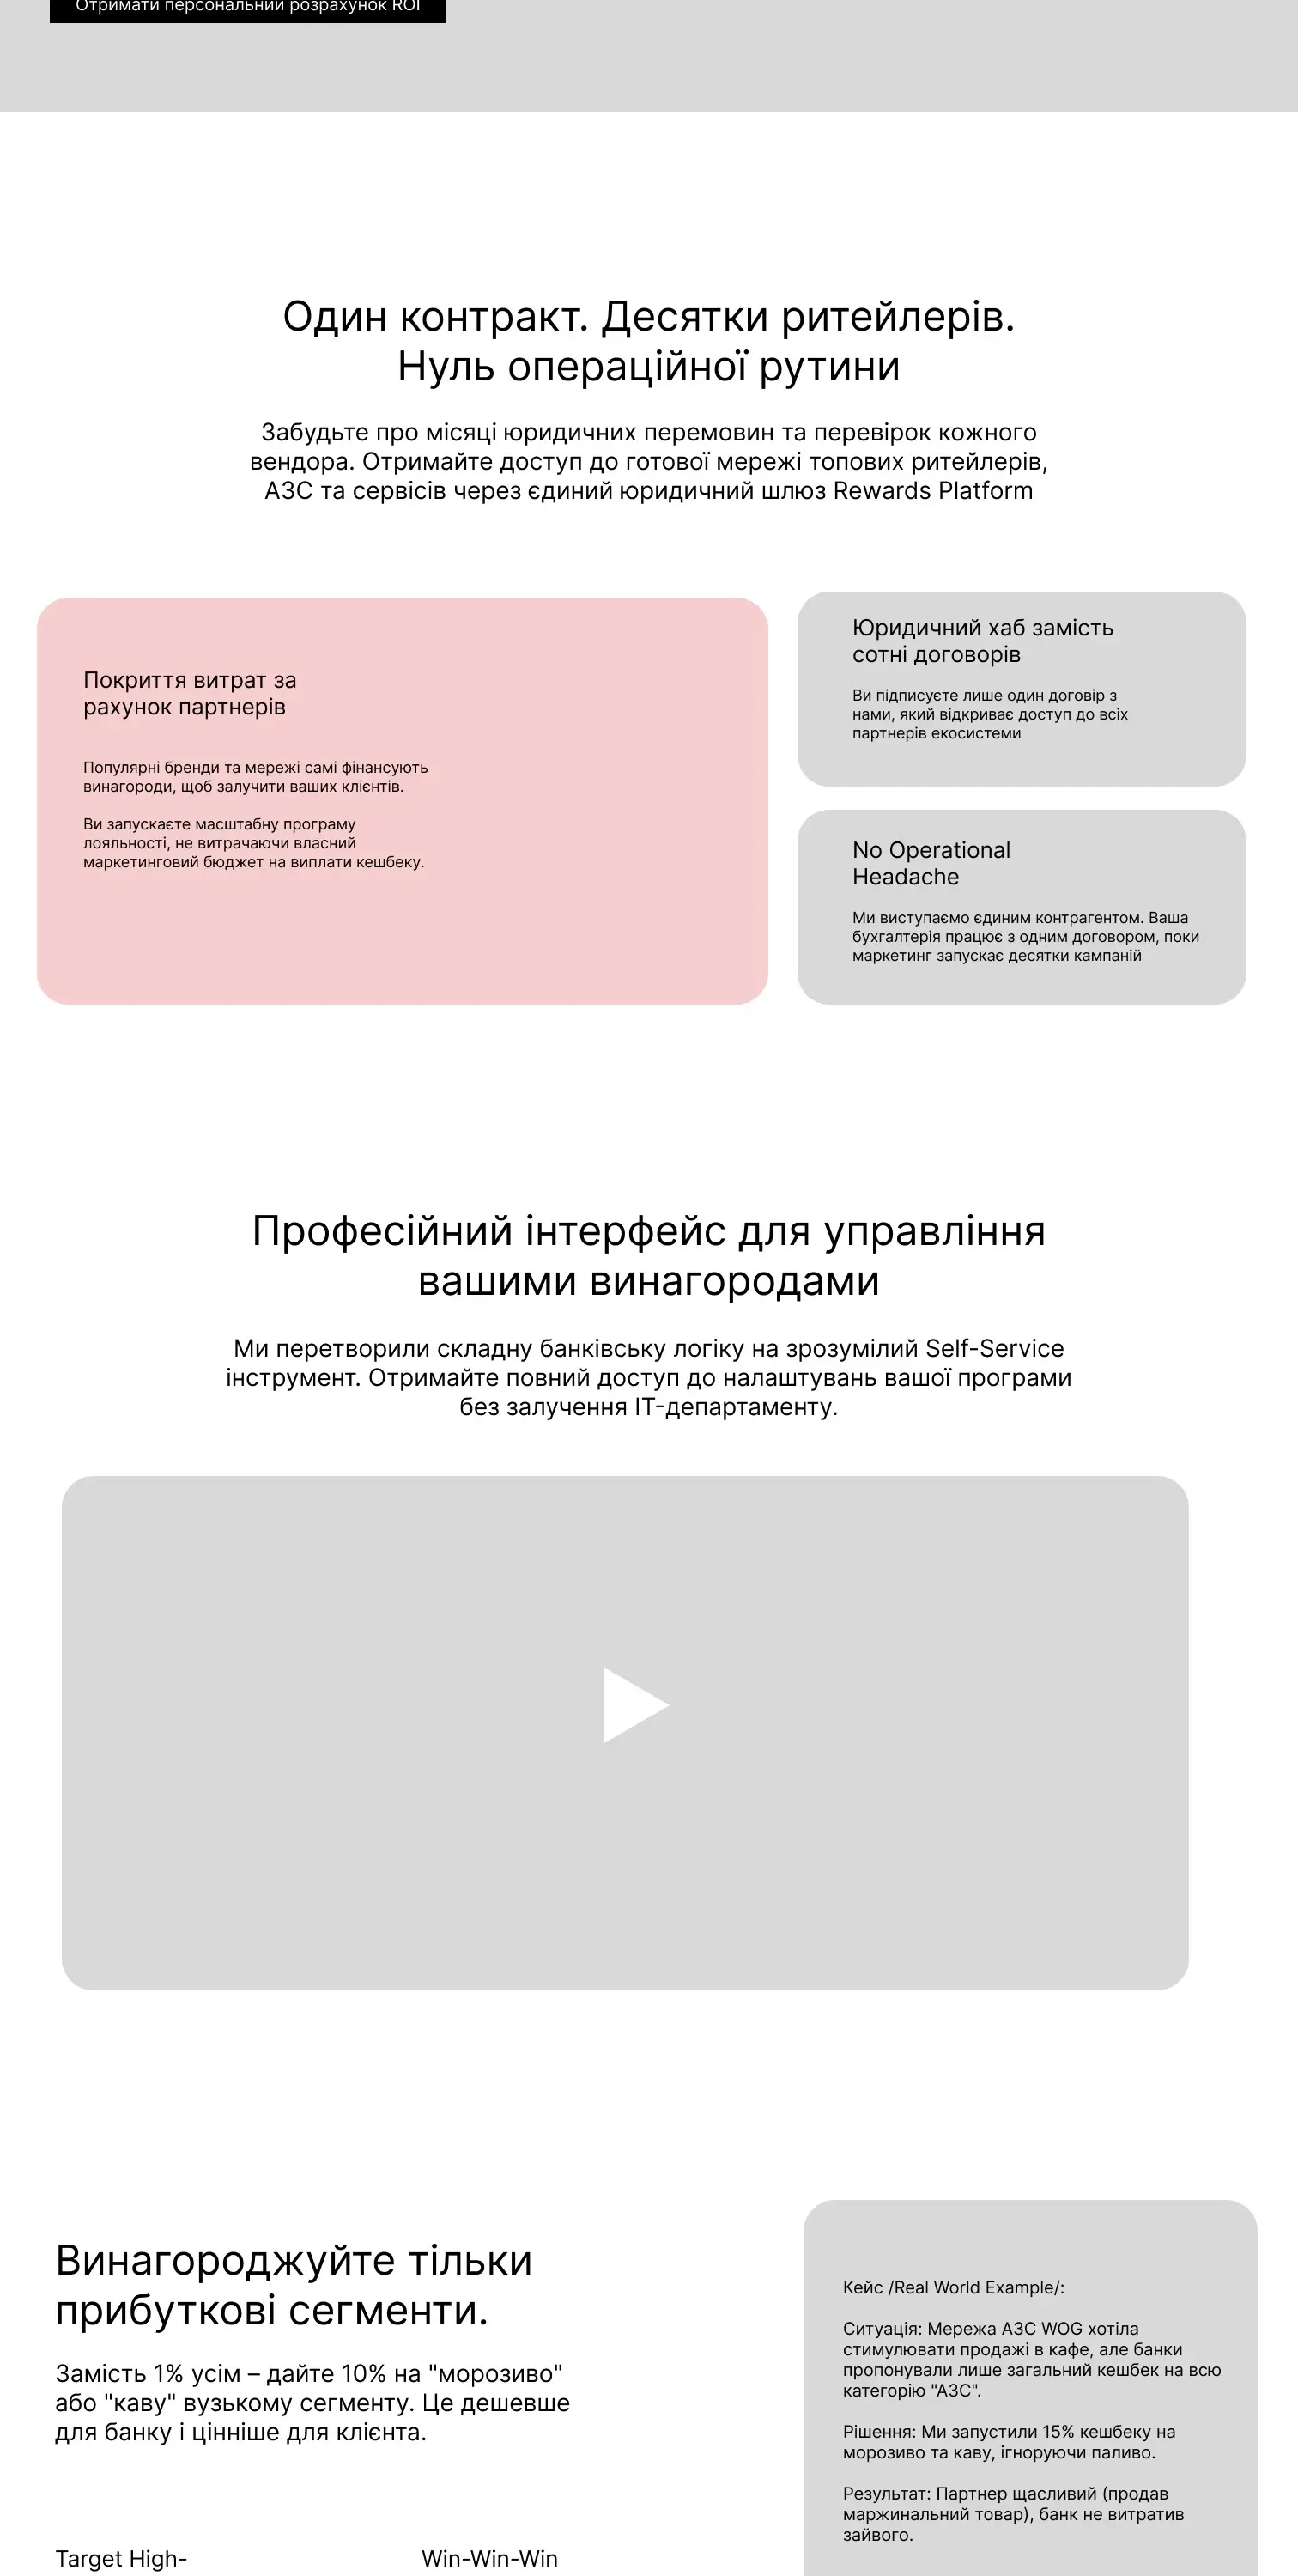
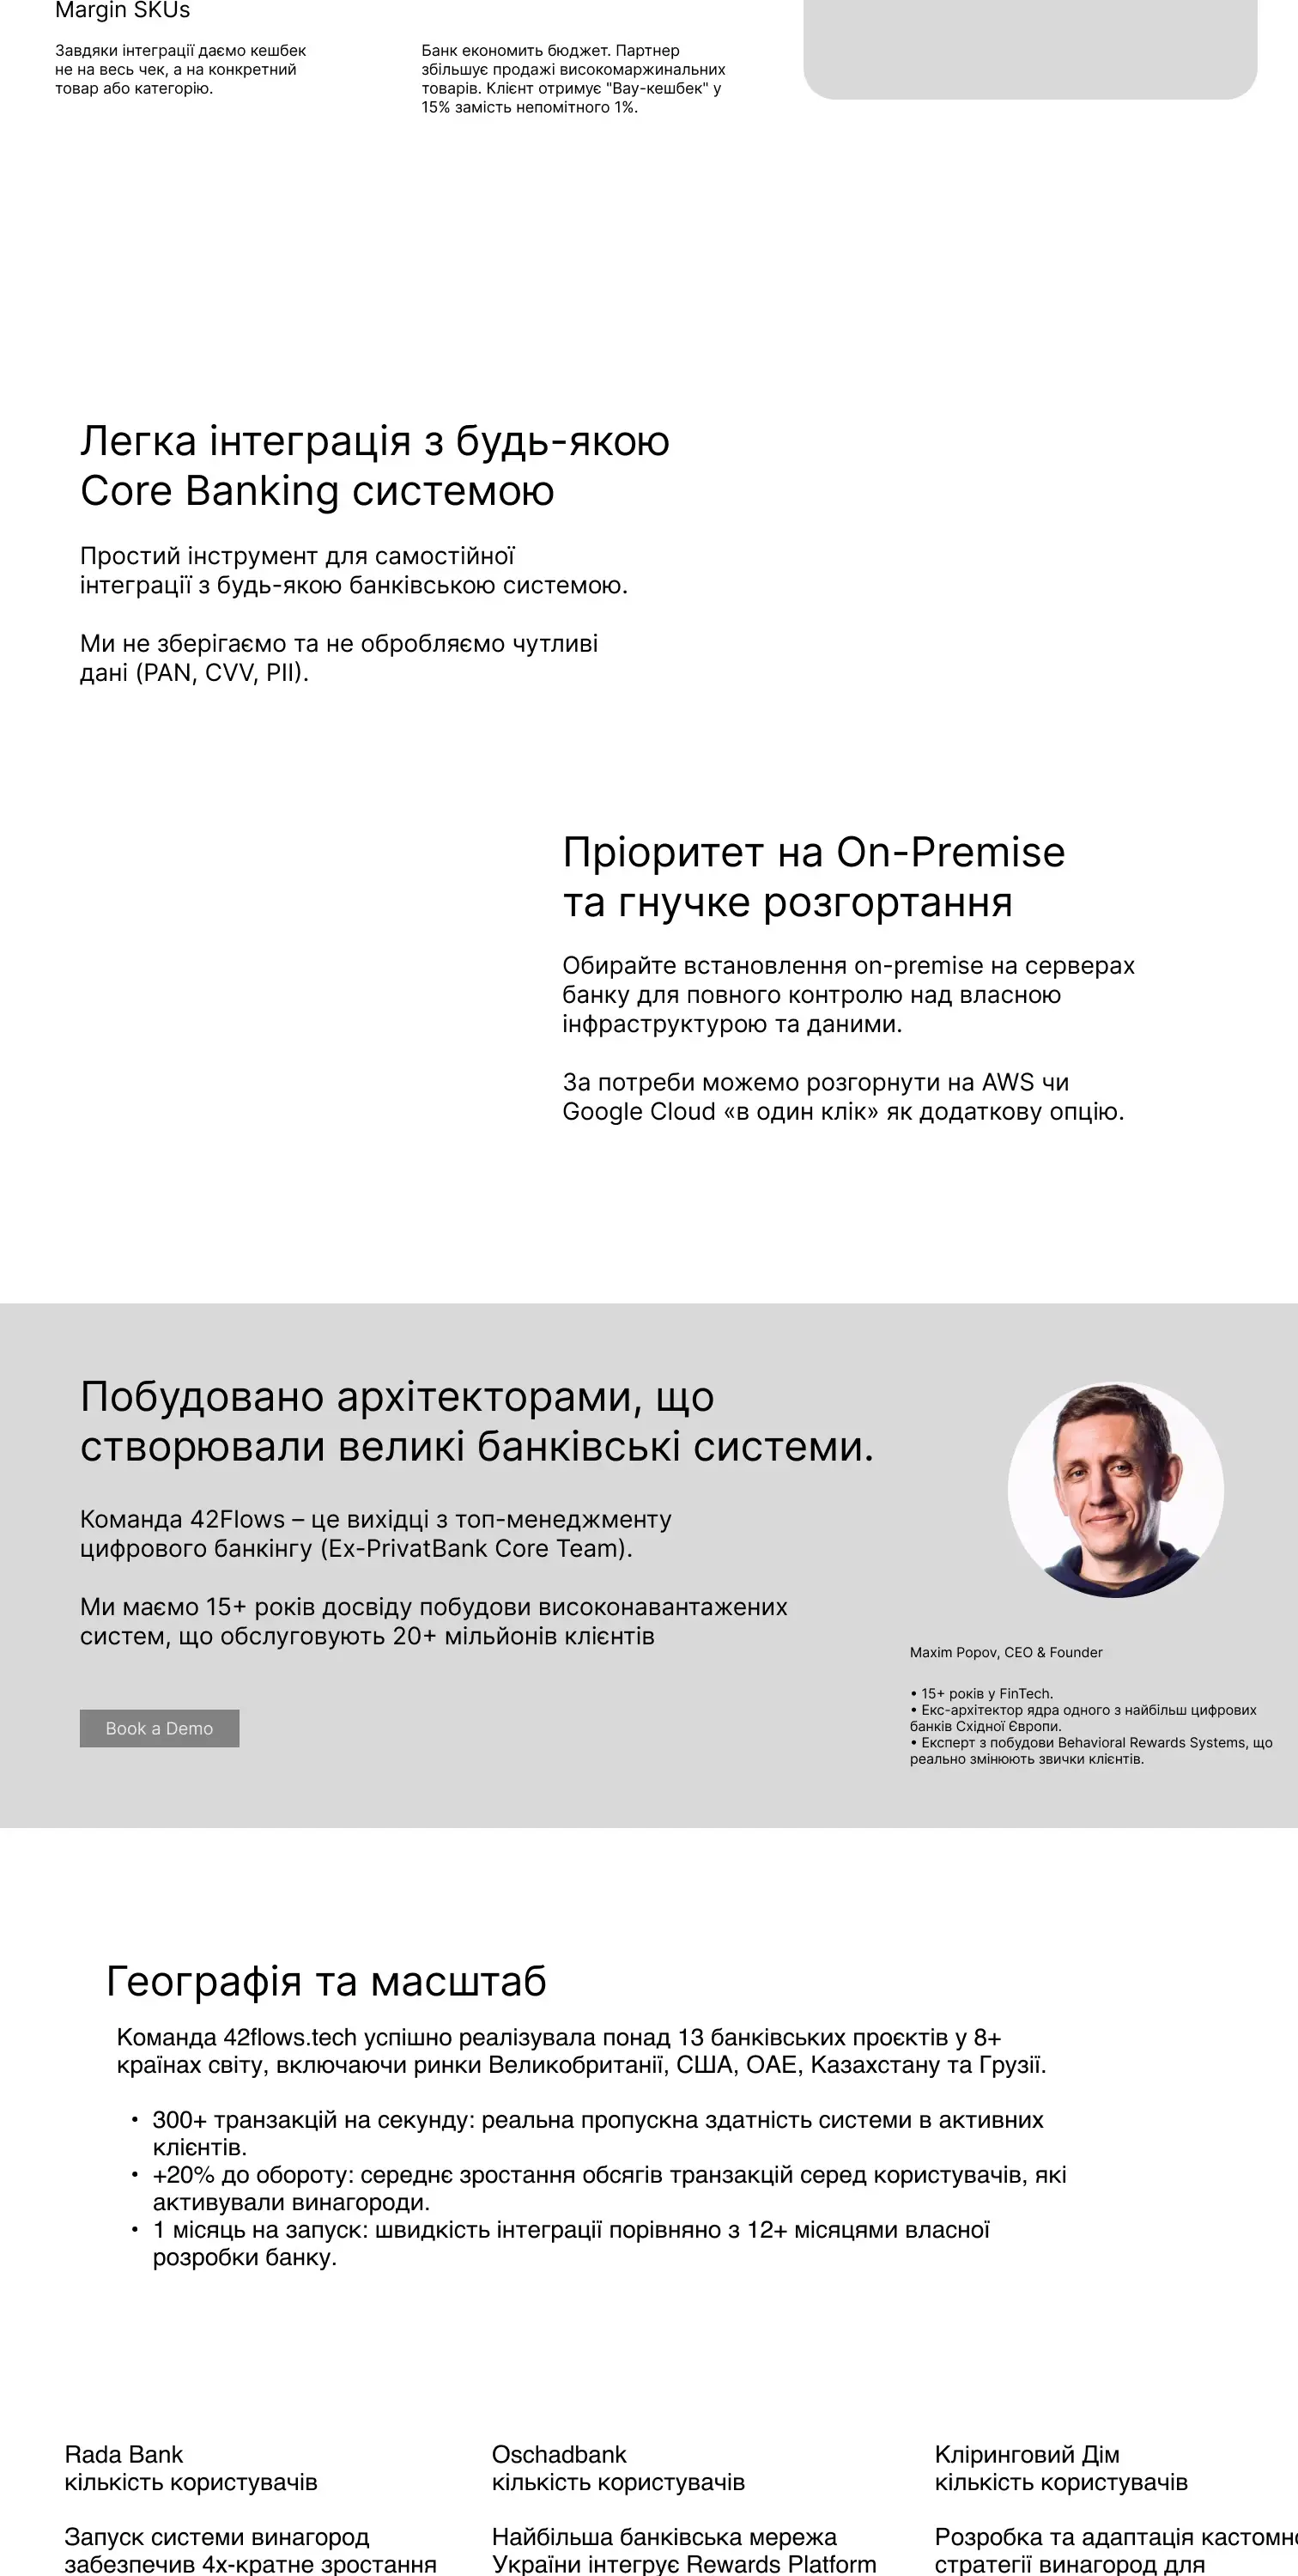
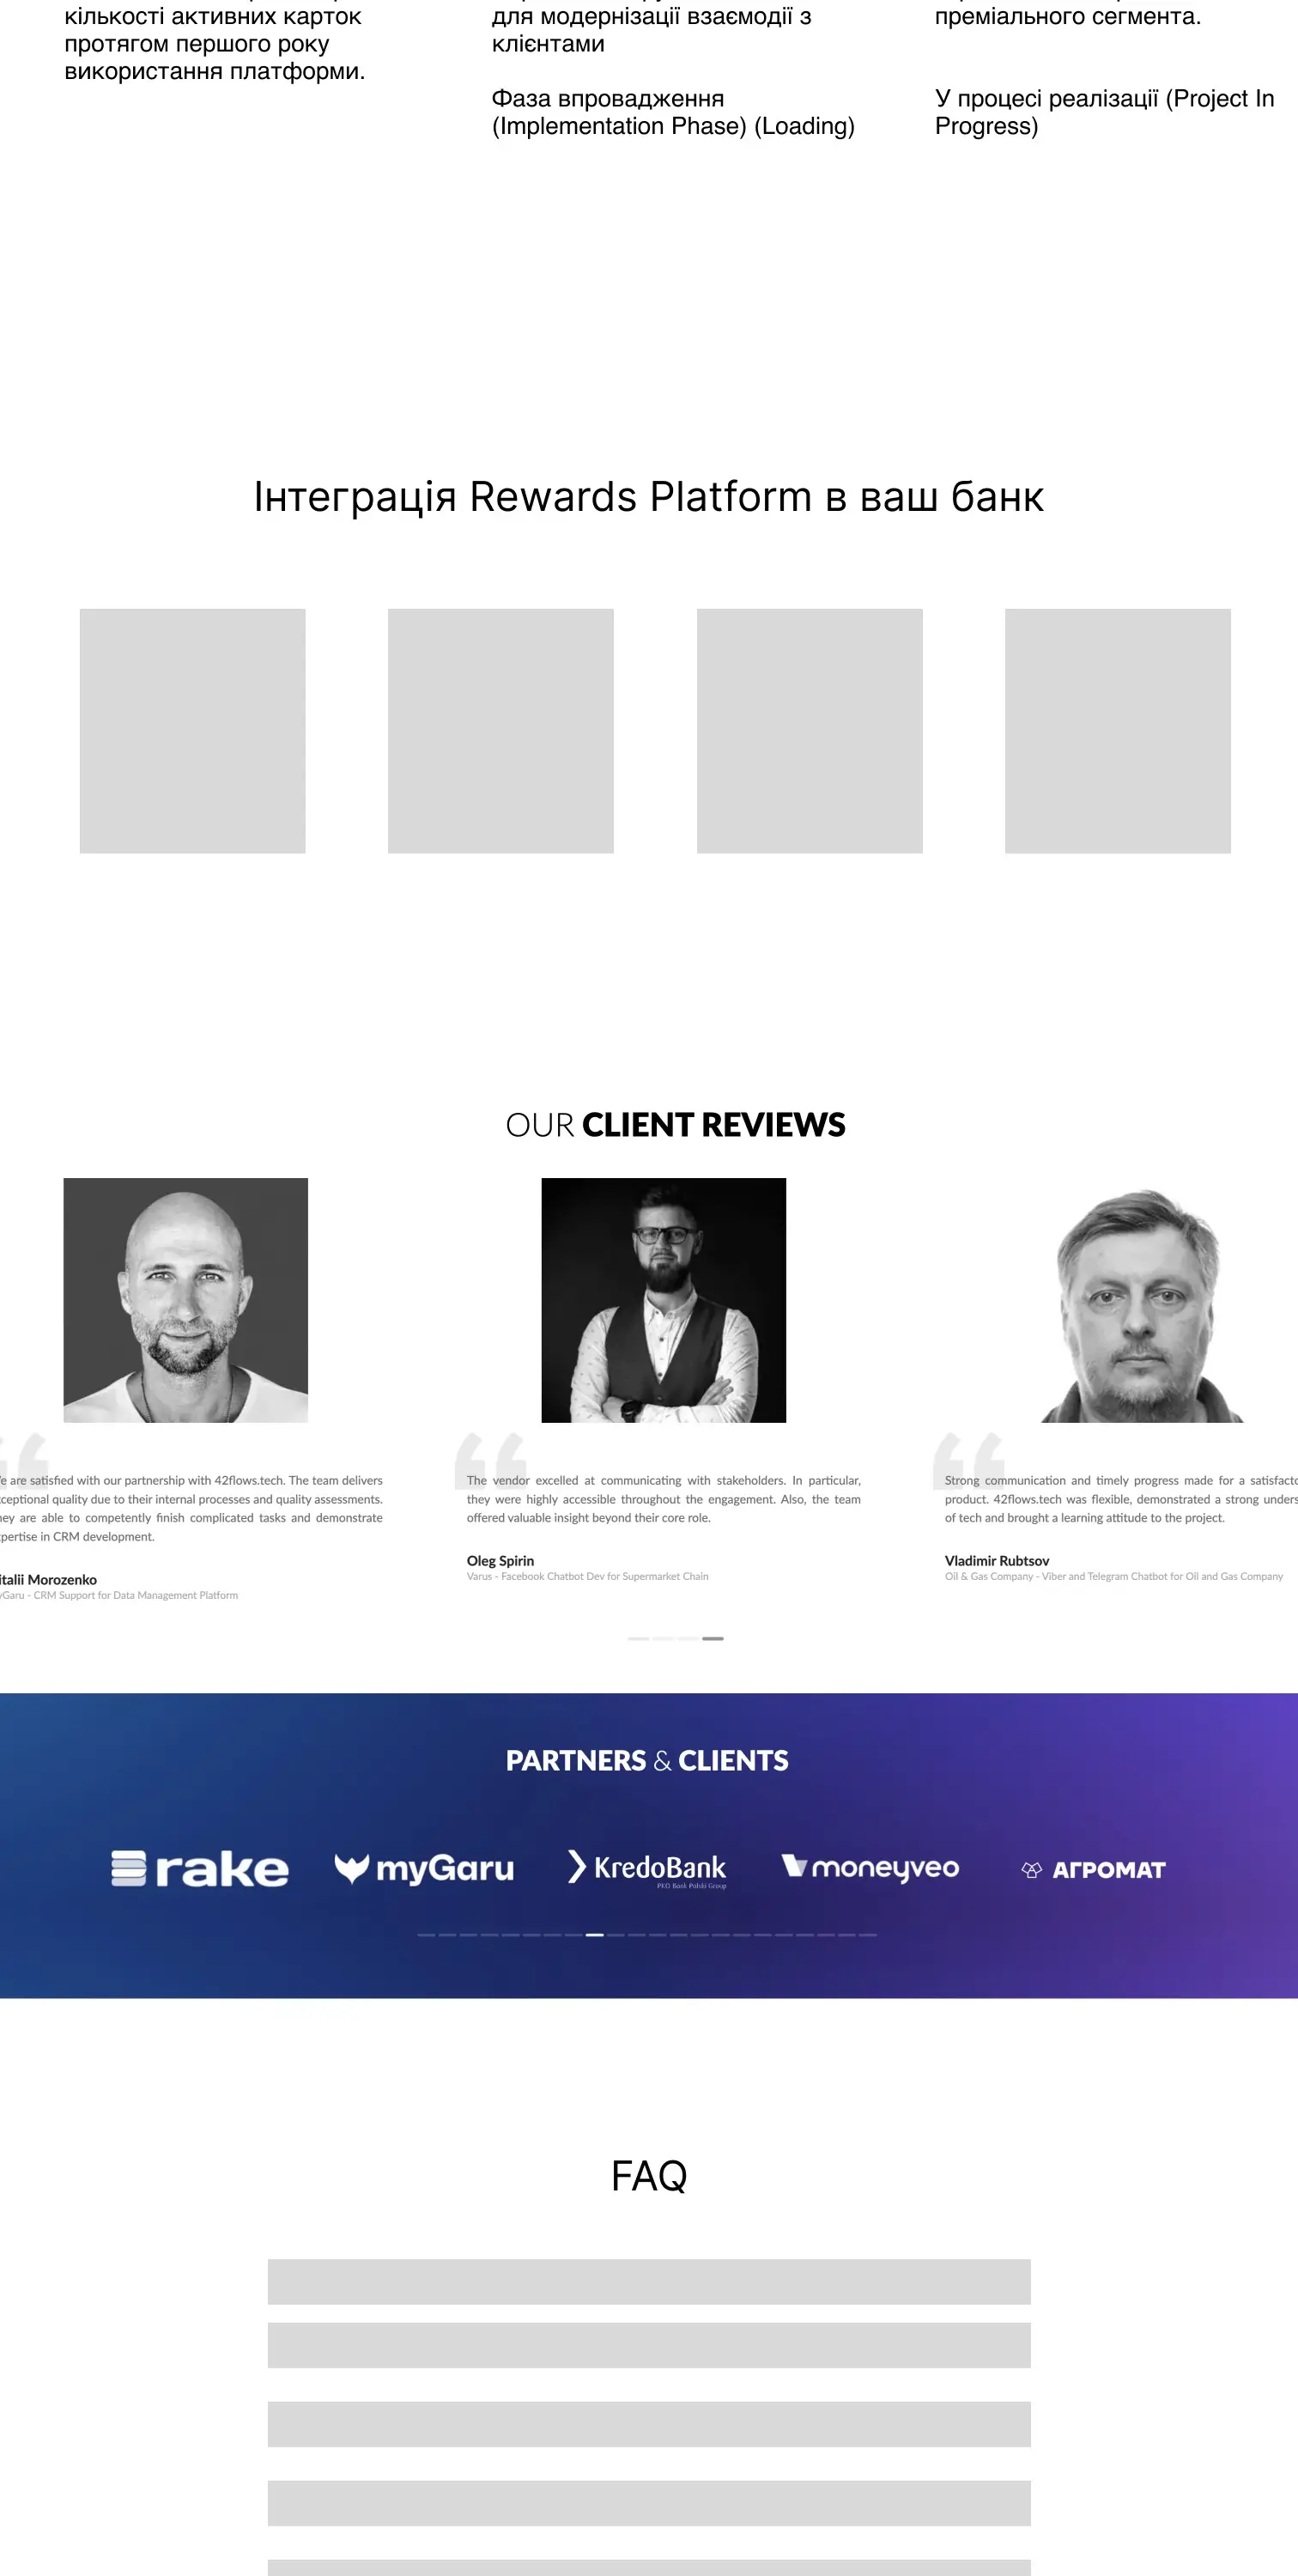
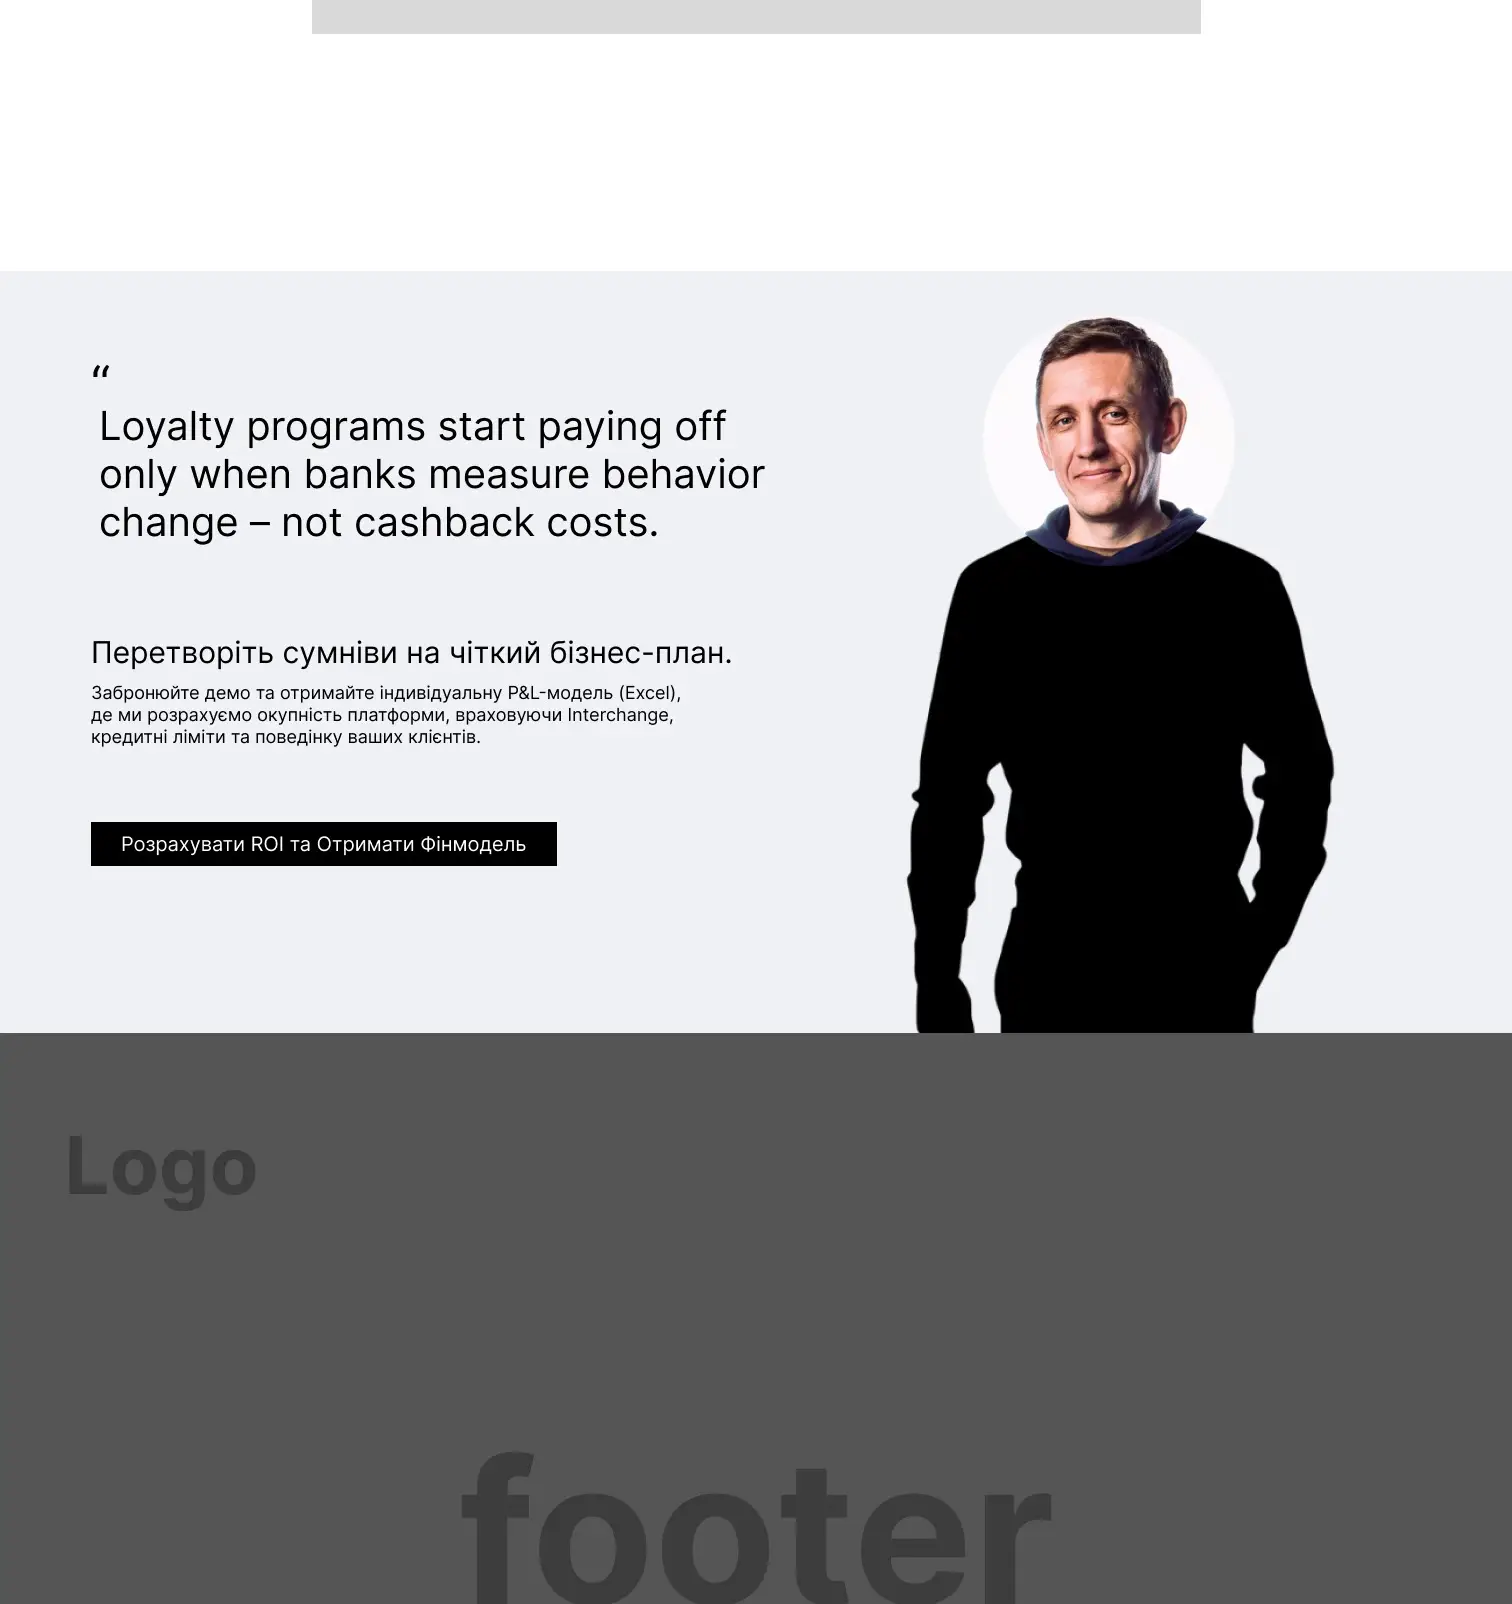
The page’s text prototype came before the first mockup: first we agreed on what to tell the bank and in what order, and only then on how it would look.
Website
Every block on the page answers a question the bank is already asking itself
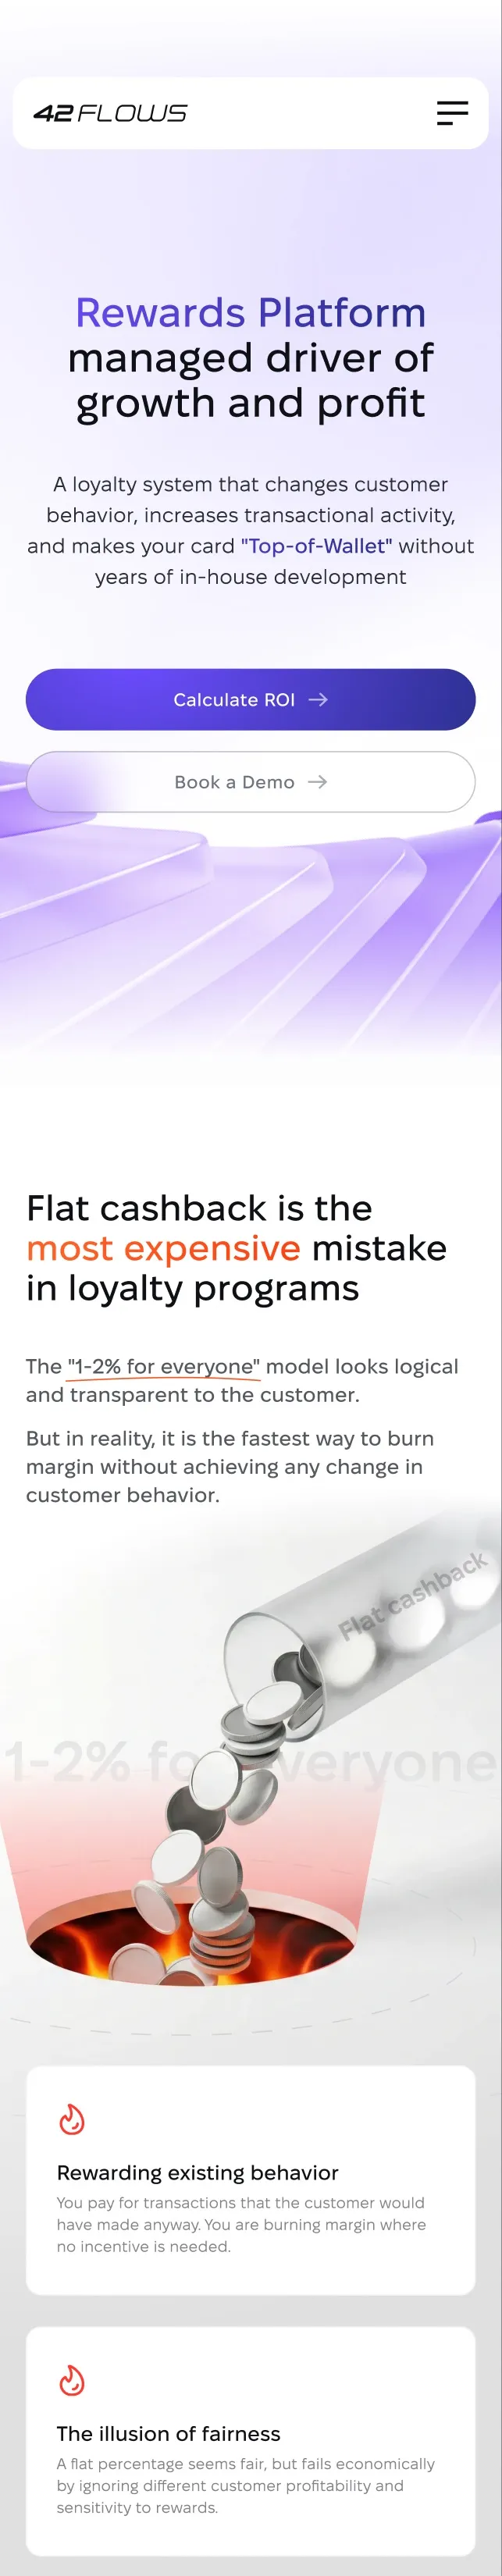
Switch funnel stages or step through the blocks with the arrows — the page in the browser jumps to the right spot. “Prototype” shows the same block in the text prototype we started from, and “Phone” shows the mobile version.
01/ 12Attention
First screen: a ready product
We heard42Flows is already perceived as a ready platform and evaluated as infrastructure with ROI.
We didRewards Platform — “a managed driver of growth and profit.” Two actions upfront: calculate ROI and book a demo. Calm 3D modules replace the clip art.
02/ 12Interest
The problem: “1–2% for everyone”
We heard“Blanket” cashback rewards groceries and fuel the customer would buy anyway — the bank burns margin where no incentive is needed.
We didThe page opens with the bank’s mistake before it shows the product: three reasons flat cashback works as a discount and builds no loyalty.
03/ 12Interest
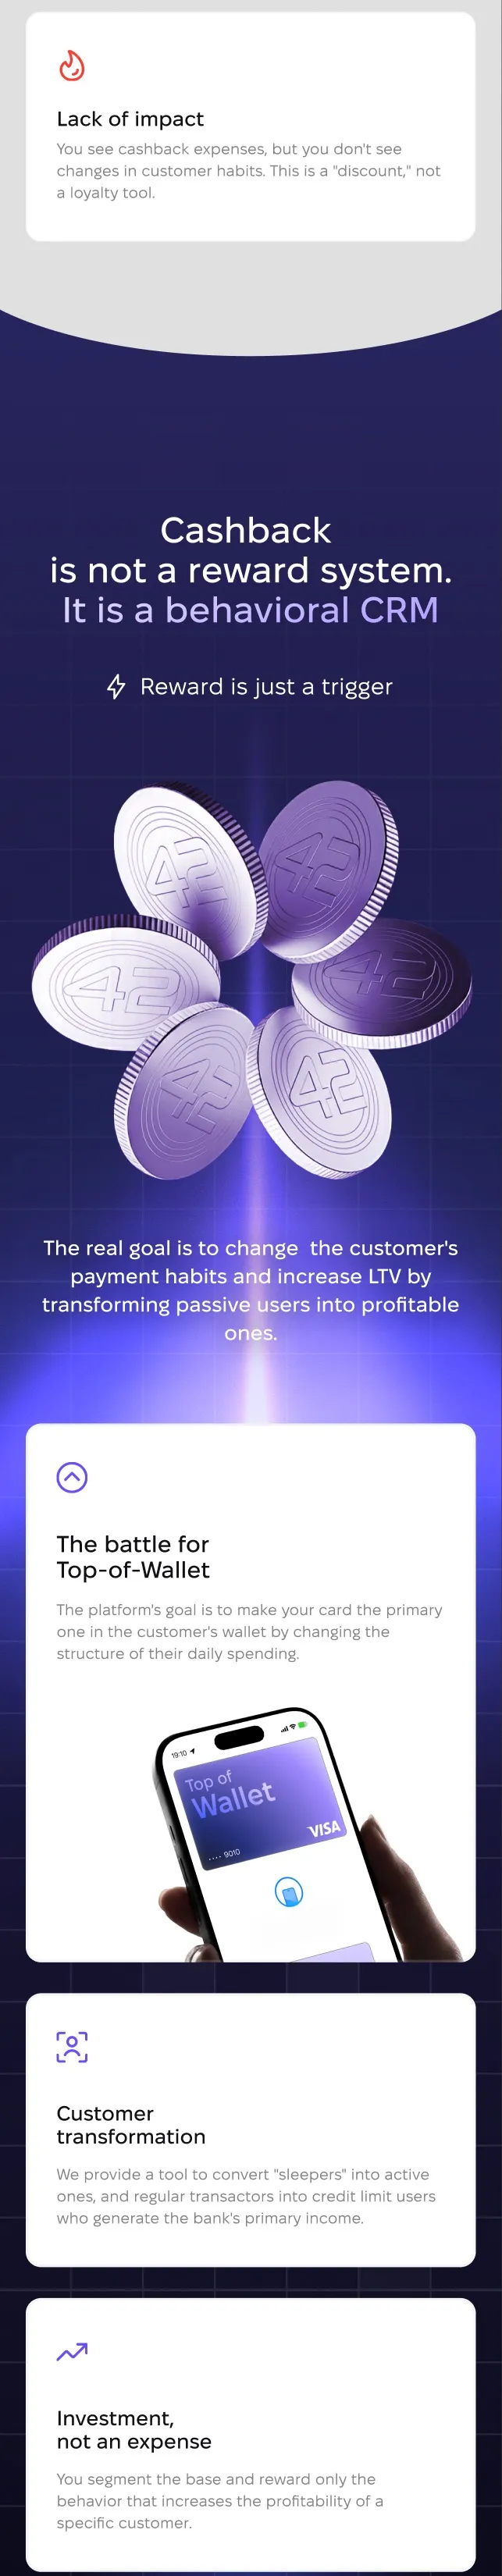
The solution: a behavioral CRM
We heardWhat the team is really building is a tool for behavior change: dormant customers become active, transactors become credit-limit users.
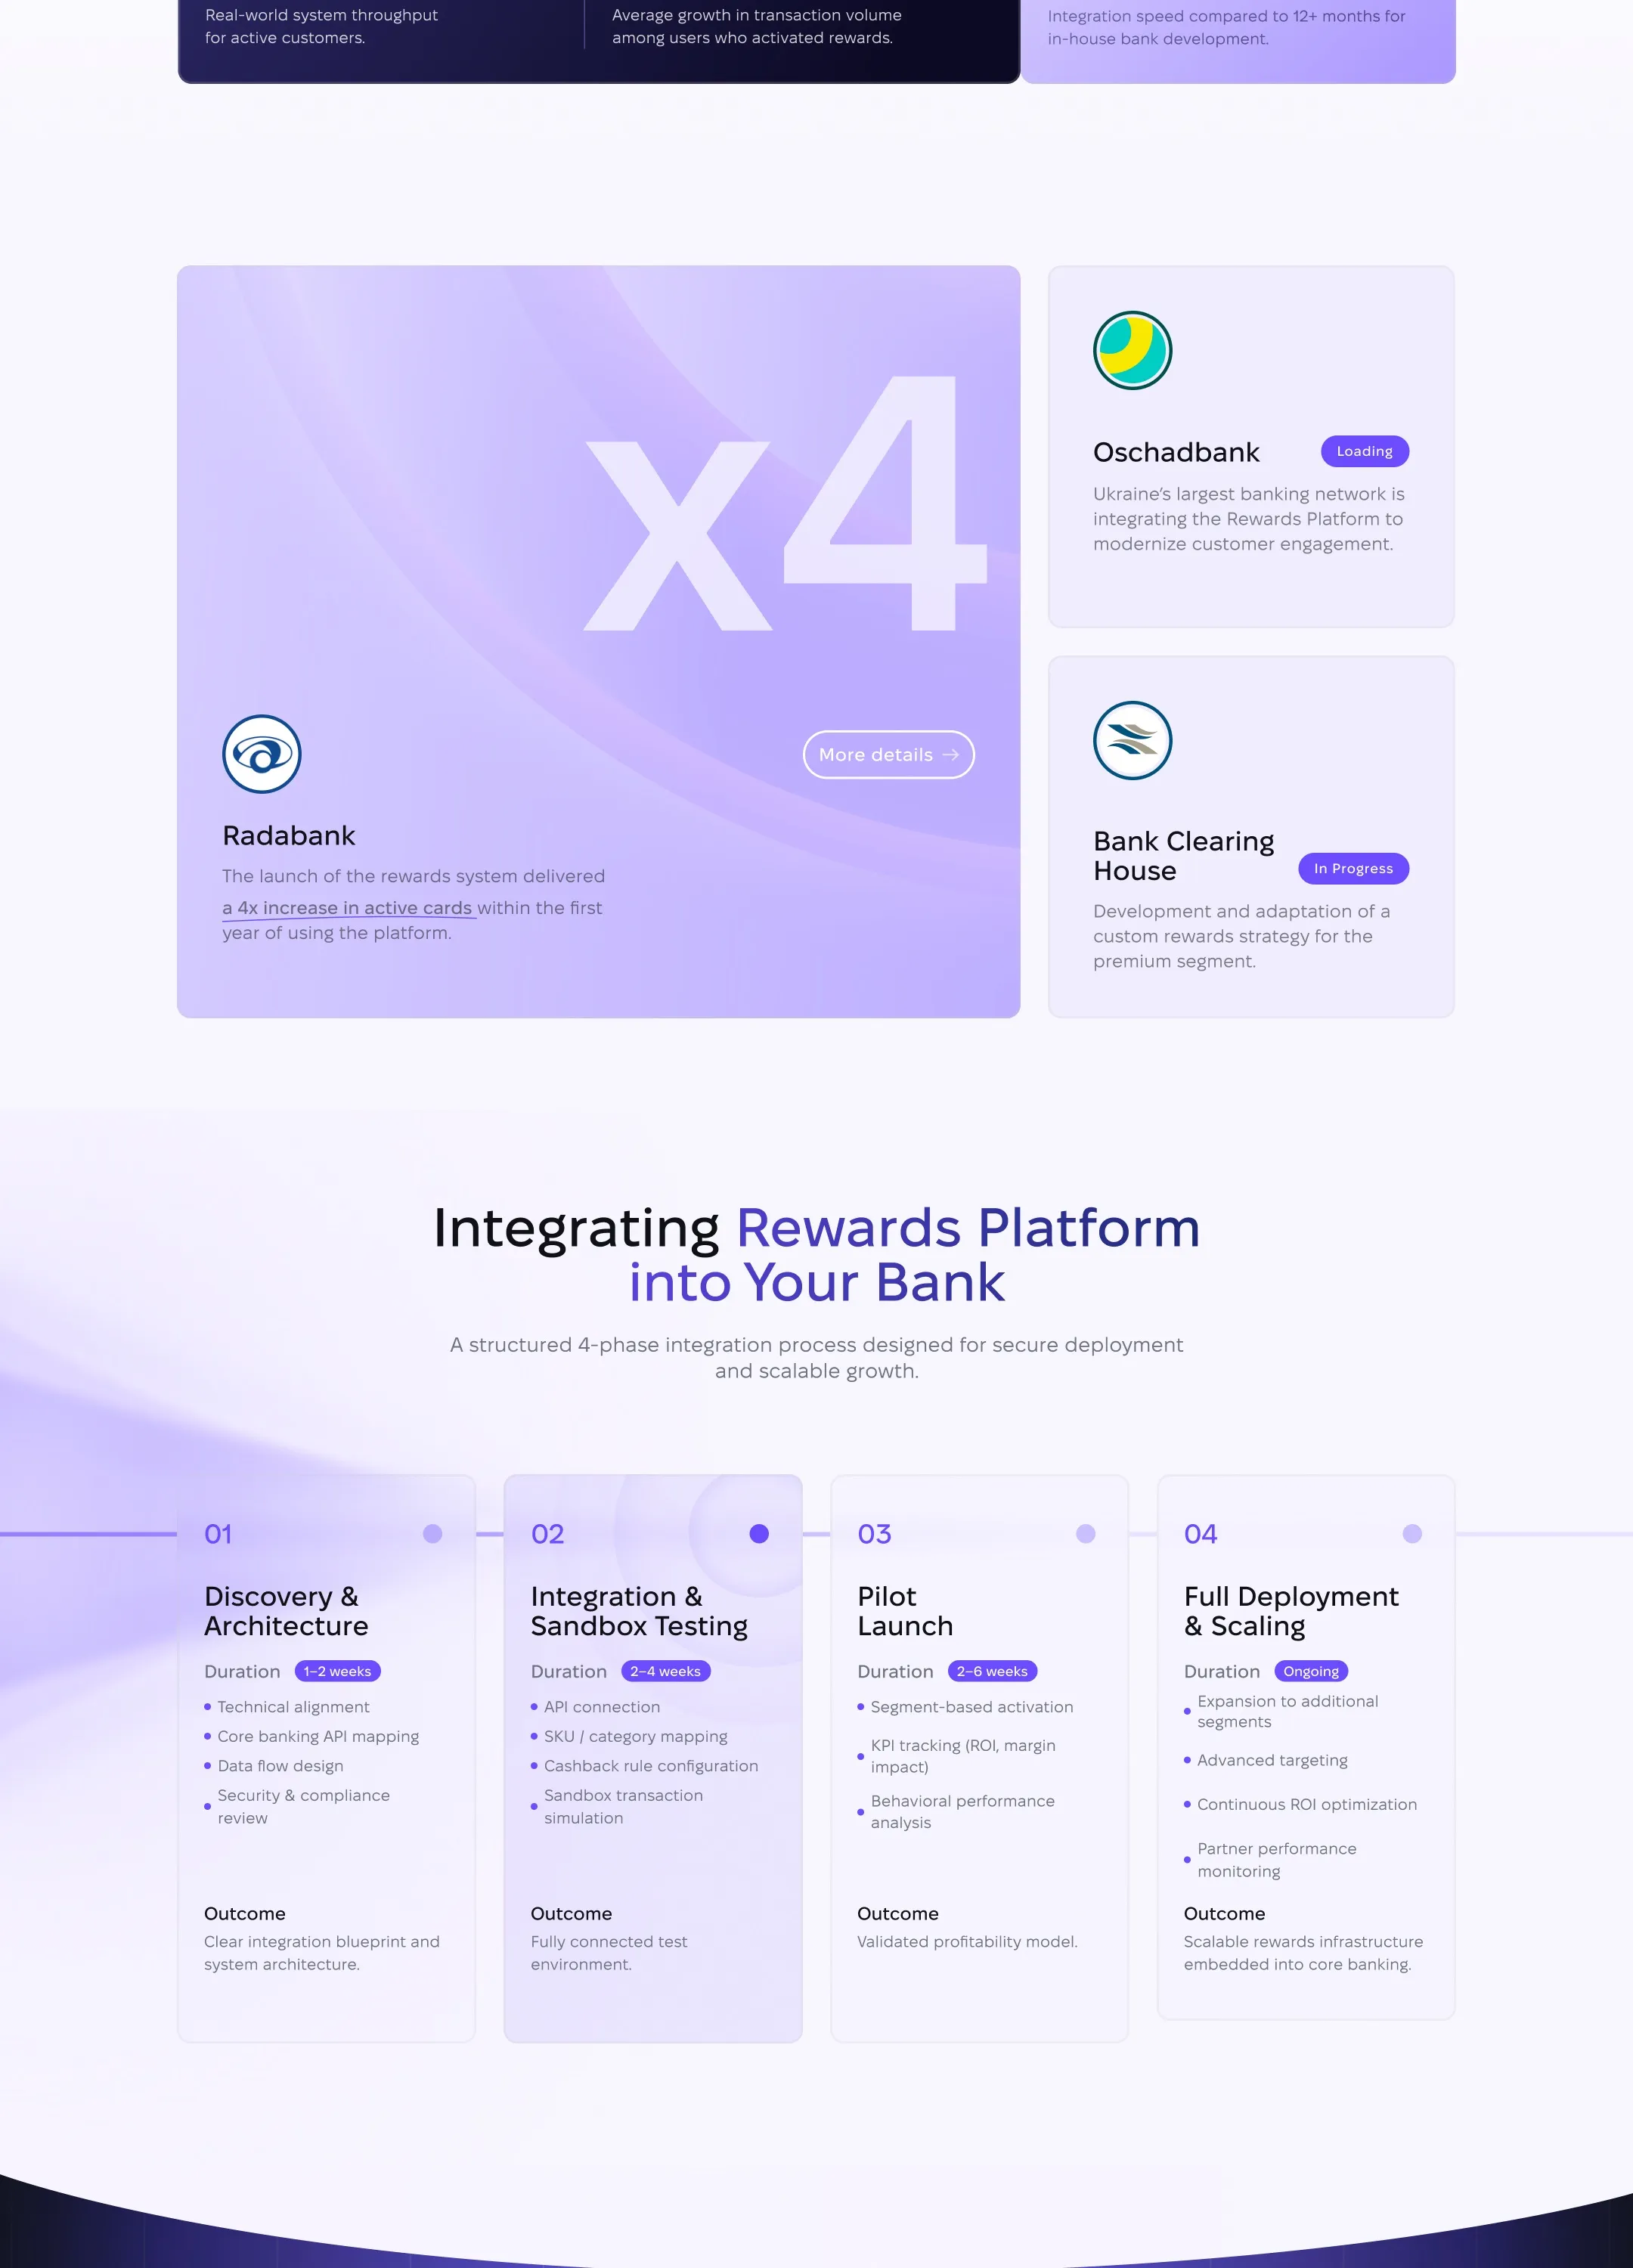
We did“Cashback is not a reward system. It is a behavioral CRM” — with proof: +20% transaction volume among customers who activated rewards.
04/ 12Interest
The hook: ROI before the contract
We heardA financial model changes the bank’s attitude: it removes the finance team’s pessimism before the first meeting.
We did“We know your ROI before the contract is even signed”: a personal four-year P&L covering interchange, credit limits, churn and unredeemed bonuses.
05/ 12Desire
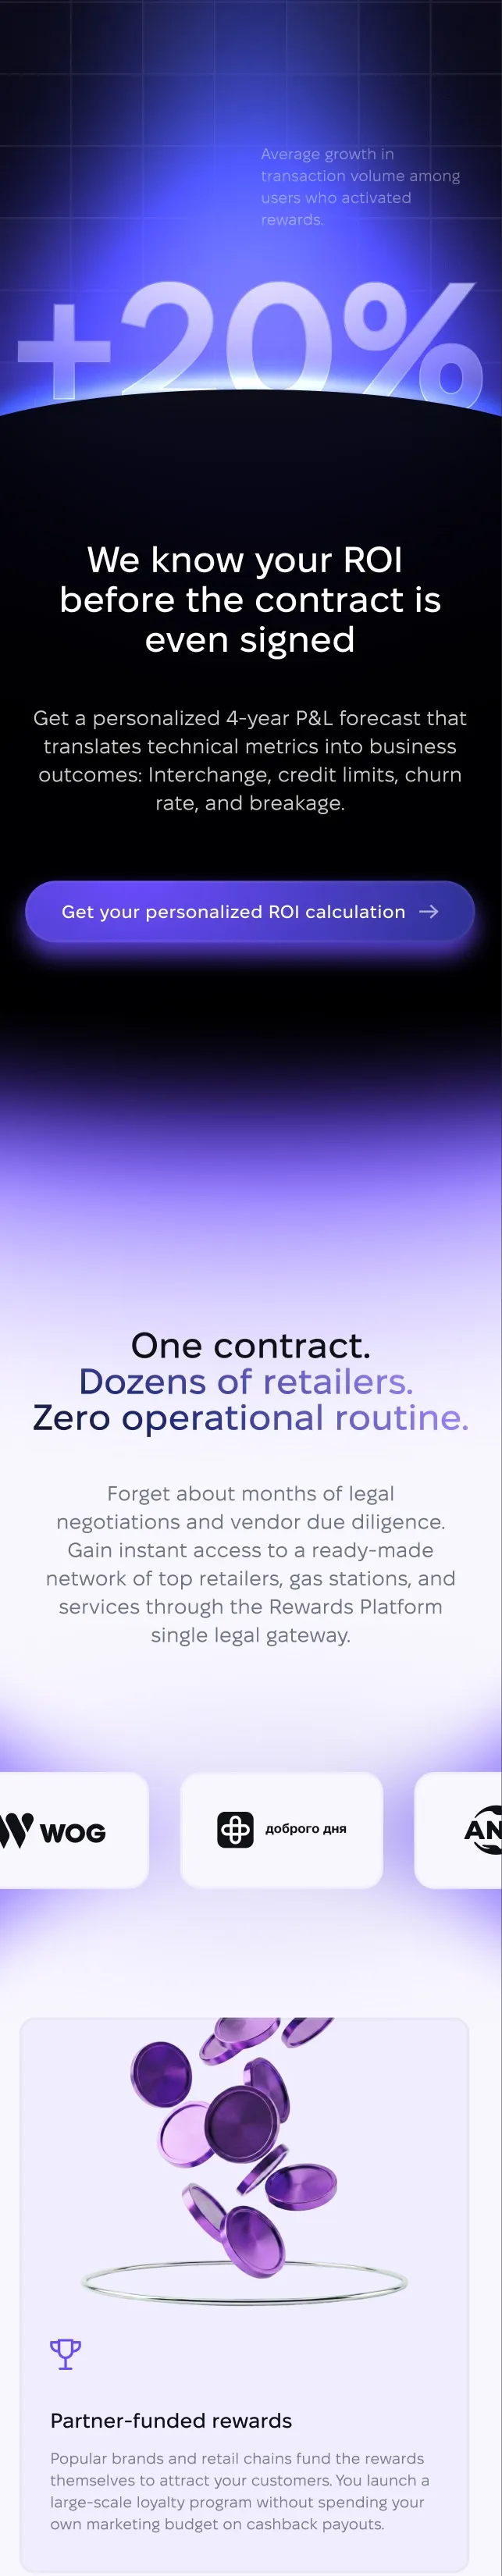
Partners pay for loyalty
We heardFor a bank, the legal side matters more than the API: a hundred merchant agreements are scarier than an integration.
We didThe emphasis moves from “one connection” to “one contract”: dozens of retailers through a single agreement, with rewards funded by the partners themselves.
06/ 12Desire
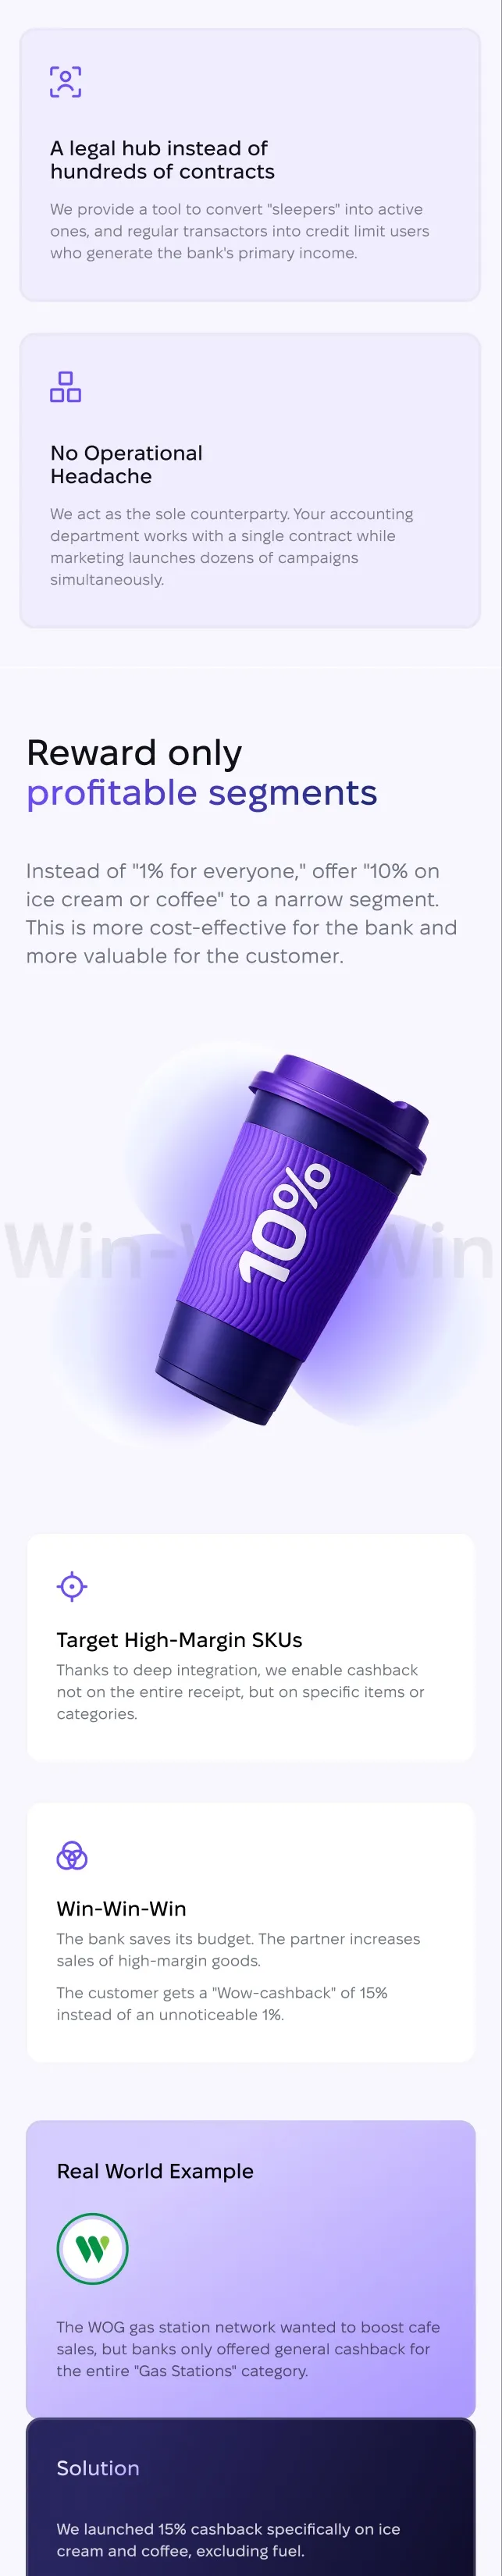
Segments in place of “1% for everyone”
We heardThe strongest proof is a live case: 15% cashback on coffee and ice cream at WOG gas stations, while banks offered only generic cashback on the whole category.
We did“Reward only profitable segments”: 10% on coffee for a narrow segment beats 1% for everyone — with the WOG case as a “win-win-win” example.
07/ 12Desire
An interface with no IT queue
We heardBanks fear dependence on IT. But segmentation in the admin panel is still in progress — a “15-minute launch” promise is off the table.
We didAn honest promise: “a convenient rewards management system” — we show only what already works.
08/ 12Desire
Security and deployment
We heardSecurity questions come up at every meeting, and conservative banks are wary of the cloud.
We did“We store no sensitive data” in place of technical details. On-premise deployment on the bank’s servers comes first; the cloud is just an option.
09/ 12Desire
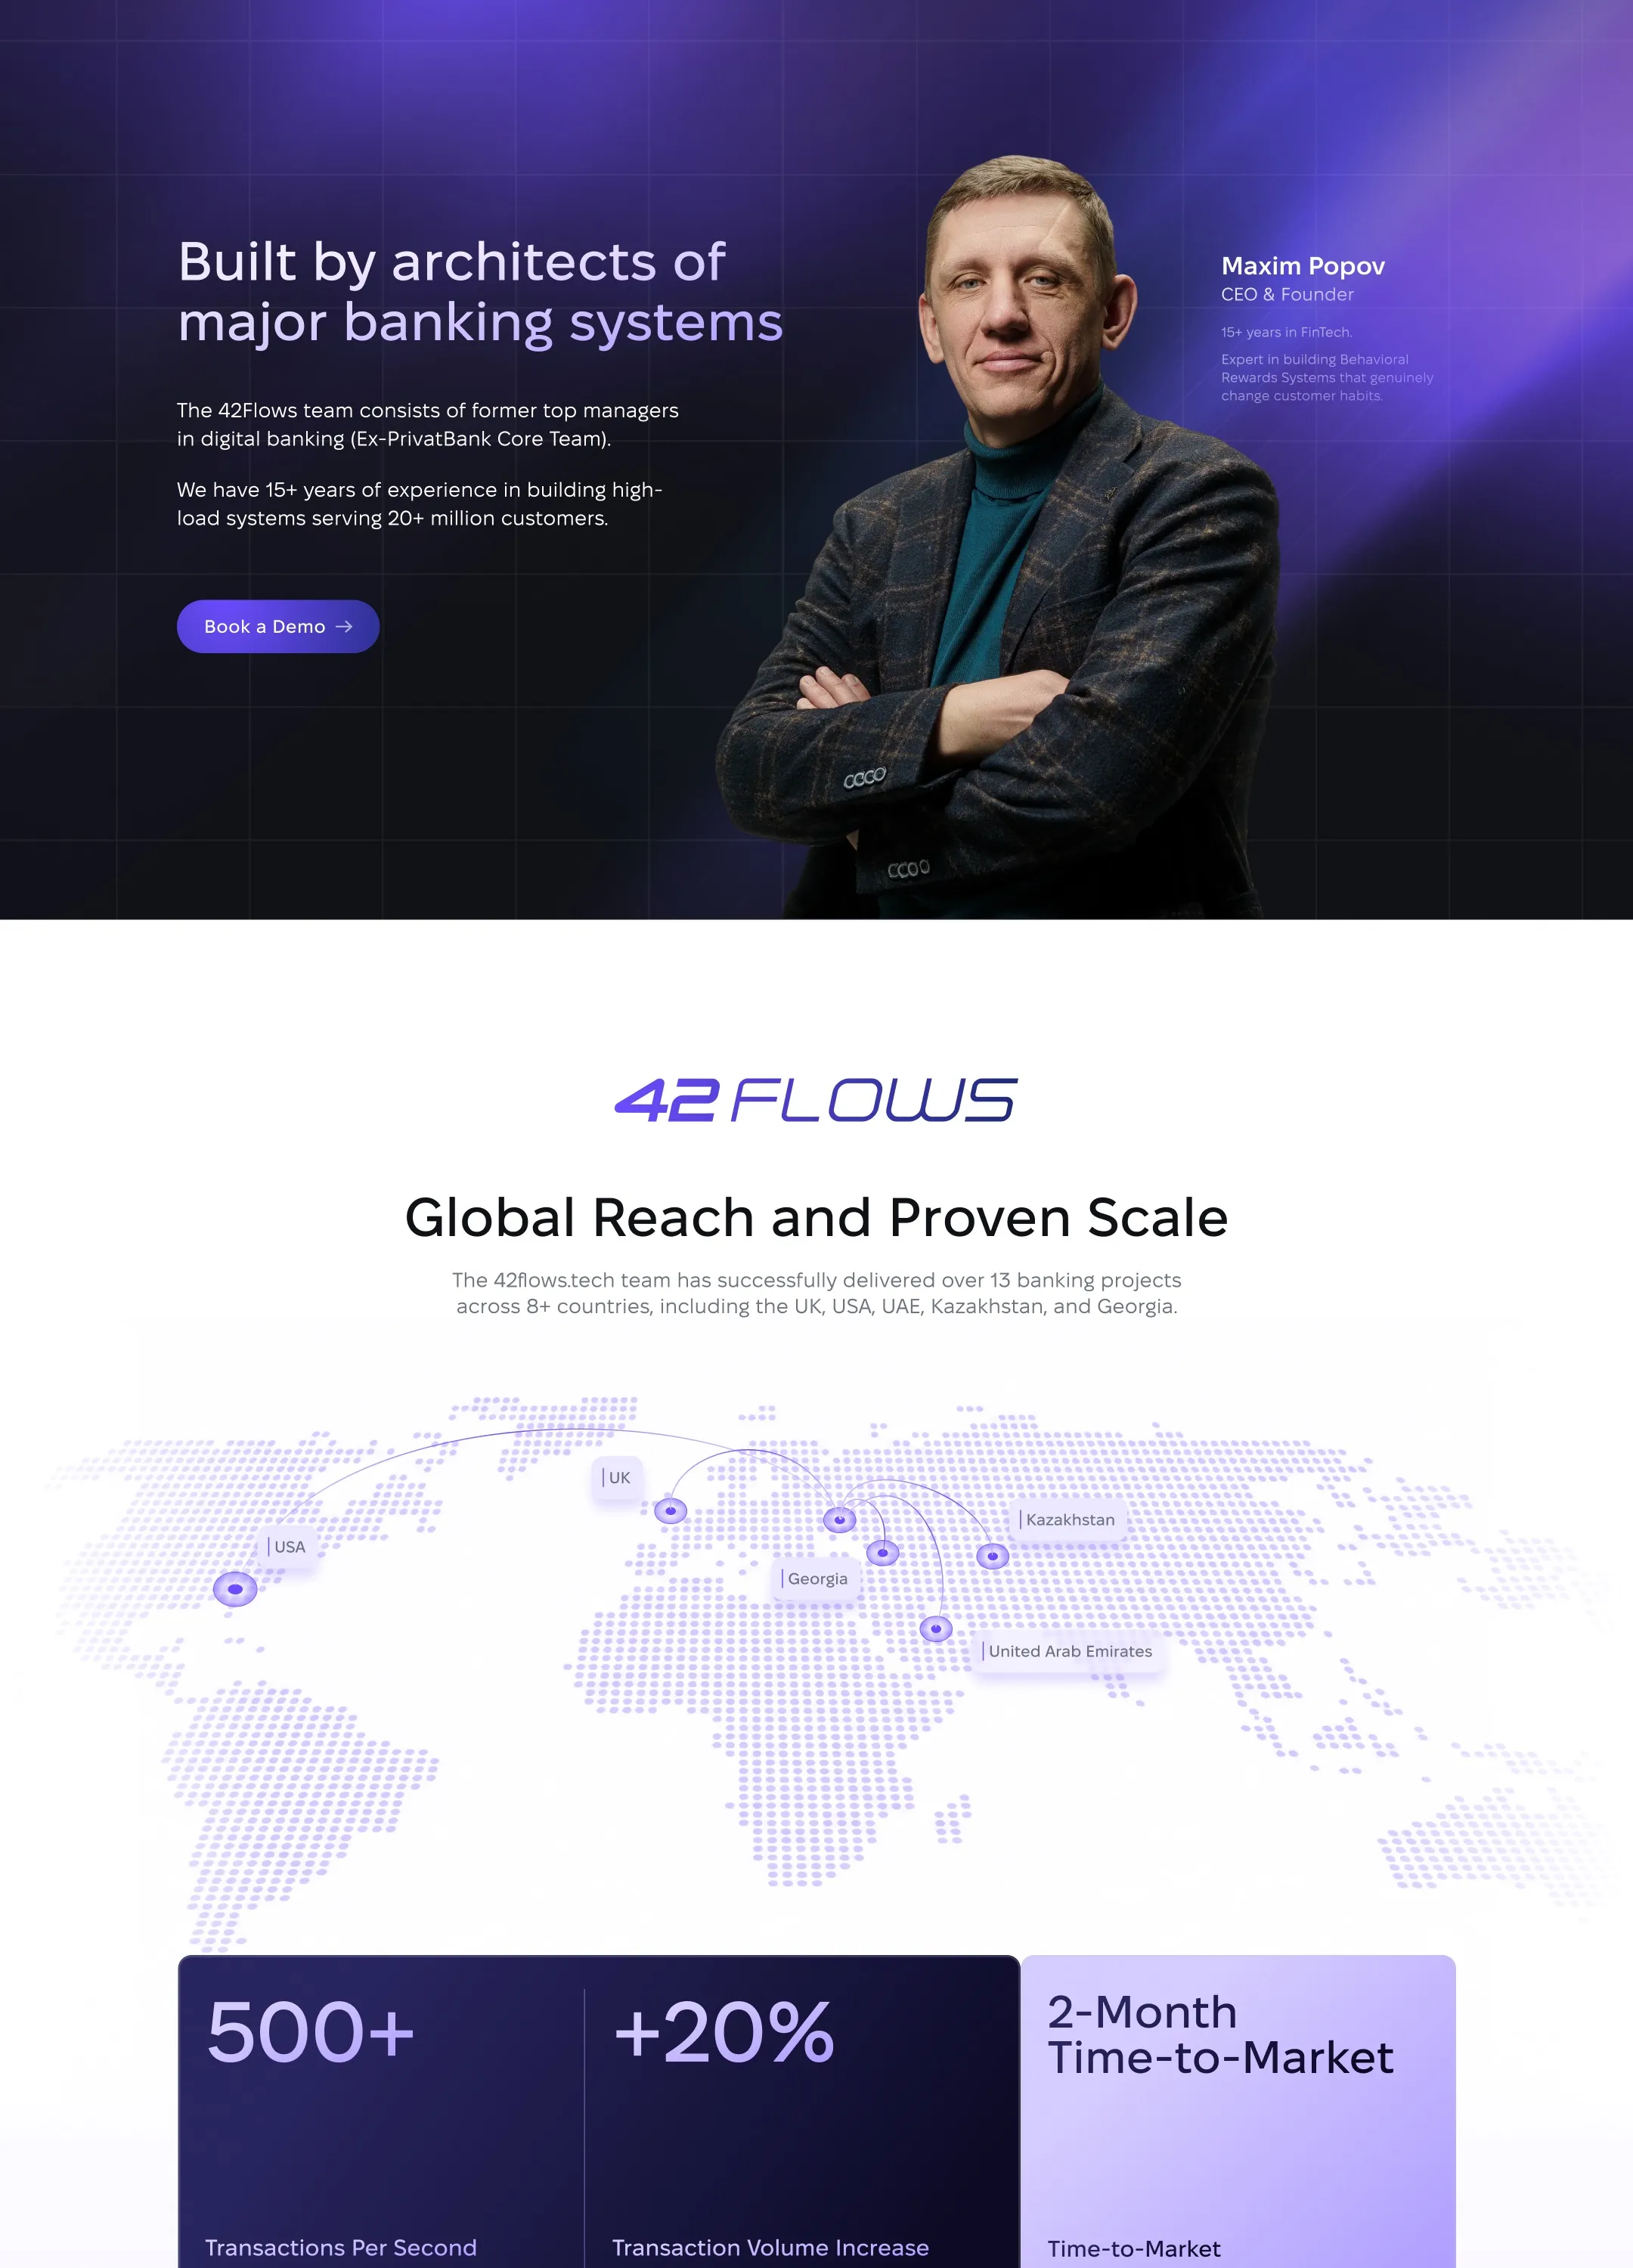
Trust: people and scale
We heardTrust in the founder and personal contact are a critical trigger. The PrivatBank name means little in Europe without a sense of scale.
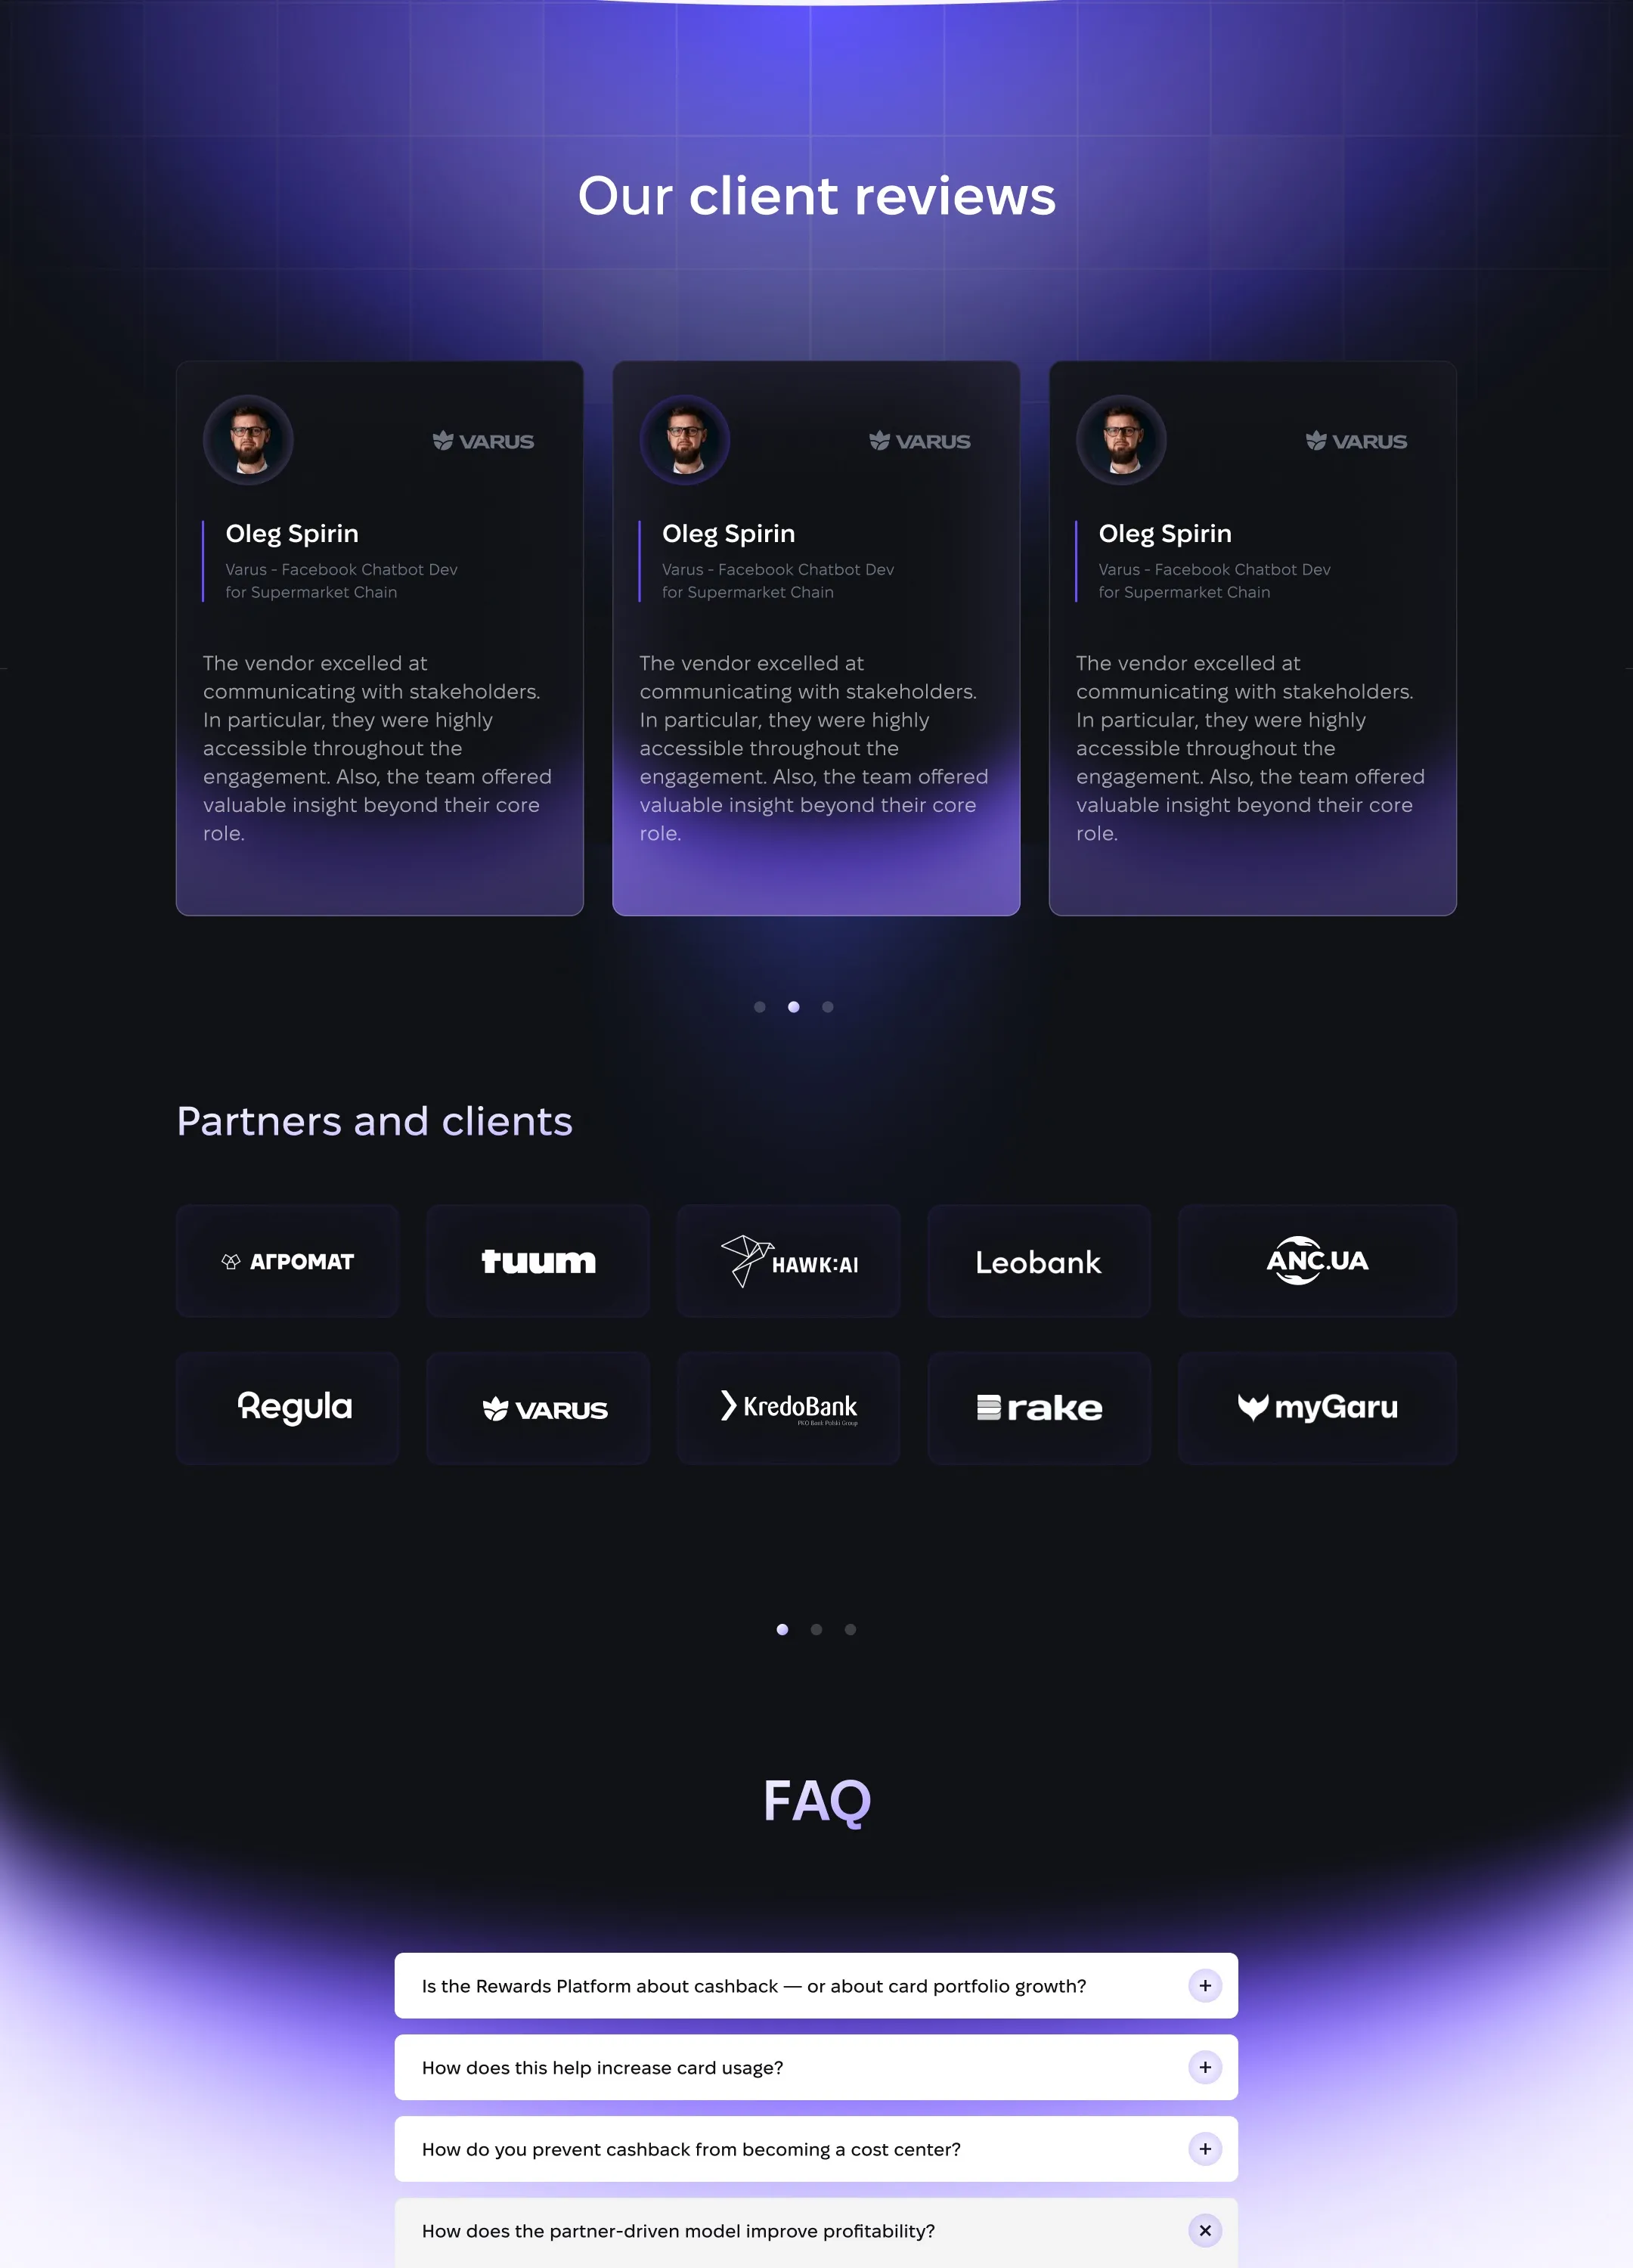
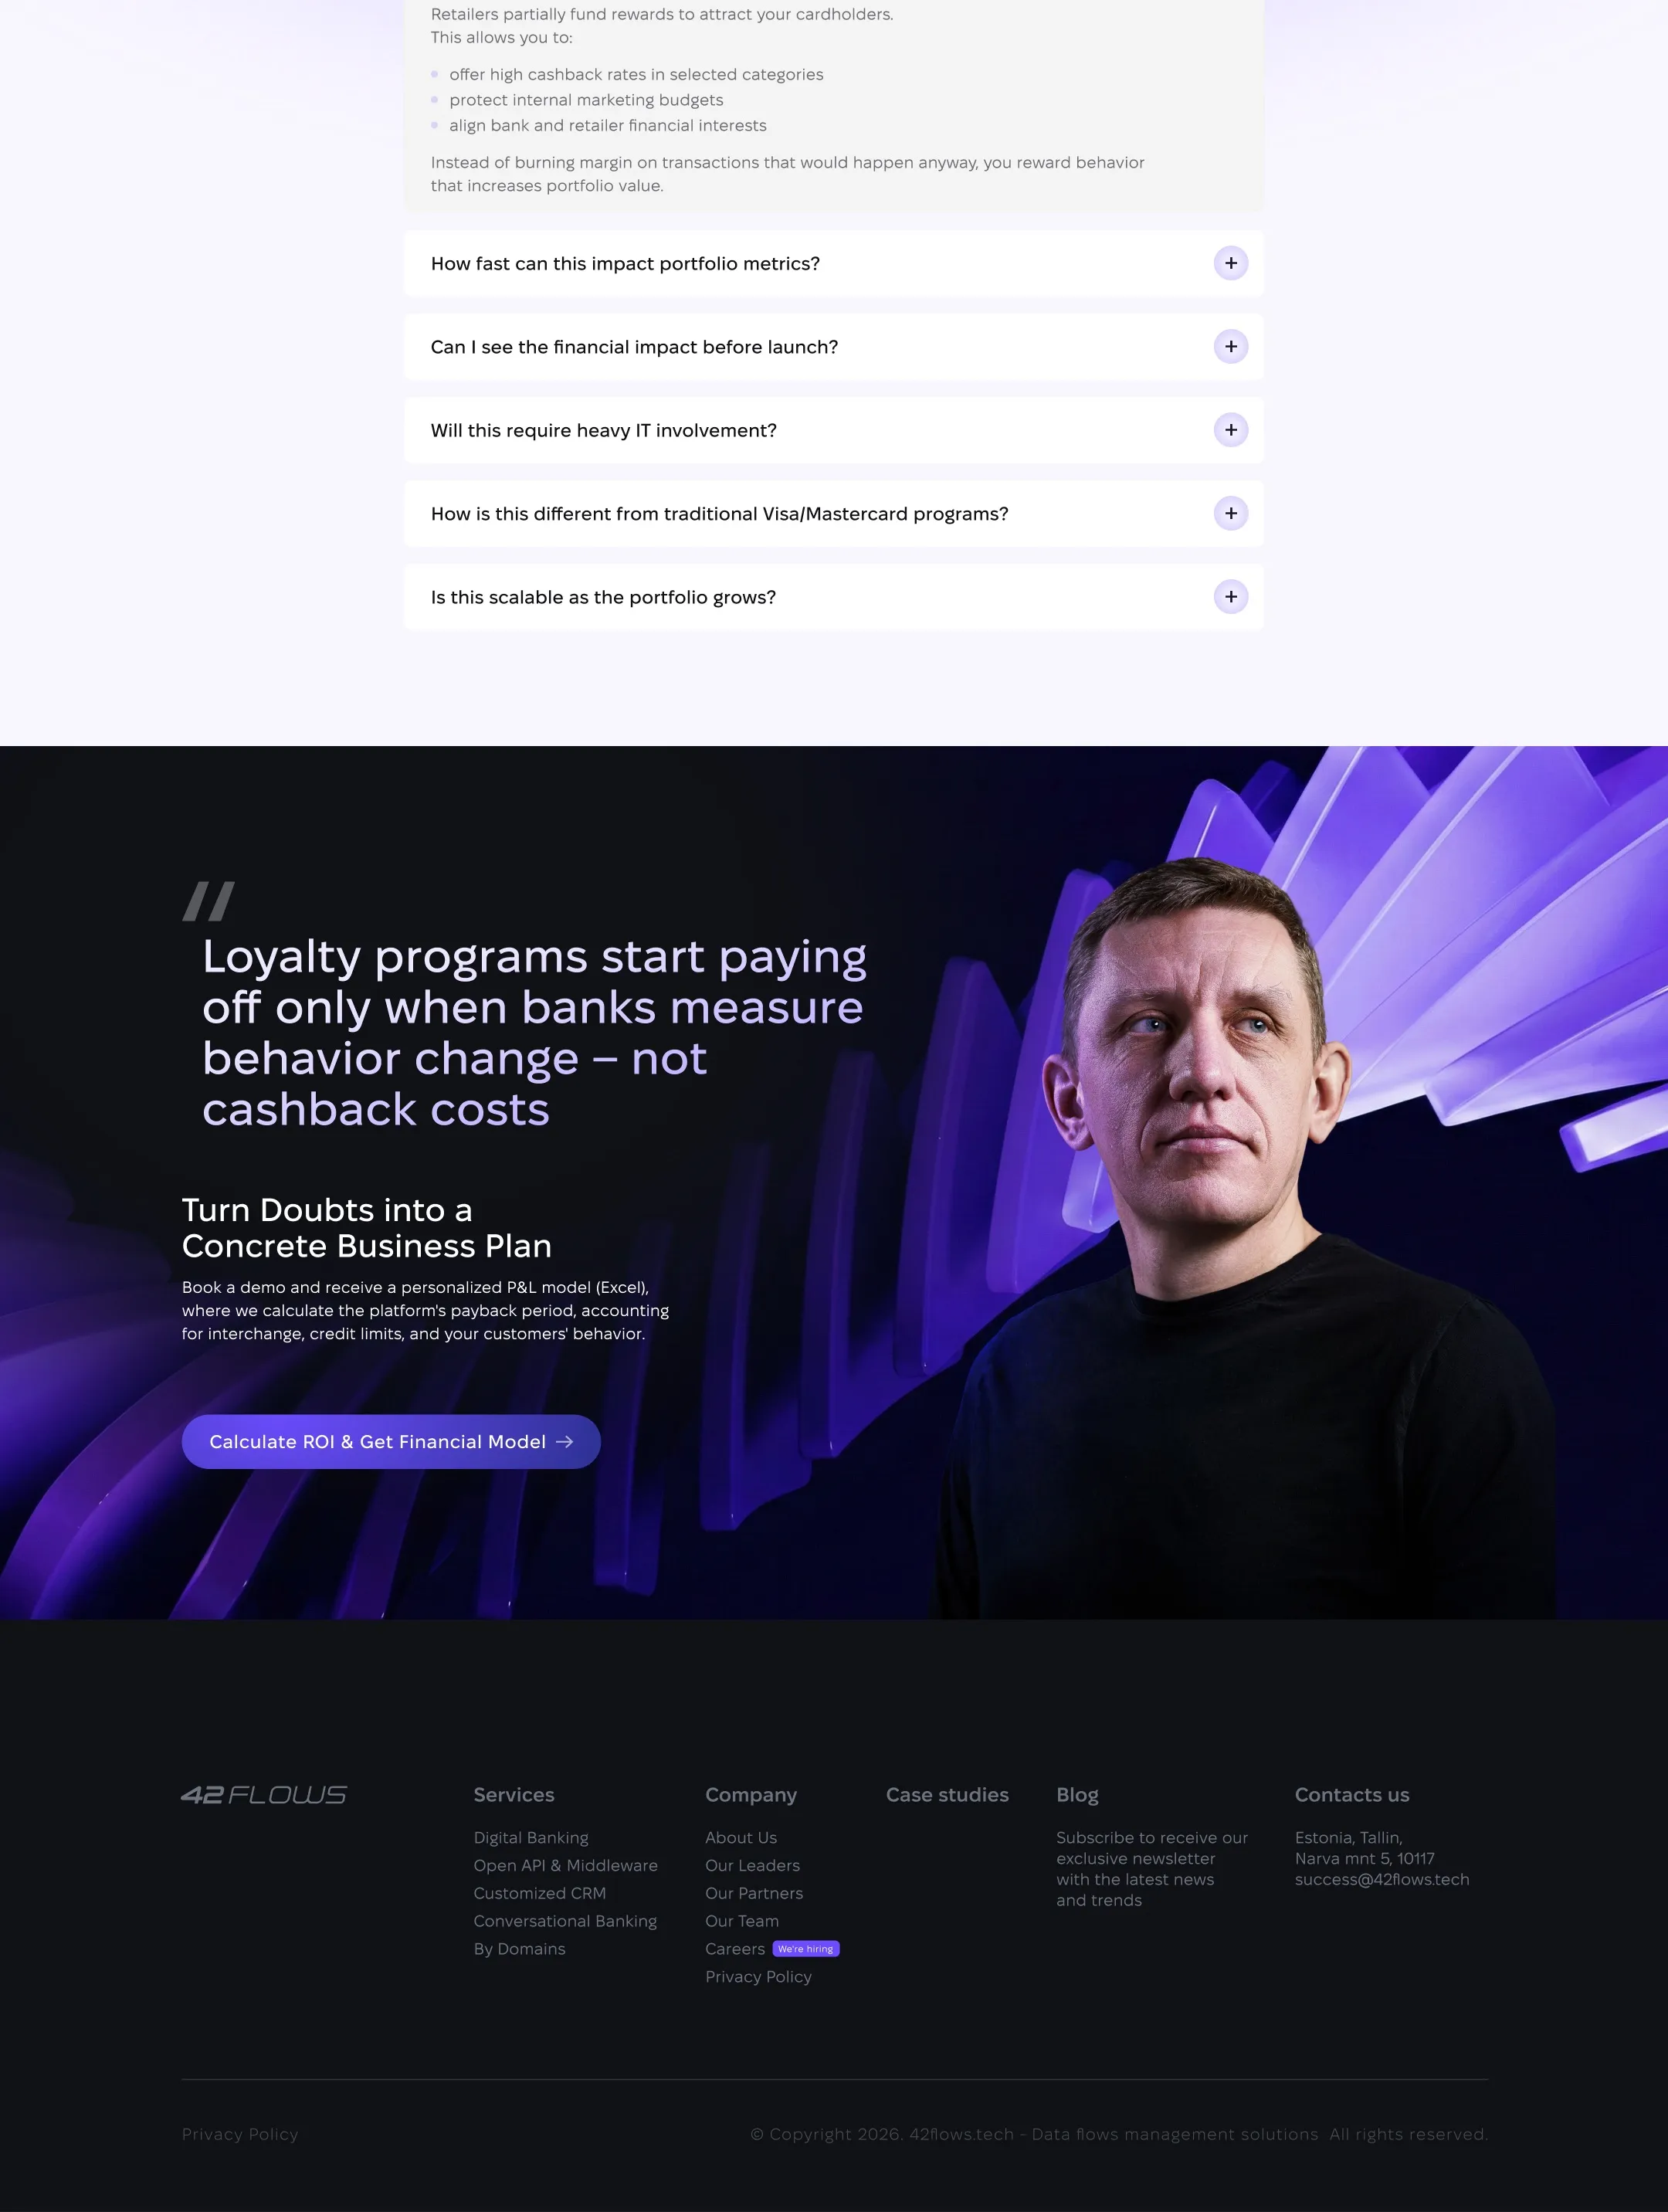
We didThe founder on the page, a team of ex-PrivatBank people, 13+ banking projects in 8+ countries. Ongoing implementations are honestly marked “In Progress.”
10/ 12Action
Implementation in phases
We heardMost launch time goes into accounting and approvals; the code is the quick part.
We didFour phases with timelines and an outcome for each — from architecture to scaling — so the process is predictable.
11/ 12Action
Objections go into the FAQ
We heardBanks ask the same things: why not build in-house, is it secure, what about the legacy banking system, won’t cashback become a cost.
We didAn FAQ built from real objections — from “we have our own developers” to “cashback loses money.”
12/ 12Action
Final action: calculate your ROI
We heardWithout a financial model sales don’t move, so the first meeting starts with one.
We did“Calculate ROI and get a financial model”: the bank receives an Excel file with the payback period on its own portfolio.
Brand identity
The page became the platform for the identity
Three visual directions: “system control,” “engineering approach,” “simplicity.” We chose engineering — the product as a system of modules. Each 3D object carries one message from the page and moves from the website into posts and other materials.
-
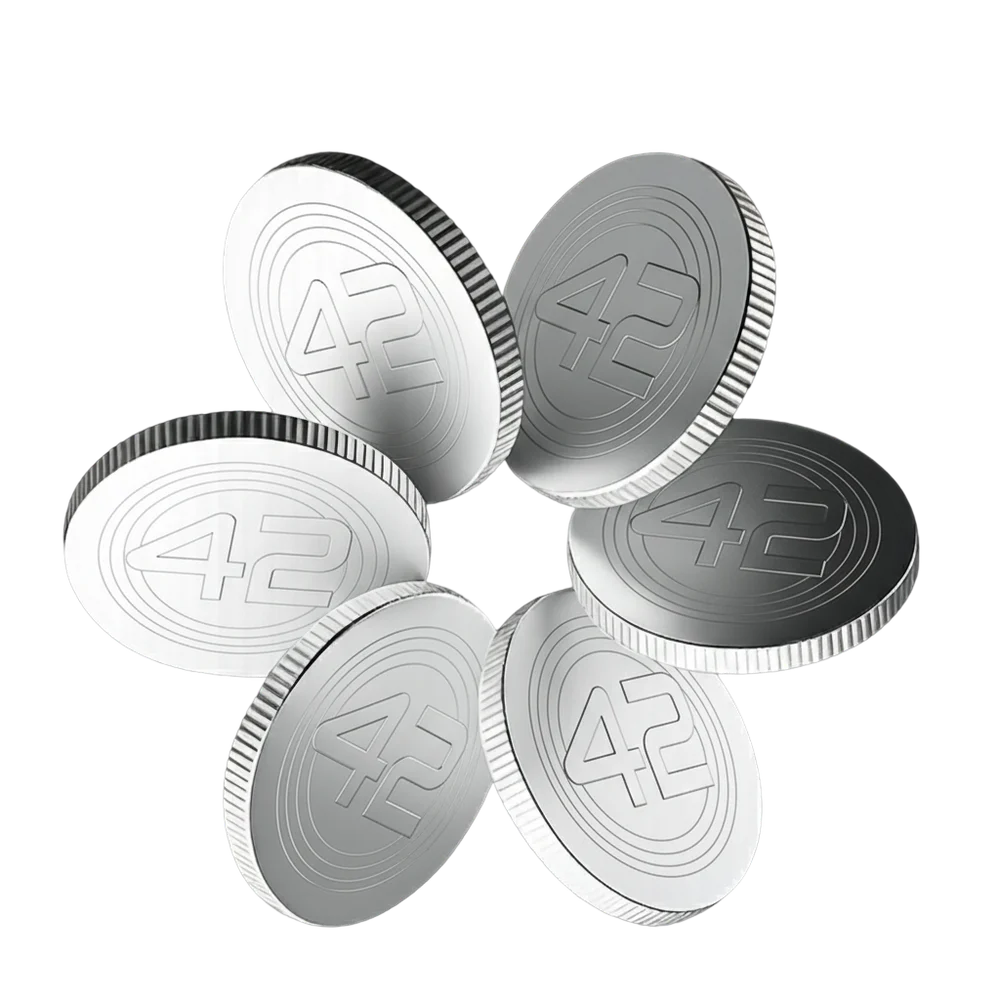
A “42” flower made of coinsRewards that add up to a system -
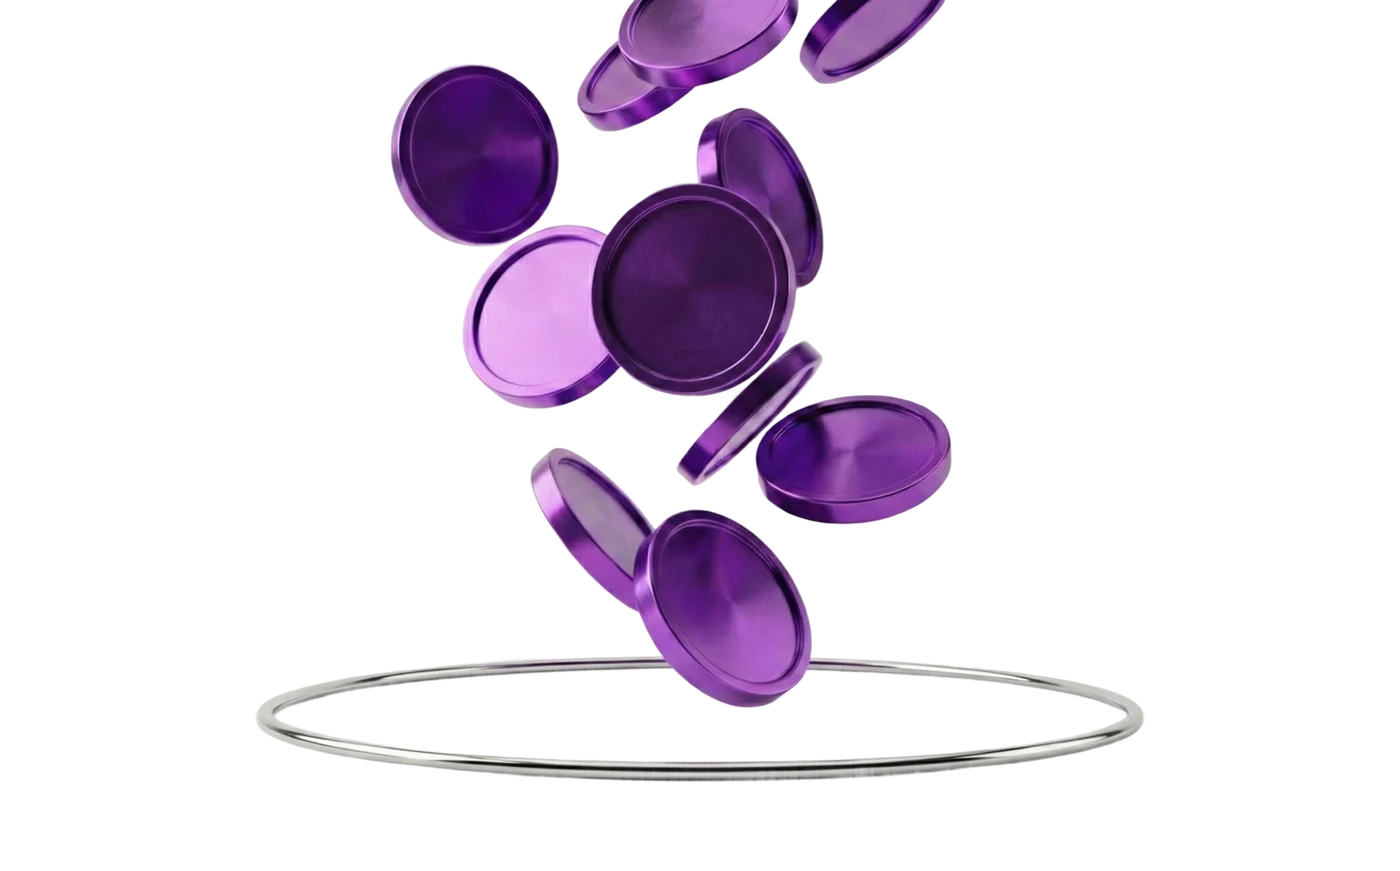
Coins above a ringPartner rewards: the retailer pays -
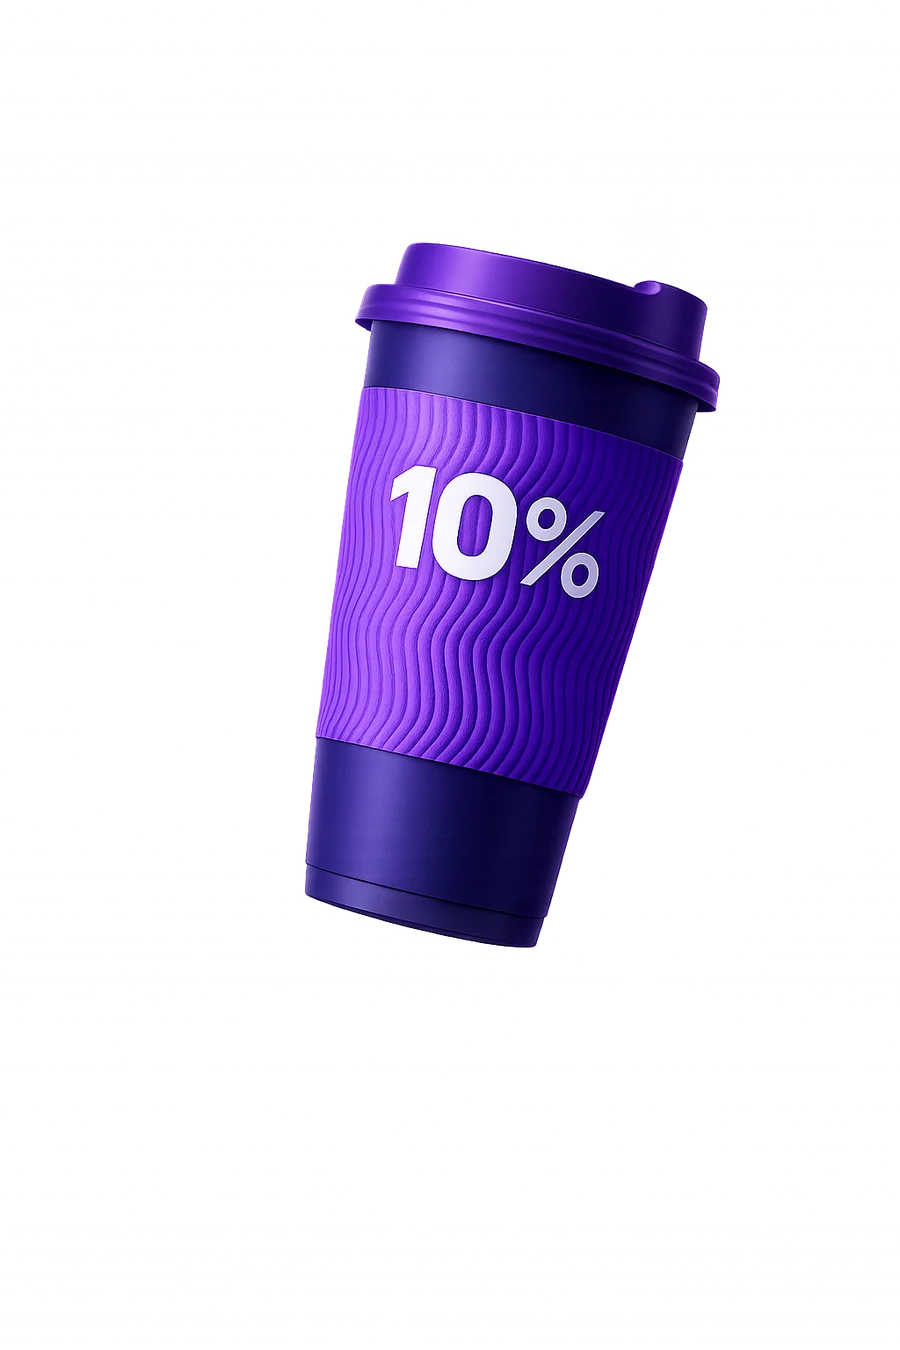
The “10%” cupSegments: generous where it’s profitable -
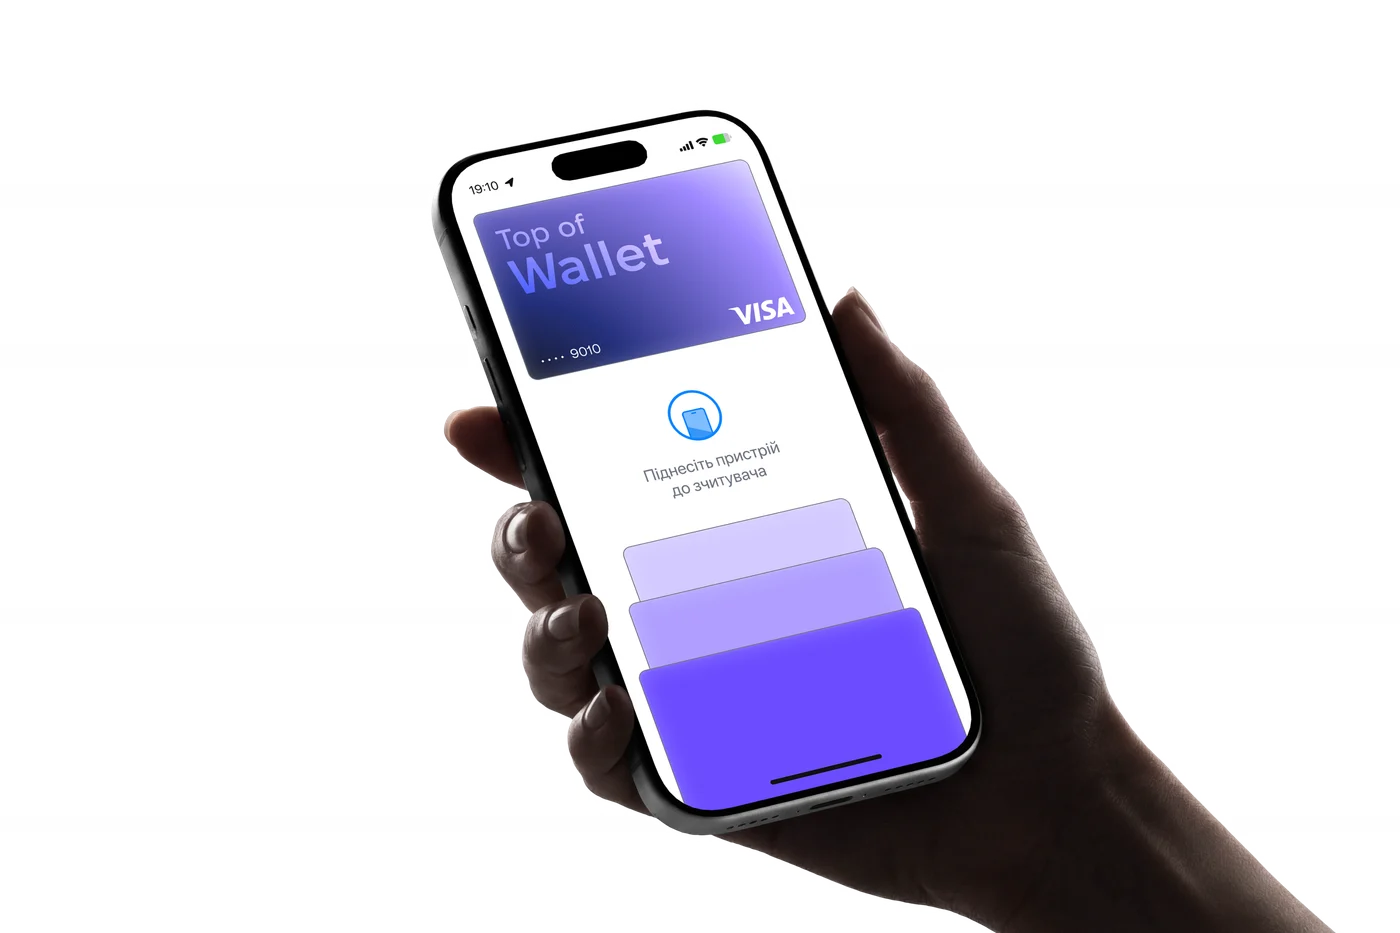
Top of WalletThe platform’s goal: become the main card in the wallet -
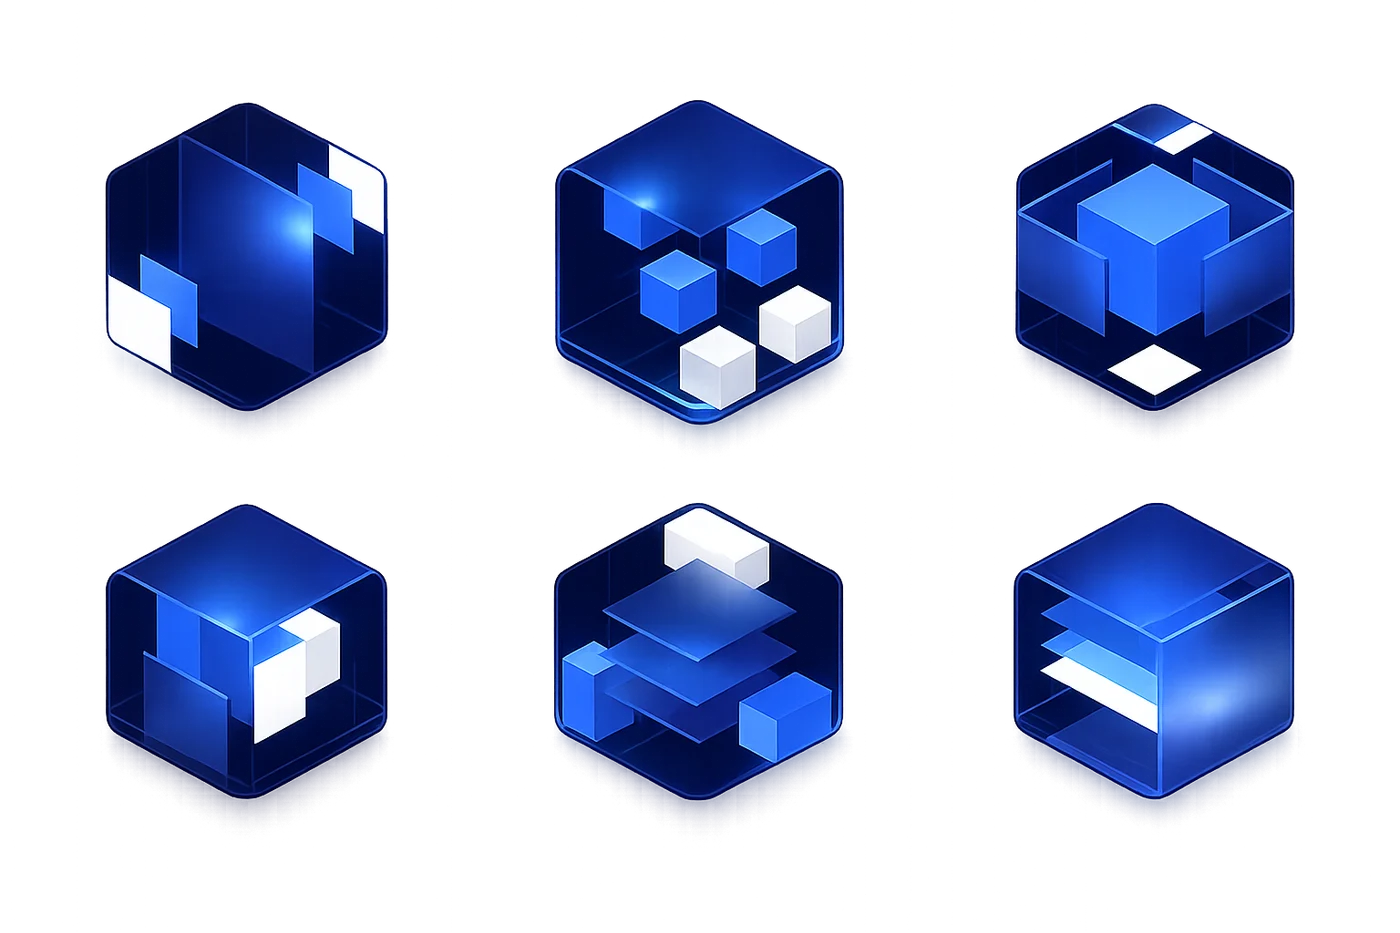
Module cubesInfrastructure: integration, security, deployment
Result
We validated the 42Flows team’s hypotheses about a rewards platform and turned them into a new positioning: 42Flows offers banks a platform that changes customer behavior.
The Rewards Platform page is live on 42flows.tech and has taken this positioning to market. It speaks the bank’s language: the problem, a behavioral CRM, money before the contract, partners, security and a clear path to launch. The identity grew out of it and is already being scaled to posts and other materials.
What we’ll do for you
Turn a strong product into more sales
If you have a strong product, but customers don’t see its value and marketing falls short of expectations, we’ll take over this area as your external marketing director. We’ll help define whom to sell to and what, how to stand out from competitors and which acquisition channels to develop. The result: managed marketing with clear priorities, ownership of execution and a focus on winning customers and growing revenue.
- 01 Marketing partner Priorities, budget and metrics.
- 02 Positioning Hypotheses validated through interviews.
-
 03 Sales page A page that carries the positioning into sales.
- 04 Brand identity A visual system for posts and materials.
Team
- Agency
- DOGMA
- Product
- Marketing Partner
- Scope
- Strategic session, in-depth interviews, positioning, text prototype, website design, brand identity, 3D visuals
- Client
- 42Flows